


A mandatory audit is an audit of the financial statements of companies that by law must publish or file them with an auditor's report (Art. 1(1)(16) of the Audit Law, Закон № 2258-VIII). Key Solutions in Kyiv checks whether your company falls under this rule and organises the mandatory audit end to end: a partner audit firm entitled to perform statutory audits carries it out and signs the report, while we prepare the books and support you through to publication.
+38 (068) 777-14-74 Telegram WhatsApp
In brief
- Who must: public-interest entities, public joint-stock companies, large and medium-sized enterprises, natural monopolies, extractive companies and some small financial and state-sector entities.
- Other small and micro companies and sole proprietors (ФОП) have no mandatory audit duty under Law No. 996-XIV. For them an audit is an initiative engagement, ordered by a bank, investor or buyer.
- What we do: confirm your category, organise the mandatory audit with a partner firm that signs the report, prepare the books and statements, and support you through to publication. We carry out initiative audits under ISA ourselves.
- Timing: preparation starts in Q4 of the reporting year, before the year-end stock count.
- Where to start: send last year's balance sheet, income statement and average headcount.
Which companies need a mandatory audit
A mandatory audit is required every year for companies that publish annual financial statements with an auditor's report under Art. 14(3) of the Accounting Law (Закон № 996-XIV). Size category and type of activity decide, whatever the form of ownership.
Who publishes statements with an auditor's report, Law No. 996-XIV
| Group | Who is included | Rule |
|---|---|---|
| Public-interest entities | Listed or publicly offered issuers, banks, insurers, pension funds and larger financial institutions, large enterprises | Art. 1 |
| Special activities | Public joint-stock companies, national natural monopolies, extractive industries | Art. 14(3), para. 1 |
| Large and medium | Large non-issuers and all medium-sized enterprises | Art. 14(3), para. 2 |
| Small financial institutions | Micro and small financial institutions and pension funds | Art. 14(3), para. 3 |
| State sector and groups | Small state-sector enterprises where the law requires an audit; parents of large groups | Art. 14(3), paras 4, 6 |
Important. An LLC (ТОВ) or private joint-stock company (ПрАТ) needs a mandatory audit when its size or activity puts it into one of these groups. The Accounting Law applies to legal entities and to branches and representative offices of foreign legal entities (Art. 2(1)), so sole proprietors (ФОП) have no such duty. For a foreign company's office in Ukraine, we assess the duty from its statements and activity at the consultation.
How to determine the size category
Under Art. 2(2) of Law No. 996-XIV, figures for the year before the reporting year must meet at least two of three criteria.
Criteria under Art. 2(2) of Law No. 996-XIV (two of three)
| Category | Assets / net revenue | Employees |
|---|---|---|
| Micro | up to EUR 350,000 / EUR 700,000 | up to 10 |
| Small | up to EUR 4m / EUR 8m | up to 50 |
| Medium | up to EUR 20m / EUR 40m | up to 250 |
| Large | over EUR 20m / EUR 40m | over 250 |
- Euro thresholds are converted at the average official NBU rate for the period.
- The category changes after two consecutive years outside the current category's criteria; a new company uses its figures at the date of its first annual statements.
Publication deadlines, tax filing and fines
Public-interest entities (except large non-issuers), public joint-stock companies, natural monopolies and extractive companies publish audited annual statements by 30 April; the other obliged companies by 1 June (Art. 14(3)). The statements stay on the company's website for at least six years (Art. 14(7)).
Corporate income tax payers on this list file them with the State Tax Service (ДПС) by 10 June (Tax Code of Ukraine (ПКУ), cl. 46.2).
A breach of the publication rules carries a fine of 1,000–2,000 tax-free minimum incomes, UAH 17,000–34,000, and UAH 34,000–51,000 for a repeat breach within a year (Code on Administrative Offences (КУпАП), Art. 163-16). Under martial law and for three months after it, missed publication deadlines carry no liability (Law No. 2115-IX (Закон № 2115-IX), cl. 1(4-1)), except for state unitary enterprises and companies more than 50% state-owned. The statements are then published within three months after martial law ends (cl. 1(4-2)).
What preparation for a mandatory audit includes
- A written conclusion on your size category and audit duty.
- Review of the accounting policy and framework: national standards (НП(С)БО) or IFRS where Art. 12-1 of Law No. 996-XIV requires it.
- Reconciliation of the trial balance with source documents.
- Year-end count and confirmation of receivables and payables.
- Correction of errors, or restoration of accounting records where there are gaps.
- The auditor's file and answers to auditor queries.
Preparation stages
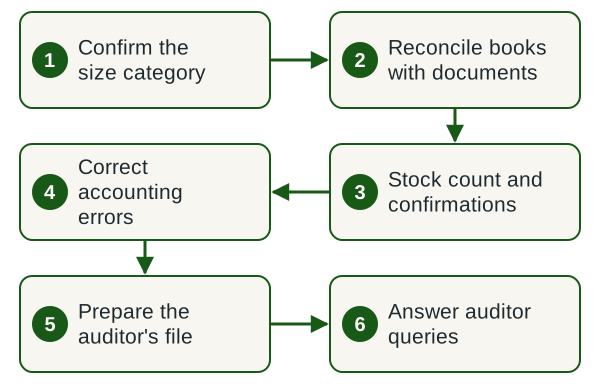
- Confirm the size category From last year's statements and activity, we state in writing whether an audit applies.
- Reconcile books with documents Trial balance, accounting policy and documents for material transactions.
- Stock count and confirmations Year-end count and counterparty confirmations before the balance sheet date.
- Correct accounting errors A list of corrections with journal entries, agreed with the chief accountant.
- Prepare the auditor's file Documents, balance breakdowns and explanations on the auditor's request list.
- Answer auditor queries Support and written explanations during fieldwork.
Timing
In our experience, preparation is best started in Q4. The count takes place before the balance sheet date: inventories, receivables and payables within three months, cash and financial investments within two (Inventory Regulation (Положення № 879), cl. 10). The exact timeline depends on volumes, the state of documents and counterparties' replies.
What affects the cost
- Volume of transactions and state of source documents.
- Reporting framework and any group consolidation.
- Number of sites for the stock count.
- Time left before the count and the publication deadline.
Market benchmarks for the audit fee itself are in our article How much does a financial statement audit cost.
What we need from you
- Last year's balance sheet, income statement and average headcount.
- Read-only access to the accounting system (BAS or another).
- Accounting policy order and the annual trial balance.
- Key contracts, bank statements and meeting minutes on the auditor's appointment.
- Previous auditor's reports and a contact person.
What you get
- A written conclusion on the audit duty and publication deadline.
- A list of corrections with journal entries.
- Count reports, signed confirmations and the auditor's file.
How to choose an auditor for a mandatory audit
A mandatory audit is performed by a firm entered in the relevant section of the public Register of Auditors and Audit Entities (Реєстр аудиторів та суб'єктів аудиторської діяльності), kept by the Audit Public Oversight Body of Ukraine (Arts 6(1), 20, Law No. 2258-VIII). The Register has four sections (Art. 21(1)):
- section 1 — auditors;
- section 2 — audit entities;
- section 3 — audit entities entitled to carry out mandatory audits of financial statements;
- section 4 — the same for public-interest entities.
The auditor is appointed by the general meeting, by the supervisory board where the law provides for it, or by another highest body (Art. 29(1)). Key Solutions organises the mandatory audit end to end: a partner audit firm listed in the relevant section of the Register carries out the audit and signs the report, and we prepare the books and statements, handle the auditor's queries and support you until publication. You can check the partner's Register entry before signing the contract. For companies with no statutory requirement, we carry out an initiative audit of financial statements under ISA (МСА) for a bank, investor, buyer or the owners.
Order a mandatory audit, fully managed
We run the full cycle: preparing the books and statements, the audit and report by a partner firm entitled to perform statutory audits, and publication. The fee is agreed individually after we review your statements.
Legal framework
Rules the work relies on
- Law of Ukraine No. 996-XIV On Accounting and Financial Reporting (Закон № 996-XIV), Art. 1, 2, 14 — scope, size categories, publication.
- Law of Ukraine No. 2258-VIII On Audit of Financial Statements and Auditing Activity (Закон № 2258-VIII), Art. 1, 6, 20, 21, 29 — mandatory audit, the Register.
- Code on Administrative Offences (КУпАП), Art. 163-16 — fines.
- Law No. 2115-IX (Закон № 2115-IX), cl. 1(4-1), 1(4-2) — martial-law deadlines.
- Tax Code of Ukraine (ПКУ), cl. 46.2 — filing with the tax authority.
Risks, and why to hand preparation to a contracted team
Misstatements left uncorrected lead to a qualified or adverse opinion, and an incomplete stock count can lead to a disclaimer. That report is published and read by banks, counterparties and the tax authority. Preparation is run by a team under a contract that fixes scope, timing and responsibilities; legal questions go to the group's lawyers.
Why Key Solutions
- Company
- ТОВ «АУДИТОРСЬКА ФІРМА «КЕЙ СОЛЮШНЗ», a Ukrainian limited liability company, EDRPOU code 39610085. The company's details are public in the Unified State Register (ЄДР).
- Contract
- We work under a contract: scope, timing and responsibilities are fixed before the start. Client information is protected by professional secrecy (Art. 11 of Law No. 2258-VIII).
- Group
- We are part of Innova Consulting Group: legal matters are handled by legal.ua, crypto-asset taxation by crystal.tax.
- Office
- Our office is at 77 Velyka Vasylkivska St, Kyiv. We serve clients across Ukraine remotely. The specialists who run engagements are listed on the Our employees page.
FAQ
Which companies in Ukraine need a mandatory audit?
Companies that must publish annual statements with an auditor's report under Art. 14(3) of Law No. 996-XIV: public-interest entities, public joint-stock companies, large and medium-sized enterprises, natural monopolies, extractive companies, small financial institutions, some small state-sector enterprises and parent companies of large groups.
Does an LLC (TOV) need a mandatory audit?
Only if its size or activity puts it into one of those groups: medium-sized or large under Art. 2 of Law No. 996-XIV, a financial institution, a securities issuer, a natural monopoly or an extractive company (Art. 14(3)). The same applies to a private joint-stock company.
Does a Ukrainian subsidiary or representative office of a foreign company need one?
A Ukrainian subsidiary is a Ukrainian legal entity and is assessed like any other company, by size category and type of activity. Law No. 996-XIV also covers branches and representative offices of foreign legal entities (Art. 2(1)); for such an office we assess the duty from its statements and activity at the consultation.
What happens if audited financial statements are not published?
Art. 163-16 of the Code on Administrative Offences sets a fine of UAH 17,000–34,000, or UAH 34,000–51,000 for a repeat breach. Under martial law and for three months after it, missed deadlines carry no liability (Law No. 2115-IX), except for state-controlled companies, and publication follows within three months after martial law ends.
How can I check whether an audit firm may perform a mandatory audit?
Audit firms are listed in the public Register of Auditors and Audit Entities. For a mandatory audit the firm must appear in section 3, and for public-interest entities in section 4 (Art. 21(1) and Art. 6(1) of Law No. 2258-VIII).
What is the difference between a mandatory and an initiative audit?
A mandatory audit is required by law, performed by a firm from section 3 or 4 of the Register, and published with the statements. An initiative audit is ordered by owners, a bank, an investor or a buyer, and the report goes to the client. Both follow ISA.
Related services
Check whether you need an audit
Tell us your type of activity and attach last year's balance sheet and income statement. We will confirm whether a mandatory audit applies and propose a plan covering preparation, the partner firm's audit and publication, with timing and cost.
Request a consultation +38 (068) 777-14-74 Telegram WhatsApp


Comments