


Accounting restoration is the rebuilding of source documents, ledgers and reports for past periods from bank data, state registers, counterparties and inventory counts. Key Solutions restores bookkeeping and tax records in Kyiv and remotely, up to amended tax returns.
+38 (068) 777-14-74 Telegram WhatsApp
In short
- When you need it: the books were not kept or kept with errors, the accountant left without a handover, documents are lost, or a tax audit, sale or liquidation is ahead.
- What you get: restored documents and ledgers reconciled with the bank and the Unified Register of Tax Invoices (ЄРПН), corrected reports and amended returns.
- Timing: a plan by period, fixed in the contract after the review.
- Cost: depends on the period, transactions, whether the database survived, VAT and inventory counts.
- Where to start: book a consultation and prepare bank statements and the last filed reports.
When accounting records count as lost or neglected
Records are unusable when they cannot support the figures in filed reports. Accounting must run without breaks from registration to liquidation (Art. 8(1) of Law No. 996-XIV), and the Tax Code of Ukraine (ПКУ) prohibits tax reports built on data that source documents and ledgers do not confirm (clause 44.1 of the Tax Code). Typical cases:
- the books were kept only in part (bank or payroll only) or not at all;
- the accountant left without handing over the database, or it was damaged without a backup;
- source documents were lost, damaged or left where there is no access;
- the tax authority sent a request or scheduled an audit, and the figures cannot be supported;
- the company is changing owners; for a buyer, the review can be part of a financial and tax due diligence.
Full and partial restoration
| Format | When it fits | What we restore |
|---|---|---|
| Accounting review | Change of accountant, purchase of a stake | Reconciliation with reports, bank and ЄРПН; list of gaps |
| Partial restoration | Gaps in some areas over several months | Bank and cash, settlements, payroll or stock |
| Full restoration | Books not kept or database lost | All areas, ledgers, financial and tax reports |
| Tax records | Discrepancies in VAT, income tax or ЄСВ returns | Tax ledgers, ЄРПН reconciliation, amended returns |
What is included
- Analysis of documents and the database, reconciliation with filed reports.
- A report on the state of the books with errors and recommendations.
- Rebuilding of accounts and entries; duplicates requested from counterparties and invoices downloaded from ЄРПН.
- Tax records: VAT, corporate income tax, personal income tax and single social contribution (ЄСВ).
- Fixed assets and stock with inventory counts, bank and cash, payroll.
- Amended returns and corrected financial statements.
How we restore the books
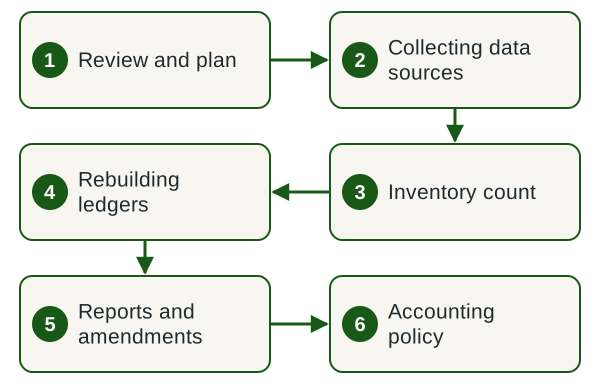
- Review and plan Documents and databases listed, gaps mapped, a plan drawn up by period.
- Collecting data sources Bank statements, electronic tax accounts, registers, contracts, counterparty requests.
- Inventory count Assets, liabilities, cash and stock, with count sheets and reports.
- Rebuilding ledgers Analytical and synthetic accounts, period closing, data matched.
- Reports and amendments Liabilities recalculated, amended returns and corrected statements filed.
- Accounting policy Policy, document flow schedule, storage and backup rules.
The quality test comes from Art. 9(3) of Law No. 996-XIV: analytical accounts must match the synthetic accounts at the end of each month. The depth of restoration follows the tax authority's assessment window of 1,095 days after the filing deadline, or 2,555 days for transfer pricing, CFC and non-resident payment controls (clause 102.1 of the Tax Code); under martial law it is suspended for some audits (subclause 69.36, subsection 10, Section XX).
Timing
Timing depends on the number of periods, the volume of documents, the number of bank accounts and how fast counterparties reply. After the review we set a timeline for each stage in the contract. If the tax authority has already been notified of lost documents, the work is planned within the 90-day period described below.
What affects the cost
| Factor | Effect on workload | What to prepare |
|---|---|---|
| Period | Each month adds closing, reconciliations and reports | List of periods and last filed reports |
| Transactions | More documents mean more reconciliations and requests | Bank statements for the period |
| Accounting database | A surviving database cuts the work | A copy or an export |
| VAT registration | Adds tax credit reconciliation with ЄРПН | Tax invoices and VAT returns |
| Stock, fixed assets, payroll | Counts and HR data add separate work | Count sheets, orders, payroll records |
We name the price after the review and fix it in the contract before work starts.
What we need from you
- Bank statements for the whole period.
- Filed reports and acceptance receipts.
- A copy of the accounting database, if it survived.
- Contracts with main counterparties and the documents you have.
- HR documents and payroll records.
- The notice of lost documents to the tax authority, if filed.
- A contact person who answers questions and signs counterparty requests.
What you get
- Restored documents or duplicates, and a list of those that could not be restored.
- Ledgers that match at the end of each month.
- Corrected financial statements and amended tax returns.
- A report on errors found, amounts to pay or reduce, and audit risks.
- An accounting policy and document storage rules.
Get a quote for restoration
Give the period, your tax regime and whether the database survived. We will reply with the review scope, timeline and cost.
Lost documents: 5 days and 90 days
After documents are lost, damaged or destroyed early, the taxpayer notifies the tax authority in writing within five days, with proof of the event, and then has 90 calendar days to restore them; audit deadlines move meanwhile by up to 120 days (clause 44.5 of the Tax Code). Documents not restored, or not provided before an audit ends, are treated as missing when the reports were prepared (clause 44.6).
Companies whose documents were lost in, or cannot be removed from, combat areas or temporarily occupied territories can file a notice under subclause 69.28, subsection 10, Section XX, after which documentary audits of those periods are suspended. For VAT, only invoices registered in ЄРПН support tax credit, and an invoice can be included within 365 days of its date (clause 198.6), so older VAT periods come first.
Amended returns
| Method | Self-assessed penalty | When to pay |
|---|---|---|
| Amended return for the period | 3% of the underpayment (cl. 50.1); penalty and interest waived until martial law ends (subcl. 69.38) | Before filing the amended return |
| Correction in the next return | 5% of the underpayment (cl. 50.1); penalty and interest waived until martial law ends (subcl. 69.38) | With that return's liability |
During a documentary audit, amended returns for the audited period cannot be filed (clause 50.2), so errors are best corrected before an audit starts.
Legal basis
Rules the work relies on
- Arts. 8 and 9 of Law No. 996-XIV: continuous accounting, the director's responsibility, source documents and ledgers.
- Arts. 44, 50 and 102 of the Tax Code: retention and restoration of documents, amended returns, the limitation period.
- Subclauses 69.28, 69.36 and 69.38, subsection 10, Section XX of the Tax Code: combat areas, extended periods, penalty relief.
- Arts. 163-1 and 164-2 of the Code of Administrative Offences (КУпАП): liability of officers.
- Section I of the Regulation on Inventory of Assets and Liabilities: mandatory inventory counts.
Risks, and the case for a contracted team
A mistake in restoration costs more than the work. A missing document takes the related expenses and tax credit with it (clause 44.6), a duplicate without mandatory details does not support the transaction, and unreconciled ledgers create new discrepancies. Fines add to this: UAH 1,020 for failing to keep documents, UAH 2,040 for a repeat within a year (clause 121.1 of the Tax Code), and UAH 136 to 255 on officers for missing accounting (8 to 15 non-taxable minimum incomes under Art. 164-2 КУпАП, at UAH 17 each under clause 5, subsection 1, Section XX of the Tax Code).
The director stays responsible for accounting (Art. 8(3) of Law No. 996-XIV), so we work under a contract that sets the plan by period, deadlines and who answers for each stage. Tax disputes and court cases go to the group's lawyers at legal.ua.
Why Key Solutions
- Company
- ТОВ «АУДИТОРСЬКА ФІРМА «КЕЙ СОЛЮШНЗ», a Ukrainian limited liability company, EDRPOU code 39610085. The company's details are public in the Unified State Register (ЄДР).
- Contract
- We work under a contract: scope, deadlines and liability are agreed before work starts. Client information is protected by professional secrecy (Art. 11 of Law No. 2258-VIII).
- Group
- We are part of Innova Consulting Group: legal matters are handled by legal.ua, crypto-asset taxation by crystal.tax.
- Office
- Our office is at 77 Velyka Vasylkivska St., Kyiv. We serve clients across Ukraine remotely. The specialists who run projects are listed on the Our employees page.
Frequently asked questions
What is accounting restoration and when is it needed?
Accounting restoration rebuilds ledgers, tax returns and financial statements for past periods from surviving source documents and outside data: the bank, state registers and counterparties. A company needs it when the books were not kept, were kept with breaches, or documents were lost.
How much does accounting restoration cost?
The cost depends on the number of periods, the volume of transactions, whether the accounting database survived, VAT registration and whether an inventory count is needed. We name the price after reviewing the documents and fix it in the contract. For an estimate, send bank statements and the last filed reports.
How long does accounting restoration take?
It depends on the number of periods, the volume of source documents and how fast counterparties reply. After the review we draw up a plan by period and fix the timeline in the contract. If the tax authority has been notified of lost documents, we plan the work within the 90-day restoration period.
What should a company do after losing source documents?
Under clause 44.5 of the Tax Code, notify the tax authority in writing within five days of the event, attaching proof of it, and restore the documents within 90 calendar days from the day after the notice arrives. Audit deadlines move meanwhile by no more than 120 days.
Can an amended return be filed without a penalty?
Yes. From 1 August 2023 until martial law ends, subclause 69.38, subsection 10, Section XX of the Tax Code releases a taxpayer who corrects errors on its own from the clause 50.1 penalty and late-payment interest, provided Art. 50 is followed. Amended returns for a period under documentary audit cannot be filed.
What if documents remain in a combat zone or an occupied territory?
Subclause 69.28, subsection 10, Section XX of the Tax Code lets the company file a free-form notice, signed by the director and the chief accountant, that the documents cannot be removed, listing the circumstances, periods and documents. After the notice, documentary audits of those periods are suspended.
Related services
Let's discuss restoring your books
Give the period, your tax regime, whether the database survived and whether the tax authority has sent requests. We will reply with a review plan, timeline and cost estimate.
Book a consultation Order the service +38 (068) 777-14-74 Telegram WhatsApp