An audit before a tax inspection is a review of the books, primary documents and tax returns before the State Tax Service arrives, so errors are found and fixed before the inspector sees them. Key Solutions prepares the company, supports it through the inspection on the accounting side and prepares the figures for objections to the report.
+38 (068) 777-14-74 Telegram WhatsApp
In short
- When you need it: you are on the inspection schedule, an order or tax query has arrived, a VAT refund is claimed, or a reorganisation is ahead.
- What you get: discrepancies with amounts and Tax Code references, restored documents, amended returns and a plan for the inspection.
- Timing: notice comes at least 10 calendar days ahead, so start once the schedule is published. Our timing is fixed in the contract.
- The fee is agreed individually: it depends on the taxes and periods, the volume of documents and support during the inspection.
- Where to start: send us the order or notice from the tax office, if you have one, and tell us your tax regime.
How to know an inspection is coming
A planned inspection is visible in advance: para. 77.1 of the Tax Code requires it to appear in the annual schedule, which the State Tax Service publishes by 25 December of the previous year. High-risk taxpayers can be scheduled once a year, medium-risk once every two years and low-risk once every three years (para. 77.2).
A copy of the order and a written notice with the start date must be delivered at least 10 calendar days before the inspection (para. 77.4). During martial law, documentary and factual inspections are held only where safe access to premises, documents and stock counts is possible (subpara. 69.2-2 of para. 69, subsection 10, section XX of the Tax Code).
What the service includes
- analysis of the schedule, order, notice or tax query: which taxes, periods and type of inspection;
- reconciliation of returns with registers and primary documents and their mandatory details (Art. 9 of Law No. 996-XIV), including payroll and employment records;
- a list of missing documents and their restoration: documents not provided before the inspection ends are treated as absent (para. 44.6);
- a check of the latest inventory counts, since late or poor counts are an offence under Art. 164-2 of the Code of Administrative Offences;
- an estimate of possible additional tax and amended returns while the inspection has not started (para. 50.2);
- a document pack and written explanations, and a briefing for your accounting team;
- support during the inspection on the accounting side, and figures and documents for objections to the report.
Legal work on a dispute, such as legal objections, an appeal to a higher tax authority or court, is handled by our sister company legal.ua (tax disputes).
How we work
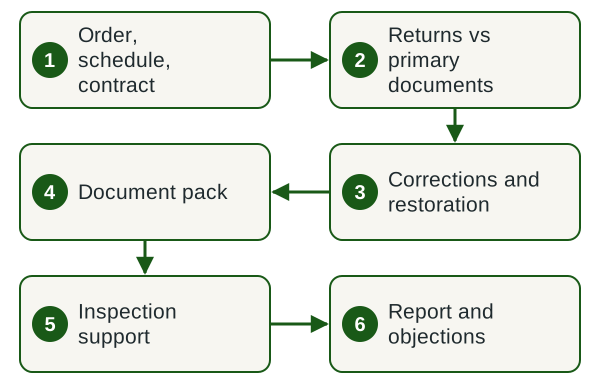
- Order, schedule and contract. We identify the type of inspection, taxes and periods and fix scope and timing in the contract.
- Returns against primary documents. We go through returns, registers and documents the way the inspector will.
- Corrections and restoration. We restore documents and prepare amended returns where the Tax Code still allows it.
- Document pack. We assemble documents on the subject of the inspection and written explanations.
- Inspection support. We work with the inspectors on the accounting side and record every document handed over.
- Report and objections. We analyse the report and prepare figures and documents for objections within the deadline.
Timing and cost
We fix our timing in the contract after reviewing the order and the documents. It depends on the number of taxes and periods, the volume of primary documents and how fast counterparties respond. If the order has already arrived, we agree a tight schedule and start with the taxes under inspection. The fee is agreed individually and depends on the type of inspection, taxes and periods, the state of primary documents, risky transactions such as VAT refunds or foreign trade, and whether you need support during the inspection and objections afterwards.
What we need from you
- the order, notice or tax query, if you already have it;
- tax returns and financial statements for the periods under inspection;
- read-only access to the accounting system and bank statements;
- the contract register, HR files and payroll records;
- a responsible person who can approve explanations quickly.
Result
- a report listing discrepancies, possible additional tax and Tax Code references;
- restored documents and amended returns;
- a document pack with written explanations;
- a plan for the inspection: who talks to the inspectors, how copies are provided, what is recorded;
- after the report, figures and documents for objections.
Your rights during the inspection
Inspectors may start an on-site inspection only after presenting the referral, a copy of the order and their service IDs (para. 81.1 of the Tax Code). The duty to provide documents arises once the inspection starts, and copies are taken under an inventory (paras. 85.2, 85.7).
If violations are found, a report is issued (para. 86.1) and the company has 10 working days to object (para. 86.7). A tax assessment notice follows within 15 working days (para. 86.8) and can be appealed to a higher tax authority within 10 working days (paras. 56.2, 56.3).
Legal framework
Rules the work relies on
- Arts. 75–82 of the Tax Code: types of inspections, schedule, grounds for unscheduled inspections, access and duration.
- Arts. 17 and 85 of the Tax Code: taxpayer rights and handling of documents during an inspection.
- paras. 44.1–44.7 of the Tax Code: documentary support for tax figures, retention and restoration of documents.
- Art. 86, paras. 56.2–56.3 and 102.1 of the Tax Code: report, objections, assessment notice, appeal, limitation period.
- Art. 9 of Law No. 996-XIV: primary documents and their mandatory details.
Why hand this to a team under contract
During an inspection, the costliest items are documents that are missing when it ends: the related figures are treated as unsupported, followed by additional tax, penalties and late-payment interest. The second typical loss is a missed deadline, since 10 working days for objections pass quickly. A team under contract goes through the documents the way the inspector will, knows which corrections the Tax Code still allows and keeps the deadlines.
Why Key Solutions
- Turnkey, with no extra hassle
- We take the whole task: documents, calculations, reporting and correspondence with the State Tax Service. You make the decisions, provide source documents and sign; we do the rest and contact you only when it matters.
- We take on the tax office
- Information requests, blocked tax invoices, inspection reports: we prepare explanations, rework documents and appeal until the issue is closed. Where the law is in dispute, we work together with the group's lawyers.
- We see it through
- Your case stays on track: the specialist running it remains with you, even if an inspection or audit drags on for months. Statutory audits are performed, and the report signed, by a partner audit firm entitled to perform them; we handle preparation and support through publication, so you deal with one team from start to finish.
- Boutique-level involvement
- A senior specialist runs your project personally (see the Our employees page), backed by 14 years of Innova group practice in 50+ countries. Non-standard tasks are our field: where you hear “it can’t be done”, we look for a lawful way, and group companies cover the rest: legal.ua for legal matters, crystal.tax for crypto-asset taxation.
- Your affairs stay yours
- Information about your company, turnover, payroll and counterparties reaches neither competitors nor third parties. We disclose only what the law or a procedure requires, and the contract says so.
- Faster and right the first time
- Full involvement: your specialist learns your books, contracts and business, so documents and reports are ready on time with no rework. The group's 14 years of experience let us get right the first time what takes some firms three attempts.
Frequently asked questions
How do I know whether my company will face a tax inspection this year?
Check the schedule of planned documentary inspections that the State Tax Service publishes by 25 December of the preceding year (para. 77.1 of the Tax Code). Updates are allowed once in the first and once in the second quarter and appear by the 30th day of the quarter's last month (Ministry of Finance Order No. 524 of 02.06.2015).
How much notice is given before a tax inspection?
For a planned documentary inspection, the company receives a copy of the order and a notice with the start date at least 10 calendar days in advance (para. 77.4 of the Tax Code). A factual inspection is carried out without notice (para. 80.1).
What is an audit before a tax inspection?
It is an independent review of the books, primary documents and returns before the tax authority starts its inspection. The goal is to find discrepancies and restore missing documents in time, because documents not provided before the inspection ends are treated as absent (para. 44.6 of the Tax Code).
How is this different from a tax audit of the company?
An audit before an inspection is tied to a specific inspection: the taxes and periods in the order, the Tax Code deadlines and the documents the inspector will request. A tax audit of the company is wider and covers all taxes and periods.
How far back can the tax authority check a company?
As a general rule, the tax authority can assess tax within 1,095 days after the filing deadline, or after actual filing if the return was late (para. 102.1 of the Tax Code). For transfer pricing and controlled foreign companies under Articles 39 and 39-2, the period is 2,555 days.
How long do I have to object to an inspection report?
Objections, additional documents and explanations go to the tax office that carried out the inspection within 10 working days after the report is received (para. 86.7 of the Tax Code). A standing commission reviews them within 10 working days and replies.
Related services
Let's prepare for your inspection
Tell us your tax regime, whether an order or query from the tax office has arrived, and which taxes and periods it covers. We will reply with a document list, a preparation plan and a quote.
Book a consultation Order the service +38 (068) 777-14-74 Telegram WhatsApp