

Accounting and reporting for a Polish sp. z o.o. means full books kept in Polish and in zloty, monthly JPK_V7 VAT files, CIT advances and the annual CIT-8 return, ZUS contributions for employees, the CRBR beneficial owner register, and annual financial statements that must be prepared, approved and filed with the KRS on statutory deadlines. Key Solutions coordinates this work for owners from Ukraine: a Polish accountant keeps the books and files the returns, while we set the tasks, control deadlines and figures, and prepare owner reporting.
Request a tailored proposal Telegram
In brief
- For: owners from Ukraine who have or plan an sp. z o.o. in Poland, and groups where a Polish company operates alongside a Ukrainian LLC.
- What we do: take over the books from the previous accountant, set up a deadline calendar, control VAT, CIT, ZUS and the annual accounts, prepare the company for a statutory audit when one is required, and give the owner clear reporting.
- Who signs: a Polish accountant keeps the books and files returns, the accountant and the management board sign the financial statements, and a Polish audit firm performs any statutory audit. The CRBR notice is filed by a person authorised to represent the company.
- Fees: a tailored proposal after a short description of the company, with no public price list.
- To start: tell us whether the company is already entered in the KRS, whether it is VAT-registered, how many transactions and employees it has per month, and who keeps the books now.
What Polish law requires from an sp. z o.o.
An sp. z o.o. always keeps full books (księgi rachunkowe) under the Accounting Act; no simplified regime applies to it. The books are kept in Polish and in the Polish currency (Art. 9 of the Accounting Act). A company registered in Poland follows Polish rules even when its owner and board live in Ukraine.
| Obligation | What and when | Legal basis |
|---|---|---|
| Books of account | Full księgi rachunkowe in Polish and in PLN, a written accounting policy (polityka rachunkowości) | Arts. 2, 9, 10, Accounting Act |
| VAT (JPK_V7) | A VAT payer files JPK_V7M for each month by the 25th of the following month; quarterly filers submit JPK_V7K with the quarterly return by the 25th after the quarter | Art. 99(1)–(3), VAT Act |
| CIT advances | Monthly by the 20th for the previous month; small taxpayers and companies in their first year may pay quarterly by the 20th after the quarter | Art. 25(1)–(1c), CIT Act |
| CIT-8 return | Filed electronically by the end of the third month after the tax year (31 March for a calendar year), with any balance of tax paid by the same date | Art. 27(1) and (1c), CIT Act |
| ZUS contributions | ZUS DRA declaration, RCA, RSA, RPA reports and payment by the 15th of the following month | ZUS deadlines for payers with legal personality |
| Annual financial statements | Prepared within 3 months of the balance sheet date, approved by the shareholders' meeting within 6 months, filed with the KRS within 15 days of approval | Arts. 52, 53, 69, Accounting Act |
| Beneficial owners (CRBR) | Notice within 14 days of the KRS entry and within 14 days of any change | AML Act, Ministry of Finance |
Deadlines and rates follow the laws in force on 9 October 2026: Accounting Act, Dz.U. 2026 item 522, CIT Act, Dz.U. 2026 item 554, VAT Act, Dz.U. 2026 item 1263, ZUS, Ministry of Finance, CRBR.
Compliance calendar for a Polish sp. z o.o.
Most monthly deadlines of a Polish company fall on three dates. When a deadline falls on a weekend or public holiday, it moves to the next working day.
| Date | What to file or pay |
|---|---|
| by the 15th | ZUS DRA, RCA/RSA/RPA reports and employee contributions for the previous month |
| by the 20th | CIT advance for the previous month (or quarter); PIT advances withheld from salaries (Art. 38(1), PIT Act) |
| by the 25th | JPK_V7M with the VAT return and VAT payment for the previous month |
| 31 January | PIT-4R and PIT-11 to the tax office, electronically only |
| end of February | PIT-11 to employees |
| 31 March | financial statements for the past year prepared; CIT-8 filed and CIT balance paid |
| 30 June | financial statements approved by the shareholders' meeting |
| 15 days after approval | statements, approval and profit distribution resolution, and the management report filed with the KRS |
PIT-4R and PIT-11 deadlines per the National Revenue Administration (KAS); annual accounts dates assume a calendar financial year.
VAT: registration, JPK_V7 and KSeF
A company that will be a VAT payer files the VAT-R registration before its first taxable transaction (Art. 96(1), VAT Act). The standard rate is 23 % (Art. 146ef), with reduced rates for certain goods and services.
- the small-business exemption applies while net sales in the previous and current year do not exceed PLN 240,000 (Art. 113(1) as amended from 1 January 2026); several activities are excluded from it (Art. 113(13)), so we check the status before the first invoice;
- JPK_V7 combines the sales and purchase records with the return; a monthly filer submits it by the 25th of the following month (podatki.gov.pl);
- supplies to VAT payers in other EU countries also require the VAT-UE recapitulative statement.
KSeF. Since 1 February 2026 structured e-invoices through the Krajowy System e-Faktur are mandatory in Poland. Taxpayers whose 2024 sales including VAT did not exceed PLN 200,000,000 could issue invoices outside KSeF until 31 March 2026, and from 1 April 2026 the obligation covers all other taxpayers. Until 31 December 2026 invoices outside KSeF are still allowed where sales documented by them do not exceed PLN 10,000 in a month (Arts. 145l and 145m of the VAT Act as amended by the Act of 5 August 2025, Dz.U. 2025 item 1203). For a company with a Ukrainian owner this means set-up KSeF access and an agreed procedure with the accountant on who issues invoices and from which system.
CIT: rates, advances and CIT-8
The standard CIT rate is 19 %. The 9 % rate is available to small taxpayers and to companies in their first year where revenue in the tax year does not exceed EUR 2 million; it does not apply to capital gains or to companies formed through restructuring or a contribution in kind. For 2026 the small taxpayer limit is PLN 8,517,000 and the revenue limit for the 9 % rate is PLN 8,431,000 (podatki.gov.pl, CIT rates and limits).
The alternative is the Estonian CIT (ryczałt od dochodów spółek): 10 % for small taxpayers or 20 % for others, payable when profit is distributed (podatki.gov.pl, Estonian CIT). It changes the company's accounting and reporting, so the regime is chosen with a tax adviser before the year starts; Polish tax matters within the group are handled by crystal.tax.
Payroll, ZUS and employees from Ukraine
As a payer with legal personality, an sp. z o.o. files ZUS DRA and the personal reports and pays contributions by the 15th of the following month (ZUS). PIT advances withheld from salaries are remitted by the 20th of the following month, and PIT-4R and PIT-11 are filed for the year.
- monthly payroll, ZUS contributions and PIT advances;
- employee registration with ZUS and data changes;
- for Ukrainian citizens working on the basis of temporary protection, the employer notifies the powiatowy urząd pracy within 7 days of the start of work (PIP, rules from 5 March 2026);
- annual PIT-4R and PIT-11 on time.
Annual financial statements and statutory audit
The management board ensures the annual financial statements are prepared within 3 months of the balance sheet date (Art. 52(1), Accounting Act). They are prepared electronically in the Ministry of Finance structure and signed by the person keeping the books and the board members with a qualified, trusted (profil zaufany) or personal electronic signature. The shareholders' meeting approves them within 6 months of the balance sheet date (Art. 53(1)), and the board files them with the KRS within 15 days of approval together with the approval and profit distribution resolution and the management report (Art. 69(1)).
Filing with the KRS is free through the Repozytorium Dokumentów Finansowych if the PESEL number of the filing person is disclosed in the KRS; otherwise the statements are filed for a fee through the S24 system (biznes.gov.pl). Board members who hold only a Ukrainian passport without a PESEL should plan for this in advance. If statements for two consecutive years remain unfiled after a court request, the registry court may dissolve the company without liquidation.
| When an sp. z o.o. needs a statutory audit | Previous year: at least 2 of 3 |
|---|---|
| Average employment | at least 50 full-time equivalents |
| Total assets at year end | equivalent of at least EUR 3,125,000 |
| Net sales revenue | equivalent of at least EUR 6,250,000 |
Thresholds per Art. 64(1)(4) of the Accounting Act as published in Dz.U. 2026 item 522. The audit is performed by a Polish audit firm and the report is signed by a biegły rewident (Act on Statutory Auditors, Dz.U. 2025 item 1891). Key Solutions prepares the books, the document pack and explanations for the audit and coordinates with the auditor until the statements are approved.
CRBR beneficial owner register
An sp. z o.o. notifies the Centralny Rejestr Beneficjentów Rzeczywistych of its ultimate beneficial owners within 14 days of the KRS entry and within 14 days of any change. The notice is filed by a person authorised to represent the company; it cannot be filed under a power of attorney, including by the accountant. The penalty for non-compliance is up to PLN 1,000,000 (Ministry of Finance). We prepare the beneficial owner and ownership structure data and make sure a board member files the notice on time, including after a change of shareholders.
Taking over the books of a Polish sp. z o.o.
A change of accountant is the most common reason clients come to us: the previous provider stopped responding, the owner cannot see the figures, or the annual accounts were not filed with the KRS. We run the handover from a checklist so the new accountant starts without gaps.
- books of account, trial balance at the handover date and the polityka rachunkowości;
- the latest approved financial statements, shareholder resolutions and KRS filing confirmations;
- CIT-8, JPK_V7 and filing confirmations (UPO) for recent periods;
- statements for all bank accounts, invoice registers and KSeF access;
- payroll records, ZUS documents, PIT-11 and PIT-4R where there are employees;
- a check of the CRBR entry and of the company's data in the KRS.
Discrepancies found during the handover are recorded in a memo with a correction plan and dates.
What the service includes
- diagnostics: VAT status, CIT regime, audit duty, KRS and CRBR filing history;
- selecting and setting up the work with a Polish accounting office: scope, document flow, month-end schedule, access rights;
- control of JPK_V7, CIT advances and ZUS contributions before each deadline;
- control of the annual financial statements, CIT-8, approval and KRS filing;
- audit preparation and coordination with the audit firm when an audit is required;
- management reporting for the owner: profit, cash flows, taxes payable;
- a financial statements pack for the Ukrainian owner's CFC report, IFRS reporting or consolidation with a Ukrainian LLC on request.
How we work
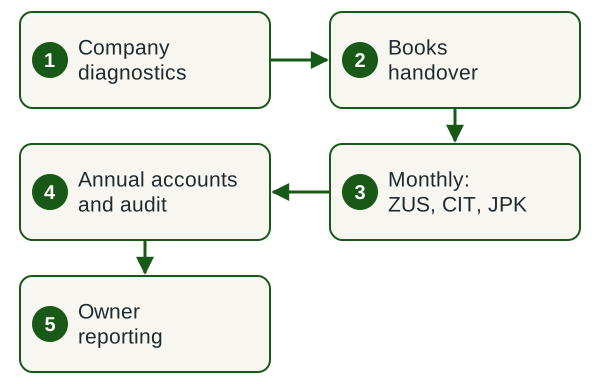
- Diagnostics. We obtain the KRS extract, the latest statements and returns, and determine the VAT and CIT regime and the company's obligations.
- Handover. We take over the books from the previous accountant against a checklist and record discrepancies.
- Monthly cycle. Documents, month-end close, ZUS by the 15th, advances by the 20th, JPK_V7 by the 25th.
- Annual reporting. Financial statements, CIT-8, audit where required, approval and KRS filing.
- Owner reporting. Management report and the CFC and consolidation pack.
Reporting for the owner in Ukraine
For an owner who is a Ukrainian tax resident, a Polish sp. z o.o. is often a controlled foreign company: a stake above 50 %, or above 10 % where Ukrainian residents together hold 50 % or more (sub-para. 39-2.1.2 of the Tax Code of Ukraine). Certified copies of the company's financial statements are attached to the CFC report (sub-para. 39-2.5.2), so the Polish annual accounts are needed in Ukraine as well. We prepare this pack together with our service for financial reporting for foreign companies.
Dividends from Poland are subject to 19 % withholding tax. The Ukraine–Poland convention of 12 January 1993 limits it to 5 % where the recipient holds at least 25 % of the capital and to 15 % in other cases (Art. 10, Dz.U. 1994 No. 63 item 269). The Polish company applies the treaty rate only on the basis of the recipient's certificate of tax residence (Art. 26(1) of the CIT Act for corporate recipients). The owner's Ukrainian taxes and CFC report are handled by crystal.tax.
Registration, address and residence: other group companies
Company formation, the registered address and corporate changes are arranged by Innova Consulting Group companies; an overview of formation and taxes is on the company registration in Poland page. Registering a company does not by itself give a right to live in Poland: a residence permit for running a business is issued by the voivode under separate requirements on the company's income or employees. Immigration matters are handled by legal.ua: business residence permit in Poland. An overview of entering the Polish market is on innovacg.com. Key Solutions joins once the company exists or is being formed and is responsible for its accounting and reporting.
What we need from you
- company name and KRS number, or the planned registration date;
- the latest financial statements, CIT-8 and JPK_V7 if the company is already trading;
- bank statements and a list of main counterparties;
- number of employees and the types of their contracts;
- contacts of the previous accountant for the handover;
- the shareholders and their tax residence for the CFC pack.
We accept documents electronically. We do not need bank passwords.
Result
- the books of the sp. z o.o. closed every month, ZUS, CIT advances and JPK_V7 filed on time;
- annual financial statements prepared, approved and filed with the KRS, CIT-8 filed by 31 March;
- an audit report where the company falls under a statutory audit;
- an up-to-date CRBR entry;
- a management report and CFC pack for the owner;
- a deadline calendar for the next year.
Legal basis
Polish laws behind this work (versions in force on 09.10.2026)
- Accounting Act (ustawa o rachunkowości), Dz.U. 2026 item 522 — Art. 9 (language and currency of books), Art. 10 (accounting policy), Arts. 52–53 (preparation and approval), Art. 64 (statutory audit), Art. 69 (KRS filing);
- Corporate Income Tax Act, Dz.U. 2026 item 554 — Art. 19 (rates), Art. 25 (advances), Art. 26 (withholding tax, residence certificate), Art. 27 (CIT-8);
- VAT Act, Dz.U. 2026 item 1263 — Art. 96 (registration), Art. 99 (deadlines), Art. 113 (PLN 240,000 exemption), Art. 146ef (23 % rate);
- Act of 5 August 2025, Dz.U. 2025 item 1203 — mandatory KSeF from 1 February 2026 and transition rules;
- Personal Income Tax Act, Dz.U. 2026 item 592 — Art. 38 (remitting PIT advances on salaries);
- Ukraine–Poland double tax convention, 1993 — Arts. 10–12;
- Tax Code of Ukraine — sub-paras. 39-2.1.2 and 39-2.5.2: controlling person and CFC report.
Why Key Solutions
- Company
- ТОВ «АУДИТОРСЬКА ФІРМА «КЕЙ СОЛЮШНЗ», a Ukrainian limited liability company, EDRPOU code 39610085, registered on 30.01.2015.
- Roles
- Polish books and filings: a Polish accountant; statutory audit: a Polish audit firm; CRBR: a board member of the company; coordination, control and owner reporting: Key Solutions.
- Group
- We are part of Innova Consulting Group: Polish taxes and the owner's CFC matters — crystal.tax, legal and immigration matters — legal.ua.
- Contract
- Scope, timing, liability and confidentiality are set out in a contract before work starts.
FAQ
Can a Polish sp. z o.o. be accounted for from Ukraine?
A Polish company keeps its books in Polish and in zloty (Art. 9 of the Accounting Act), and JPK_V7, CIT-8 and ZUS documents are filed electronically with Polish authorities. The books and filings are therefore handled by a Polish accountant or accounting office. Key Solutions sets the tasks, controls deadlines and figures, and prepares owner reporting.
When must an sp. z o.o. register for VAT?
The VAT-R registration is filed before the first taxable transaction (Art. 96(1), VAT Act). The small-business exemption applies while net sales in the previous and current year do not exceed PLN 240,000 (Art. 113(1) from 1 January 2026) and does not cover the activities listed in Art. 113(13). A monthly filer submits JPK_V7M by the 25th of the following month.
Does my sp. z o.o. need a statutory audit?
Yes, if in the previous year the company met at least two of three conditions: average employment of at least 50, total assets of at least EUR 3,125,000 at year end, or net sales of at least EUR 6,250,000 (Art. 64(1)(4), Accounting Act). The audit is performed by a Polish audit firm and signed by a biegły rewident.
What are the deadlines for annual accounts and CIT-8?
Financial statements are prepared within 3 months of the balance sheet date, approved by the shareholders within 6 months and filed with the KRS within 15 days of approval (Arts. 52, 53, 69, Accounting Act). CIT-8 is filed electronically by the end of the third month after the tax year, i.e. 31 March for a calendar year, regardless of the approval date (Art. 27(1), CIT Act).
Who files the CRBR notice?
A person authorised to represent the company, usually a board member. It cannot be filed under a power of attorney, including by the accountant. The deadline is 14 days from the KRS entry and 14 days from any change of beneficial owners; the penalty is up to PLN 1,000,000. We prepare the data and track the deadline.
Is KSeF mandatory for my company?
From 1 April 2026 the obligation to issue structured e-invoices through KSeF covers all taxpayers, subject to a transition rule: until 31 December 2026 invoices outside KSeF are allowed where sales documented by them do not exceed PLN 10,000 in a month (Art. 145m, VAT Act as amended by Dz.U. 2025 item 1203). We set up KSeF access during the handover.
How do we switch from our current accountant?
We collect the books, trial balance and polityka rachunkowości, the latest financial statements with the KRS filing confirmation, CIT-8 and JPK_V7 with UPO receipts, ZUS documents and KSeF access from the previous accountant. Discrepancies are recorded in a memo with a correction plan, and then the monthly cycle starts.
Does a Polish sp. z o.o. give the owner a right to live in Poland?
Not automatically: company registration and residence permits are separate procedures. A residence permit for running a business is issued by the voivode where the company meets requirements on income or number of employees. Immigration matters are handled by legal.ua, and Key Solutions is responsible for the company's accounting and reporting.
How much does accounting for a Polish sp. z o.o. cost?
We prepare a tailored proposal after a short description of the company. The scope depends on the number of transactions and accounts, VAT status, headcount, CIT regime, audit duty, the state of prior years' books, and whether CFC or consolidation reporting is needed.
Related services
Request a tailored proposal for your sp. z o.o. accounting
Tell us whether the company is registered, whether it is VAT-registered, how many transactions and employees it has per month, and who keeps the books now. We will reply with the scope of work, the split of roles and how we would start.
Request a tailored proposal Telegram WhatsApp