

Accounting and reporting for a UAE company owned from Ukraine rests on three obligations to the federal authorities: Corporate Tax, VAT and record keeping. Every company, including a free zone company, registers for Corporate Tax and files a return within 9 months after the end of its tax period. The rate is 0% on taxable income up to AED 375,000 and 9% on the part above it. A Qualifying Free Zone Person pays 0% only on its qualifying income and 9% on other taxable income, without the AED 375,000 band, and must have audited financial statements. VAT is 5%; registration is mandatory once taxable supplies exceed AED 375,000 over 12 months, and returns are filed within 28 days after each tax period. Economic substance reporting (ESR) was cancelled for financial years ending after 31.12.2022. Key Solutions coordinates this work: a UAE partner accountant keeps the books and files the returns in the Federal Tax Authority (FTA) system, and we set the tasks, check deadlines and figures and prepare owner reporting.
Request a tailored proposal Telegram
In short
- For: owners from Ukraine with a mainland or free zone company in Dubai, Abu Dhabi, Ras Al Khaimah or another emirate, and groups where the UAE company trades, holds IP or invoices clients on behalf of a Ukrainian business.
- What we do: confirm the company's Corporate Tax position (standard regime, Qualifying Free Zone Person, Small Business Relief), set up the FTA and free zone calendar, take over the books, keep VAT under control, prepare the year-end close, the audit file and the Corporate Tax return figures, and give the owner clear reporting.
- Who files: a UAE partner accountant prepares and files the Corporate Tax and VAT returns; an independent audit firm licensed in the UAE audits the statements where an audit is required; an authorized signatory of the company approves the filings.
- Cost: a tailored proposal after a short description of the company, with no public price list.
- To start: send the company name, emirate and licensing authority (mainland or which free zone), financial year end, Corporate Tax and VAT registration numbers if any, revenue range and who keeps the books today.
First: which Corporate Tax regime applies
The UAE Corporate Tax Law (Federal Decree-Law No. 47 of 2022) applies to financial years beginning on or after 1 June 2023 (Ministry of Finance: Corporate Tax). The amount of tax and the audit requirement depend on the regime the company falls into, so this is settled before the first return.
| Regime | Rate | What it means for the books |
|---|---|---|
| Standard: mainland company or free zone company that does not qualify | 0% on taxable income up to AED 375,000, 9% on the part above | Full accrual accounts; audit required when revenue exceeds AED 50 million |
| Qualifying Free Zone Person (QFZP) | 0% on qualifying income, 9% on all other taxable income; the AED 375,000 band does not apply | Audited financial statements every year whatever the revenue; qualifying and non-qualifying revenue tracked separately |
| Small Business Relief (resident company, revenue up to AED 3 million) | Treated as having no taxable income for the period, if elected in the return | Return still filed; cash-basis accounts allowed; unavailable to a QFZP |
Rates per Cabinet Decision No. 116 of 2022 and the FTA Free Zone Persons guide; Small Business Relief per the Ministry of Finance, 07.08.2026. Checked 10.2026.
What a UAE company files and when
The table covers federal obligations as of 10.2026. A free zone or mainland licensing authority adds its own conditions for licence renewal, and they are checked separately for each company.
| What to file or do | When | Where and source |
|---|---|---|
| Corporate Tax registration | Required for every company, free zone companies included, even if all income is taxed at 0% | FTA, EmaraTax; mof.gov.ae |
| Corporate Tax return and payment | Within 9 months after the end of the tax period (the financial year); for a year ending 31 December, by 30 September | FTA; FTA Corporate Tax General Guide |
| Audited financial statements | For tax periods from 1 January 2025: a QFZP always; any other taxable person with revenue above AED 50,000,000 | Ministerial Decision No. 84 of 2025 |
| VAT registration | Within 30 days once taxable supplies and imports exceed AED 375,000 over the past 12 months or are expected to within the next 30 days; voluntary from AED 187,500 | FTA; tax.gov.ae: VAT registration |
| VAT return and payment | Within 28 days after the end of each tax period | FTA; tax.gov.ae: filing VAT returns |
| Electronic invoicing | Revenue of AED 50 million or more: service provider appointed by 30.10.2026, mandatory from 1.01.2027. Below AED 50 million: provider by 31.03.2027, mandatory from 1.07.2027 | Ministry of Finance; amendment of 10.05.2026 |
| Economic substance (ESR) notification and report | Cancelled for financial years ending after 31.12.2022; earlier years and FTA requests still apply | Cabinet Decision No. 98 of 2024 |
| Records | Kept for 7 years after the end of the tax period they relate to | FTA Free Zone Persons guide, section 12.1 |
A return due date falling on a weekend or public holiday moves to the next business day. The figures above are rules of law; Key Solutions does not set them.
Free zone company: what 0% really covers
A free zone licence alone gives no 0% rate. A free zone company becomes a Qualifying Free Zone Person only when it meets all the conditions at once: adequate substance in the free zone, qualifying income, transfer pricing compliance, audited financial statements, no election for the standard regime, and the de minimis test. Under that test, non-qualifying revenue in the tax period must not exceed the lower of AED 5,000,000 and 5% of total revenue (FTA guide CTGFZP1, sections 3.2–3.3).
- A QFZP pays 0% on qualifying income and 9% on taxable income that is not qualifying, from the first dirham: the 0% band up to AED 375,000 is unavailable to it.
- Qualifying income is limited mainly to transactions with other free zone persons and to qualifying activities. Revenue from mainland customers for non-qualifying activities counts toward the de minimis limit.
- A company that fails a condition loses QFZP status for that tax period and the following four and is taxed at the standard rates.
- Free zone and mainland licensing authorities set their own rules on accounts and audit for licence renewal, so the audit report often serves two purposes: the Corporate Tax return and the licence.
We therefore split revenue in the books by customer type and activity from the first month. The de minimis test and the qualifying share are then visible during the year, before the auditor sees the figures.
VAT 5%
The standard VAT rate in the UAE is 5% (Ministry of Finance: VAT). A resident company registers within 30 days once taxable supplies and imports exceed AED 375,000 over the previous 12 months or are expected to exceed it in the next 30 days; voluntary registration is possible from AED 187,500, including for start-ups with taxable expenses and no turnover yet. A business without a place of residence in the UAE that makes taxable supplies there registers regardless of the threshold, unless another person in the UAE accounts for the VAT. The return and payment are due within 28 days after the end of the tax period, and the FTA sets the period for each registrant (tax.gov.ae).
For a company invoicing clients outside the UAE, the main questions are the place of supply and the zero rate for exported services, which the partner accountant confirms against the contracts before the first return.
Audit and financial statements
Ministerial Decision No. 84 of 2025, in force for tax periods starting on or after 1 January 2025, requires audited financial statements from two groups: any taxable person (outside a tax group) with revenue above AED 50,000,000 in the period, and every Qualifying Free Zone Person whatever its revenue (MD No. 84 of 2025, Art. 2). For earlier periods the same rule came from Ministerial Decision No. 82 of 2023. A company outside these groups may still need an audit for its free zone, bank or investors.
The audit is carried out by an independent audit firm licensed in the UAE. Key Solutions prepares the audit file: trial balance, reconciliations, related-party schedules and the revenue split for the QFZP test.
Small Business Relief and electronic invoicing
A resident company with revenue of up to AED 3 million in the current and every previous tax period can elect Small Business Relief and is treated as having no taxable income for the period. In August 2026 the Ministry of Finance extended the relief to tax periods ending on or before 31 December 2029 (Ministerial Decision No. 131 of 2026). The election is made in the Corporate Tax return, so the return is still filed. The relief is unavailable to a Qualifying Free Zone Person and to members of large multinational groups.
Electronic invoicing is being introduced through accredited service providers: a pilot started on 1 July 2026, companies with revenue of AED 50 million or more move to mandatory e-invoicing on 1 January 2027, and other businesses on 1 July 2027. For most owners from Ukraine this means choosing an accounting system and provider during 2026–2027 so that invoices are issued in the required format from the start date.
Taking over from the previous agent
We start with a check: licence and licensing authority, Corporate Tax and VAT registrations in EmaraTax, filed returns, audit reports for earlier years, bank statements and money flows with the owner and related companies. If registration or returns were missed, the partner accountant prepares the corrections, and the owner receives a risk assessment before anything is filed. Differences are recorded in a handover report.
What the service includes
- diagnostic: licence, Corporate Tax regime, QFZP conditions, VAT status, filing history;
- selecting and setting up the UAE partner accountant: scope, document flow, access to EmaraTax;
- bookkeeping on an accrual basis with revenue split by customer type and activity;
- VAT returns and VAT records, place-of-supply review for foreign clients;
- year-end close, audit file and liaison with the audit firm;
- Corporate Tax return figures, including the QFZP de minimis test and transfer pricing schedules;
- preparation for electronic invoicing with the chosen provider;
- management reporting for the owner: profit, cash flow, taxes due;
- a financial statements pack for the Ukrainian owner's CFC report, consolidation with a Ukrainian company on request.
How we work
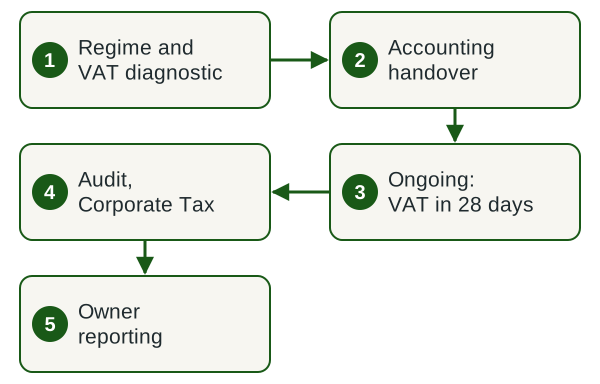
- Diagnostic. We confirm the licence, the Corporate Tax regime and VAT status and check past filings.
- Handover. We take over the books from the previous agent and record differences.
- Ongoing cycle. Documents, bank reconciliation, VAT returns every period.
- Annual cycle. Year-end close, audit where required, Corporate Tax return within 9 months.
- Owner reporting. Management report, CFC and consolidation pack.
Reporting for the owner in Ukraine
For an owner who is a Ukrainian tax resident, a UAE company is usually a controlled foreign company: a stake above 50%, or above 10% where Ukrainian residents together hold 50% or more (Tax Code of Ukraine, sub-para. 39-2.1.2). Certified copies of the company's financial statements are attached to the CFC report (sub-para. 39-2.5.2), so the UAE books are kept to produce full year-end statements, audited where the law or the free zone requires it. We prepare the CFC pack together with reporting for foreign companies. The group's UAE market entry overview is at innovacg.com.
Registration and visas: other group companies
Forming a mainland or free zone company is handled by regserv.biz: company registration in the UAE. A UAE company gives its owner no residence status by itself; residence visas are a separate procedure handled by legal.ua. Key Solutions steps in once the company exists or is being formed and is responsible for accounting and reporting.
What we need from you
- trade licence, certificate of incorporation and memorandum of association, licensing authority;
- Corporate Tax and VAT registration certificates (TRN), if already issued;
- Corporate Tax and VAT returns filed so far, audit reports for earlier years;
- bank statements and payment platform statements;
- contracts with main customers and suppliers, showing where they are located;
- a list of transactions with the owner and the owner's other companies: contributions, loans, payments, services;
- employees and office lease details, which matter for substance;
- the owners' tax residence and the share structure for the CFC pack.
Documents are exchanged electronically. We do not need bank passwords.
Result
- the company's Corporate Tax regime is confirmed and documented;
- Corporate Tax return filed and tax paid within 9 months of year end;
- VAT returns filed within 28 days after each period where the company is registered;
- audited financial statements where the law or the free zone requires them;
- revenue split ready for the QFZP de minimis test;
- management report and CFC pack for the owner;
- an FTA, auditor and licence deadline calendar for the next year.
Legal basis and sources
Official sources behind this page (UAE Ministry of Finance and Federal Tax Authority, checked 10.2026)
- Ministry of Finance: Corporate Tax in the UAE — Federal Decree-Law No. 47 of 2022, registration, return within 9 months, 0% for free zone qualifying income;
- Cabinet Decision No. 116 of 2022 — AED 375,000 threshold;
- FTA guide: Free Zone Persons (CTGFZP1) — QFZP conditions, de minimis, records for 7 years;
- Ministerial Decision No. 84 of 2025 — audited financial statements;
- Small Business Relief extended to 2029 — Ministerial Decision No. 131 of 2026;
- FTA: VAT registration, FTA: filing VAT returns — thresholds and the 28-day deadline;
- Cabinet Decision No. 98 of 2024 — ESR reporting cancelled;
- Ministry of Finance: e-invoicing timeline — Ministerial Decisions No. 243 and 244 of 2025, No. 66 of 2026;
- Tax Code of Ukraine, sub-paras. 39-2.1.2 and 39-2.5.2: controlling person and CFC report.
Why Key Solutions
- Company
- KEY SOLUTIONS AUDIT FIRM LLC, Ukrainian company code 39610085, registered since 30.01.2015.
- Roles
- UAE books, VAT and Corporate Tax returns are prepared and filed by a UAE partner accountant; the audit is carried out by an independent audit firm licensed in the UAE; an authorized signatory of the company approves the filings; coordination, control and owner reporting are done by Key Solutions.
- Group
- We are part of Innova Consulting Group: company formation by regserv.biz, market entry by innovacg.com.
- Contract
- Scope, liability and confidentiality are set in a contract before work starts.
Frequently asked questions
Does a UAE free zone company pay 0% Corporate Tax?
Only on qualifying income and only if it meets every Qualifying Free Zone Person condition: adequate substance, qualifying income, transfer pricing compliance, audited financial statements and the de minimis test. Other taxable income is taxed at 9% from the first dirham, because the AED 375,000 band at 0% does not apply to a QFZP.
What is the de minimis test for a free zone company?
Non-qualifying revenue in the tax period must not exceed the lower of AED 5,000,000 and 5% of total revenue. A company that fails it loses Qualifying Free Zone Person status for that period and the following four and is taxed at the standard rates.
When is the UAE Corporate Tax return due?
Within 9 months after the end of the tax period, which is normally the financial year. For a year ending 31 December the return and payment are due by 30 September of the following year. The return is filed in the FTA's EmaraTax system.
Does a UAE company need an audit?
For tax periods starting from 1 January 2025, Ministerial Decision No. 84 of 2025 requires audited financial statements from every Qualifying Free Zone Person and from any other taxable person with revenue above AED 50 million. Free zone authorities, banks and investors may require an audit in other cases too.
When must a UAE company register for VAT?
Within 30 days once taxable supplies and imports exceed AED 375,000 over the past 12 months or are expected to within the next 30 days. Voluntary registration is possible from AED 187,500. The rate is 5%, and returns are due within 28 days after each tax period.
Does a UAE company still file an economic substance (ESR) report?
Cabinet Decision No. 98 of 2024 cancelled ESR notifications and reports for financial years ending after 31 December 2022. Obligations for earlier years, FTA information requests and penalties already imposed remain.
What is Small Business Relief and who can use it?
A resident company with revenue of up to AED 3 million in the current and all previous tax periods can elect to be treated as having no taxable income. The relief now covers tax periods ending on or before 31 December 2029. A Corporate Tax return is still filed, and a Qualifying Free Zone Person cannot use the relief.
Who keeps the books and files returns for a UAE company?
A UAE partner accountant keeps the books and files the VAT and Corporate Tax returns in EmaraTax; an independent audit firm licensed in the UAE carries out the audit where it is required. Key Solutions coordinates the work, checks deadlines and figures and prepares owner and CFC reporting.
Related services
Request a tailored proposal for your UAE company's accounting
Send the emirate and licensing authority, financial year end, Corporate Tax and VAT registration status, revenue range, whether the company had an audit and who keeps the books today. We will reply with the scope, the split of roles and how to start.
Request a tailored proposal Telegram WhatsApp