


IFRS conversion of financial statements is the restatement of accounts prepared under Ukrainian national accounting standards (НП(С)БО, often called Ukrainian GAAP) into IFRS through adjustments and reclassifications. Locally it is often called IFRS transformation. Key Solutions sets the IFRS accounting policy, makes the adjustments and prepares full IFRS statements with notes.
+38 (068) 777-14-74 Telegram WhatsApp
In short
- When you need it: the company is on the list in part 2 of Art. 12-1 of the Law on Accounting and Financial Reporting (Law No. 996-XIV), or a bank, investor or parent group asks for IFRS statements.
- What you get: IFRS financial statements with notes and a conversion worksheet with the calculation behind every adjustment.
- Timing: we set it after a diagnostic and fix it in the contract; it depends on the number of entities and periods and on the state of the books.
- Cost: depends on transaction volume, the number of legal entities and whether this is first-time adoption or a repeat conversion.
- Where to start: send the trial balance and financial statements for the last year, and we will reply with the format, timing and price.
When a Ukrainian company needs IFRS financial statements
A company needs IFRS statements when the law requires them or when a user of the statements asks for them: a bank, an investor, a foreign owner or a buyer. Other companies decide for themselves whether to apply IFRS (part 3 of Art. 12-1 of Law No. 996-XIV).
- Legal duty (part 2 of Art. 12-1 of Law No. 996-XIV): among others, large enterprises, banks, insurers, public joint-stock companies, issuers whose securities are admitted to trading on a regulated market, extractive companies, parent companies of large groups and financial companies listed in para. 2 of the Procedure for Submitting Financial Statements (Procedure No. 419). See also financial statements under IFRS.
- A loan from a bank or an international financial institution.
- Consolidation into a foreign group, the sale of a stake or a new investor.
Conversion or parallel accounting: which to choose
Conversion restates finished Ukrainian GAAP statements into IFRS at the reporting date, while parallel accounting records every transaction under both sets of rules at once. For most companies, conversion for the reporting period is enough.
| Format | When it fits | What we need from you |
|---|---|---|
| Annual or quarterly conversion | Statements for a bank, investor, parent group or the financial reporting centre | Trial balance, Ukrainian GAAP statements, contracts and breakdowns |
| Management reports under IFRS | The owner needs cash flow and results more often than once a year | Access to the accounting system and the month-end close schedule |
| Parallel accounting | IFRS data is needed daily and the group has many companies | A second chart of accounts and rules in the accounting system |
What IFRS conversion includes
- Review of Ukrainian GAAP accounts and statements and a list of differences from IFRS.
- An IFRS accounting policy: asset measurement, provisions, leases, revenue.
- Measurement of property, plant and equipment, receivables, inventories and provisions.
- Adjustments and reclassifications, including deferred tax.
- A conversion worksheet.
- Statements of financial position, comprehensive income, cash flows and changes in equity, with notes.
- Consolidation where the group has several companies.
How we work
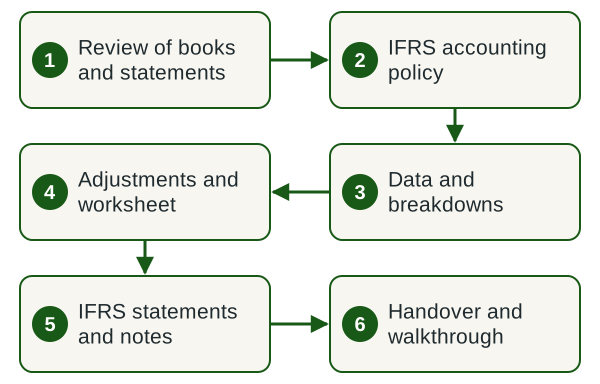
- Review of books and statements We study the trial balance and statements, assess differences from IFRS and set the scope.
- IFRS accounting policy We agree measurement methods and key judgements with you.
- Data and breakdowns We request contracts and breakdowns from a checklist.
- Adjustments and worksheet Every adjustment comes with a calculation and a reference to the standard.
- IFRS statements and notes We prepare the full set of statements and notes.
- Handover and walkthrough We explain the adjustments to you, your auditor, bank or group.
Timing and filing deadlines
We set the timing after the diagnostic and fix it in the contract. It depends on the number of entities and periods, how quickly breakdowns arrive and whether this is first-time adoption, which needs data as of the transition date.
IFRS statements are filed on the Ministry of Finance taxonomy in a single electronic format (part 5 of Art. 12-1 of Law No. 996-XIV). Annual statements are due at the financial reporting centre by the publication deadline of part 3 of Art. 14 of Law No. 996-XIV, 30 April or 1 June depending on the category; interim ones by the 30th of the month after the quarter (para. 5 of Procedure No. 419). Under martial law, companies without a state share above 50% may file within three months after it ends (subparas. 1 and 4-2, para. 1 of Law No. 2115-IX).
What drives the cost
- Number of legal entities and whether consolidation is needed.
- First-time adoption of IFRS or a repeat conversion under an approved policy.
- Number of items that need measurement: leases, loans, foreign currency, fixed assets.
- Quality of Ukrainian GAAP accounting and completeness of breakdowns.
- Number of reporting periods and comparatives.
- The deadline for the statements.
What we need from you
- Trial balance and Ukrainian GAAP statements for the reporting and previous periods.
- The accounting policy order.
- Lease, credit and loan agreements and foreign currency contracts.
- Breakdowns of receivables and payables, fixed assets and inventories.
- Inventory count results.
- A contact person in accounting and an agreed response time for queries.
What you receive
- A full set of IFRS financial statements with notes.
- The conversion worksheet and working files with calculations.
- An IFRS accounting policy.
- A list of adjustments with explanations for your auditor, bank or parent company.
- Recommendations on accounting for the next conversion.
Get a quote for IFRS conversion
Send the trial balance and statements for the last year and tell us who the IFRS statements are for. We will reply with the format, timing and price.
Typical adjustments on transition to IFRS
Most adjustments come from items that Ukrainian GAAP and IFRS measure or recognise differently.
- IFRS 16 Leases: the lessee recognises a right-of-use asset and a lease liability.
- IFRS 9 Financial Instruments: an expected credit loss allowance on receivables.
- IAS 16 Property, Plant and Equipment and IAS 36 Impairment of Assets: useful lives and impairment.
- IAS 12 Income Taxes: deferred tax assets and liabilities arising from all adjustments.
- IFRS 15 Revenue from Contracts with Customers: timing of revenue under complex contracts.
- IAS 21 The Effects of Changes in Foreign Exchange Rates: foreign currency items and functional currency.
First-time adoption of IFRS
First-time adoption is the first set of statements under international standards, prepared under IFRS 1 First-time Adoption of International Financial Reporting Standards. The balance sheet in the first annual IFRS statements shows figures at the start and end of the reporting period and at the transition date (para. 11, section II of National Accounting Standard (НП(С)БО) 1).
An inventory count is taken at the transition date (para. 12 of Procedure No. 419), and the statistics authority is notified by letter (para. 11). Companies required to apply IFRS then keep their books under the IFRS policy (part 6 of Art. 12-1 of Law No. 996-XIV).
Legal framework
Rules the work relies on
- parts 2–6 of Art. 12-1 of Law No. 996-XIV — who must apply IFRS, who may choose to, taxonomy, accounting after the first statements.
- part 3 of Art. 14 of Law No. 996-XIV — publication deadlines for annual financial statements.
- paras 2, 5, 11, 12 of Procedure No. 419 — activities, filing deadlines, letter to the statistics authority, inventory count.
- para. 11, section II of National Accounting Standard 1 — balance sheet of the first IFRS statements at the transition date.
- subparas. 1, 4-2, para. 1 of Law No. 2115-IX — filing and publication under martial law.
Risks and why to hand conversion to a team under contract
An error in the adjustments carries into comparatives for later years: a bank may return the statements with a loan application, an auditor may modify the opinion, and a parent company may send the package back. A team under contract answers for the result in writing, and every adjustment has a calculation the auditor can follow. A worksheet template or a chatbot answer knows nothing about your contracts, so such statements end up being redone. Legal questions on transactions and group structure are handled together with legal.ua.
Why Key Solutions
- Company
- LLC Audit Firm Key Solutions (ТОВ «АУДИТОРСЬКА ФІРМА «КЕЙ СОЛЮШНЗ»), EDRPOU code 39610085. The company's details are public in the Unified State Register (ЄДР).
- Contract
- We work under a contract: scope, timing and liability are agreed before work starts. Client information is protected by professional confidentiality (Art. 11 of Law No. 2258-VIII).
- Group
- We are part of Innova Consulting Group: legal matters are handled by legal.ua, crypto-asset taxation by crystal.tax.
- Office
- Our office is at 77 Velyka Vasylkivska St, Kyiv. We serve clients across Ukraine remotely. The specialists who run projects are listed on the Our employees page.
Frequently asked questions
What is IFRS conversion of financial statements?
IFRS conversion is the preparation of IFRS financial statements from accounting data kept under Ukrainian national accounting standards (Ukrainian GAAP). The accounting team closes the period as usual, and adjustments in a conversion worksheet bring the statements into IFRS format.
Do we need IFRS conversion if IFRS is optional for our company?
Yes, if a bank, investor or parent group asks for IFRS statements: such companies adopt IFRS by their own decision (part 3 of Art. 12-1 of Law No. 996-XIV). The duty to apply IFRS comes from part 2 of the same Article and covers large enterprises, banks, insurers and public joint-stock companies, among others.
How much does IFRS conversion cost?
The price depends on the number of companies, transaction volume, first-time or repeat adoption and the quality of the books. After reviewing the trial balance and the statements, we quote a fee and timing, and both are fixed in the contract.
How do we prepare for the transition to IFRS?
Preparation starts with choosing the transition date and the accounting policy, because they determine which data from earlier periods you will need. The inventory count and balance sheet requirements are set out in the section on first-time adoption. We draw up a transition plan and a document list for your accounting team.
Who audits the financial statements after conversion?
An independent auditor audits IFRS statements under International Standards on Auditing (ISA) when the law, a bank or an investor requires it (Art. 10 of Law No. 2258-VIII). We prepare the worksheet and calculations so that the auditor can trace each adjustment to source data, and we answer the auditor's questions on adjustments.
Can you prepare IFRS statements for a foreign parent company?
Yes. Consolidation into a foreign group is one of the usual reasons for conversion. We prepare IFRS statements with notes and a conversion worksheet and give the parent company and its auditor a list of adjustments with explanations. The format, period and deadline are fixed in the contract.
What will IFRS 18 change from 2027?
IFRS 18 Presentation and Disclosure in Financial Statements applies to annual periods beginning on or after 1 January 2027. It classifies income and expenses in the statement of profit or loss into categories, mainly operating, investing and financing, and adds new subtotals. Recognition and measurement rules stay the same.
Related services
Discuss your IFRS conversion
Tell us who needs the IFRS statements (a bank, investor, parent group or the financial reporting centre), for which period and how many companies are in scope, and attach the trial balance if it is ready. We will reply with the format, timing and price.
Book a consultation Order the service +38 (068) 777-14-74 Telegram WhatsApp