Unblocking a tax invoice means lifting the suspension of its registration in Ukraine's Unified Register of Tax Invoices (ЄРПН) by filing explanations and documents with a commission of the State Tax Service of Ukraine (ДПС, STS), or by appealing a refusal. Key Solutions analyses the STS receipt, builds the evidence package around the suspension criterion and supports the review.
+38 (068) 777-14-74 Telegram WhatsApp
In short
- When you need it: you have received an STS receipt suspending registration of a tax invoice or adjustment calculation (ПН/РК), a refusal to register, a decision that your company meets the risk criteria, or a decision rejecting your VAT payer data table.
- What you get: written explanations and copies of documents matched to the criterion in the receipt and, after a refusal, a complaint to the central-level STS commission.
- Timing: the regional commission reviews explanations within 5 working days under para. 9 of the Procedure approved by Ministry of Finance Order No. 520 (Порядок № 520). Our preparation time depends on the number of invoices and the state of primary documents, and we fix it in the contract.
- Cost: depends on the number of invoices and counterparties, the suspension ground, the condition of your documents and the stage of the procedure. We quote after reviewing the receipt.
- How to start: book a consultation and attach the suspension receipt or the commission's decision, plus the contract with the buyer.
Tax invoice unblocking services: what we prepare at each stage
The service covers the whole procedure, from the first suspension receipt to a complaint against a refusal. What we prepare depends on the document you have received from the STS.
| STS document | What we prepare | Rule |
|---|---|---|
| Suspension receipt | Written explanations and copies of documents for the regional commission | paras 4–6, Procedure No. 520 |
| Request for additional explanations | The documents and explanations the commission is missing | para. 9, Procedure No. 520 |
| Refusal to register | Complaint to the central-level STS commission | Tax Code, para. 56.23 |
| Decision on payer riskiness | Information and documents showing the company falls outside the criteria | para. 6, Resolution No. 1165 |
| Suspension by product code | VAT payer data table with an explanation | paras 12–14, Resolution No. 1165 |
Resolution No. 1165 provides for automatic registration in two cases. Once the STS accepts your data table, invoices suspended under para. 1 of Annex 3 are registered automatically on the fifth working day (para. 16-1). Once it decides that the company no longer meets the risk criteria, registration follows on the next working day (para. 6-1). Both routes also require additional conditions, including the Pmax (Рмакс) indicator and the VAT amount the payer is entitled to register.
Why the STS suspends invoice registration
The grounds are set by the Cabinet of Ministers: para. 201.16 of the Tax Code of Ukraine (ПКУ) delegates both the procedure and the grounds to it. The exhaustive list sits in the Procedure approved by Cabinet of Ministers Resolution No. 1165 of 11.12.2019 (постанова КМУ № 1165), as amended by Resolution No. 1048 of 26.08.2025. The receipt itself states the reason (Tax Code, para. 201.10).
- Payer risk criteria (Annex 1): registration on invalid documents, no open bank accounts, no VAT returns for the last two periods, tax information held by the STS on risky transactions, and others.
- Transaction risk criteria (Annex 3): for example, supplies under a product code of the Ukrainian classification of goods for foreign trade (УКТ ЗЕД) exceed the balance calculated from purchases or imports of that code since 1 January 2017, multiplied by 1.5, when the code is missing from an accepted data table (para. 1 of Annex 3).
- Positive tax history (Annex 2): invoices of a payer meeting at least one of these indicators are exempt from suspension on transaction risk criteria (para. 7).
Typical triggers are a sale with no matching purchase of similar goods, a product range that differs from registered purchases, sales far above the company's resources, or missing evidence of staff, fixed assets, warehouses or transport. If the cause lies in the company's status, we work in parallel on removal from the risky VAT payer list.
What the service includes
- Analysis of the receipt: the risk criterion with its calculated indicator (para. 11, Resolution No. 1165) and the УКТ ЗЕД product code or the service code of the State Classifier of Products and Services (ДКПП), where stated.
- Review of primary documents against the mandatory details in Art. 9 of the Law of Ukraine «On Accounting and Financial Reporting in Ukraine» No. 996-XIV (Закон № 996-XIV), and reconciliation of product codes in incoming and outgoing invoices.
- Written explanations for the regional commission that tie each document to the transaction in the invoice.
- A set of document copies under the list in para. 5 of Procedure No. 520, formatted for electronic filing.
- A response to the commission's request for additional explanations.
- A complaint to the central-level commission and preparation for the video-conference hearing.
- A VAT payer data table and a riskiness package if suspensions recur.
How we work
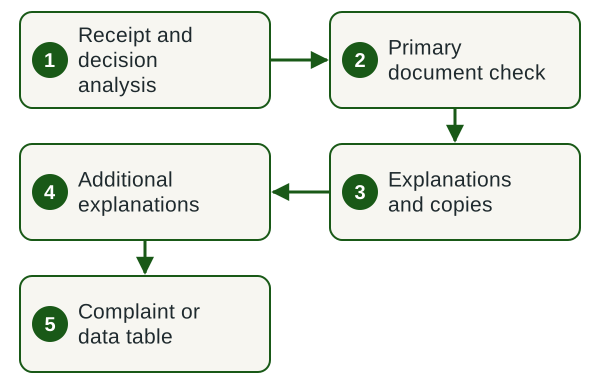
- Receipt and decision analysis. We identify the suspension criterion, the product code and the document that needs to be rebutted.
- Primary document check. We reconcile details, codes and the purchase-to-sale chain of the goods.
- Explanations and copies. We prepare the package for the regional commission and pass it to you for signature.
- Additional explanations. If the commission sends a request, we supply the documents it is missing.
- Complaint or data table. After a refusal we draft a complaint to the central STS; for recurring suspensions, a data table or a riskiness package.
Timelines
Review periods are set by law. Our preparation time depends on the number of invoices, the completeness of primary documents and how quickly counterparties respond; we name it after reviewing the documents and fix it in the contract.
- Explanations and copies can be filed within 365 calendar days following the date the invoice was drawn up (para. 6, Procedure No. 520).
- For additional explanations the payer has 5 working days from the day after receiving the request, and the commission decides within the next 5 working days (para. 9, Procedure No. 520).
- The commission reviews a VAT payer data table within five working days (para. 15, Resolution No. 1165).
- Documents on payer riskiness are reviewed within seven working days; if no decision is taken in that time, the payer is removed from the risky list (para. 6, Resolution No. 1165).
What affects the cost of unblocking tax invoices
The cost depends on the number of invoices, the suspension ground, the state of primary documents and the stage of the procedure. We quote after reviewing the receipt and the contract, and fix the price in the contract together with the scope.
| Factor | Effect on scope | What to prepare |
|---|---|---|
| Number of invoices | Invoices to one buyer under one contract, or with the same codes, go into one package (para. 6, Procedure No. 520) | List of blocked invoices |
| Suspension ground | Transaction risk, payer riskiness and data tables need different evidence | Receipt, commission decision |
| State of primary documents | Missing documents or details are restored first | Contracts, delivery notes, acts, waybills |
| Procedure stage | Explanations, additional explanations or a complaint to the central STS | All requests and decisions of the commission |
| Origin of goods | Import, production or resale defines the chain of evidence | Customs declarations, production records |
What we need from you
- The suspension receipt, the commission's request or its decision.
- The contract with the buyer, with annexes and specifications.
- Primary documents along the purchase and sale chain: delivery notes, acts, waybills, import customs declarations.
- Bank statements for the transaction.
- Evidence of resources: warehouse lease, transport, staff, fixed assets.
- A contact person in accounting who answers questions quickly.
What you receive
- Written explanations describing the transaction, with a list of attached documents tied to the invoice.
- A set of document copies ready for filing through the taxpayer's electronic account.
- A draft complaint to the central-level commission if registration is refused.
- A VAT payer data table with an explanation if suspensions recur on product codes.
- A list of actions that lower the risk of new suspensions: УКТ ЗЕД codes, primary documents, data table.
Find out the cost of unblocking
Send the suspension receipt or the commission's decision and describe the transaction in a few lines. We will reply with the scope, timing and cost.
Appealing a refusal to register
A refusal can be appealed administratively or in court (Tax Code, para. 56.1). The complaint goes to the central executive body that implements state tax policy within 10 working days following the day of the decision (subpara. 56.23.1), and the whole exchange is electronic (subpara. 56.23.5).
- Without the payer's participation the complaint is reviewed within 10 calendar days after receipt; with participation by video conference, within 30 calendar days, and this period cannot be extended (subpara. 56.23.3).
- Under martial law the complaint is reviewed within 10 working days from its receipt by the central body (Tax Code, subpara. 69.9, para. 69, subsection 10, Section XX).
- If no reasoned decision arrives in time, the complaint is deemed fully upheld in the payer's favour from the next day (subpara. 56.23.4).
- During an administrative appeal, the burden of proving that the decision is lawful rests with the tax authority (para. 56.4).
A decision challenged in court can no longer be appealed administratively (para. 56.18), so the route is chosen once and on purpose. The court stage is handled by the group's lawyers at legal.ua. See also preparing a complaint to the tax authority and court appeals against blocked invoices.
Important. The seller still has to report the VAT shown in the invoice as its tax liability for the period (Tax Code, para. 201.10). While the invoice is blocked, both sides carry the cost: the seller has declared the tax, and the buyer has no deduction yet.
Legal basis
Rules the work relies on
- Tax Code of Ukraine, paras 201.10 and 201.16 — receipts, registration deadlines, suspension under the procedure set by the Cabinet of Ministers.
- Tax Code of Ukraine, para. 56.23 — appeals against a refusal to register a tax invoice.
- Tax Code of Ukraine, paras 120-1.1 and 198.6 — late registration penalties and the buyer's input VAT.
- Procedure approved by CMU Resolution No. 1165 of 11.12.2019 — risk criteria, VAT payer data table, STS commissions.
- Procedure approved by MoF Order No. 520 of 12.12.2019 — explanations, the list of documents, commission deadlines.
- Procedure for keeping the ЄРПН, CMU Resolution No. 1246 of 29.12.2010 — receipts, the operating day, the moment of registration.
- Art. 9 of Law No. 996-XIV — primary documents and their mandatory details.
Risks, and why to hand this to a team under contract
While an invoice is blocked, the buyer has no input VAT and the seller has already declared the tax, so money on both sides is frozen. A weak package ends in refusal, and the window for a complaint is short (subpara. 56.23.1). If a riskiness decision is in force, new invoices may be suspended again and again.
We work under a contract that fixes scope, timing and liability before the start, and we build the package around the criterion in your receipt. Court proceedings are run by the group's lawyers at legal.ua. Template explanations from forums or chatbots ignore your criterion and your product codes.
Why Key Solutions
- Turnkey, with no extra hassle
- We take the whole task: documents, calculations, reporting and correspondence with the State Tax Service. You make the decisions, provide source documents and sign; we do the rest and contact you only when it matters.
- We take on the tax office
- Information requests, blocked tax invoices, inspection reports: we prepare explanations, rework documents and appeal until the issue is closed. Where the law is in dispute, we work together with the group's lawyers.
- We see it through
- Your case stays on track: the specialist running it remains with you, even if an inspection or audit drags on for months. Statutory audits are performed, and the report signed, by a partner audit firm entitled to perform them; we handle preparation and support through publication, so you deal with one team from start to finish.
- Boutique-level involvement
- A senior specialist runs your project personally (see the Our employees page), backed by 14 years of Innova group practice in 50+ countries. Non-standard tasks are our field: where you hear “it can’t be done”, we look for a lawful way, and group companies cover the rest: legal.ua for legal matters, crystal.tax for crypto-asset taxation.
- Your affairs stay yours
- Information about your company, turnover, payroll and counterparties reaches neither competitors nor third parties. We disclose only what the law or a procedure requires, and the contract says so.
- Faster and right the first time
- Full involvement: your specialist learns your books, contracts and business, so documents and reports are ready on time with no rework. The group's 14 years of experience let us get right the first time what takes some firms three attempts.
Frequently asked questions
What should I do after receiving a suspension receipt?
Keep the receipt and use it to identify the suspension criterion and the product code. Then prepare explanations for the STS with copies of primary documents that prove the transaction is real and that the company has the resources to perform it. At the same time, check whether a decision on the company's riskiness is in force: while it stands, suspensions will keep recurring.
How long does the STS take to review unblocking documents?
The regional commission reviews explanations and copies of documents within 5 working days following receipt. In that time it registers the invoice, refuses registration or requests additional explanations (para. 9, Procedure No. 520). Our preparation time depends on the number of invoices and the state of primary documents, and we fix it in the contract.
How much does unblocking tax invoices cost?
The cost depends on the number of invoices and counterparties, the suspension criterion, the state of primary documents and the stage: explanations, additional explanations or a complaint. Explanations for several invoices to one buyer under one contract, or with the same product codes, can be filed as one package (para. 6, Procedure No. 520), which reduces the work. We quote after reviewing the receipt.
Which documents are needed to unblock a tax invoice?
Para. 5 of Procedure No. 520 lists them: contracts with annexes, powers of attorney, primary documents on supply, storage and transport, warehouse records, payment documents and bank statements, and quality documents where the contract or the law requires them. If the receipt names a product code, explanations cover only the transaction with that code. We select the set to match the criterion in the receipt.
Where is a complaint against a refusal to register filed?
The complaint goes to the central executive body that implements state tax policy within 10 working days following the day of the decision (Tax Code, subpara. 56.23.1). The complaint, its annexes and the decision on it are exchanged electronically (subpara. 56.23.5). We draft the complaint and prepare the annexes.
What happens if the STS misses the deadline for reviewing a complaint?
If the payer receives no reasoned decision within the period set by subpara. 56.23.3 of the Tax Code, the complaint is deemed fully upheld in the payer's favour from the day after that period ends (subpara. 56.23.4). The review period cannot be extended.
Can the buyer claim input VAT on a blocked invoice?
Only after the invoice is registered: VAT that is not confirmed by invoices registered in the ЄРПН is excluded from the tax credit (Tax Code, para. 198.6). The 365-day period for claiming it is interrupted while registration is suspended, so the buyer keeps the right after unblocking.
Is there a penalty for late registration while the invoice is blocked?
Penalties for missing the registration deadline do not apply for the period of suspension under para. 201.16 of the Tax Code, up to the decision on resuming registration (para. 120-1.1). The same rule applies to the penalty under para. 120-1.2.
Related services
Discuss your blocked invoice
In your request, give the invoice number and date, the criterion from the receipt and the date you received it. We will reply with the documents you need, the preparation time and the cost.
Book a consultation Order the service +38 (068) 777-14-74 Telegram WhatsApp