

Accounting and reporting for a US company owned from Ukraine means federal reporting to the IRS, reporting to the state of formation, and taxes in the states where the company does business. A single-member LLC with a foreign owner files Form 5472 with a pro forma Form 1120 every year by the 15th day of the 4th month after year end (April 15 for a calendar year), by fax or mail only, and the penalty for not filing is $25,000. A C corporation files Form 1120 by the same date and pays 21% federal tax. The state requires an annual report or annual tax: in Delaware corporations pay by March 1 and LLCs by June 1; in Wyoming the report is due on the first day of the month of formation. Since 14.08.2026 companies created in the United States are exempt from beneficial ownership (BOI) reporting to FinCEN. Key Solutions coordinates this work: a US partner accountant keeps the books and files the forms, and we set the tasks, check deadlines and figures and prepare owner reporting.
Request a tailored proposal Telegram
In short
- For: owners from Ukraine who have or plan an LLC or corporation in Delaware, Wyoming or another state, and groups where the US company sells services, software or goods on behalf of a Ukrainian business.
- What we do: confirm how the company is taxed (disregarded entity, partnership or corporation), set up the IRS and state calendar, take over the books from the previous agent, monitor payroll and sales tax, prepare the year-end close and the figures for Form 5472, 1120 or 1065, and give the owner clear reporting.
- Who files: a US partner accountant prepares and files the IRS forms and state reports; an authorized officer of the company signs the return; the registered agent or accountant files the state annual report.
- Cost: a tailored proposal after a short description of the company, with no public price list.
- To start: send the company name and state, entity type (LLC or corporation), number of owners, whether it has an EIN, US employees and US customers, and who keeps the books today.
First: how your company is taxed
US reporting depends on the company's tax classification, which is settled before the first entry is booked. A single-member LLC with a foreign owner is a disregarded entity by default: it pays no income tax at entity level, but the IRS requires information reporting on its transactions with the owner and related parties. An LLC with two or more members is taxed as a partnership by default and files Form 1065. A corporation, or an LLC that elected to be taxed as one, is a separate taxpayer and files Form 1120.
| Entity type | Federal form | What it means for the owner |
|---|---|---|
| Foreign-owned single-member LLC | Pro forma Form 1120 + Form 5472 | Information return on transactions with the owner and related parties; no income tax at LLC level |
| Multi-member LLC | Form 1065 and a Schedule K-1 for each member | Profit is allocated to members; separate withholding rules apply to foreign members |
| Corporation (C corp) | Form 1120; Form 5472 if a foreign shareholder owns 25% or more and there are related-party transactions | 21% federal tax at company level; dividends to a foreign owner are taxed at source |
What a US company files and when
Reporting runs through three channels: the IRS (federal tax and information returns), the state of formation (annual report or annual tax), and the states where the company sells or hires (sales tax, payroll, state tax). The deadlines below come from irs.gov, fincen.gov and state websites as of 10.2026, for a company with a calendar financial year.
| What to file or pay | When | Where and source |
|---|---|---|
| Form 5472 + pro forma Form 1120 (foreign-owned single-member LLC) | By the Form 1120 due date: the 15th day of the 4th month after year end, April 15 for a calendar year; extension with Form 7004 | IRS, fax or mail to Ogden only; IRS: Instructions for Form 5472 |
| Form 1120 (corporation) | 15th day of the 4th month after year end; for a year ending June 30, the 15th day of the 3rd month | IRS; IRS: Instructions for Form 1120 |
| Corporate estimated tax | 15th day of the 4th, 6th, 9th and 12th months, if expected tax is $500 or more | IRS, electronic payment only; Instructions for Form 1120 |
| Form 1065 and Schedules K-1 (multi-member LLC) | 15th day of the 3rd month after year end, March 15 for a calendar year | IRS; IRS: Instructions for Form 1065 |
| Forms 1042 and 1042-S | By March 15 of the following year, if the company paid US-source income such as dividends to foreign persons | IRS; IRS: Instructions for Form 1042 |
| Payroll: Form 941 | Quarterly: April 30, July 31, October 31, January 31 | IRS; IRS: employment tax due dates |
| Form 940, W-2, 1099-NEC | By January 31 for the previous year | IRS and SSA; IRS: employment tax due dates |
| Delaware corporation: annual report and franchise tax | On or before March 1 each year | Division of Corporations; corp.delaware.gov |
| Delaware LLC: annual tax | On or before June 1 each year; LLCs file no annual report | Division of Corporations; corp.delaware.gov |
| Wyoming: annual report and license tax | By the first day of the month in which the company was formed | Secretary of State; wyobiz.wyo.gov |
Form 7004 generally extends the time to file by 6 months; the time to pay stays the same, and tax is due by the original date (IRS: Instructions for Form 7004). A due date falling on a weekend moves to the next business day.
Form 5472 for a foreign-owned LLC
This is the key form for most Ukrainian owners of a US LLC. The disregarded entity files a pro forma Form 1120 with only the name, address and items B and E on page 1 completed, and attaches Form 5472 with details of the direct and ultimate foreign owner and of reportable transactions: capital contributions, loans, payments to the owner, services bought from related parties (IRS: Instructions for Form 5472, rev. 12/2024).
- These forms cannot be e-filed. The IRS accepts them by fax (300 DPI or higher) or by mail to its Ogden, Utah unit, with "Foreign-owned U.S. DE" written across the top of Form 1120. Form 7004 for an extension goes the same way.
- Each direct and ultimate foreign owner's foreign tax number (for Ukraine, the individual tax number RNOKPP) is entered, or "None" if there is none.
- Failing to file, filing late or filing a substantially incomplete form carries a $25,000 penalty; if the failure continues more than 90 days after IRS notice, another $25,000 applies for each 30-day period.
- The company must keep permanent books and records sufficient to establish its related-party transactions. Failing to keep them triggers the same penalty.
- For a foreign-owned LLC, reportable transactions include amounts paid in connection with forming and maintaining the company, so Form 5472 can be required in a year with no income.
We therefore keep the LLC's books from the first month, with every transaction with the owner and the owner's companies recorded separately, so the Form 5472 figures are ready by March.
Corporation: Form 1120 and 21% tax
A corporation computes federal tax as 21% of taxable income (IRS: Instructions for Form 1120, 2025). If it expects tax of $500 or more for the year, it pays estimated tax in four instalments, and tax payments must be made electronically. When a foreign shareholder owns 25% or more, Form 5472 for related-party transactions is attached to Form 1120. On top of federal tax, the corporation pays tax in the states where it does business, each with its own rates and rules.
Dividends to a foreign owner are taxed at source: most types of US-source income received by a foreign person are subject to 30% US tax, unless a tax treaty reduces it (IRS: NRA withholding). The company withholds and reports on Forms 1042 and 1042-S by March 15. Crystal.tax checks how the Ukraine–US tax treaty applies before the first payment.
State reporting: Delaware and Wyoming
Formation in a state creates a yearly obligation to that state, even when the company does no business there. Missing it leads to penalties, and in Wyoming to administrative dissolution.
| State and entity | What and when | Amount per the state |
|---|---|---|
| Delaware corporation | Annual report and franchise tax by March 1 | Minimum franchise tax $175 (authorized shares method) or $400 (assumed par value capital method); annual report fee $50; late penalty $200 plus 1.5% interest per month |
| Delaware LLC | Annual tax by June 1 | $400; late penalty $200 plus 1.5% interest per month |
| Wyoming LLC or corporation | Annual report by the first day of the formation month; may be filed up to 120 days early | License tax $60 or $0.0002 per dollar of Wyoming assets, whichever is greater; no report within 60 days of the due date leads to administrative dissolution |
Amounts per corp.delaware.gov, the LLC tax instructions, the Wyoming fee schedule and the Wyoming SOS FAQ, checked 10.2026. A company doing business in another state (office, staff, warehouse) generally registers there as a foreign entity and reports to that state as well.
BOI reporting to FinCEN as of 10.2026
The Corporate Transparency Act required companies to report beneficial ownership information (BOI) to FinCEN. In March 2025 an interim final rule exempted companies created in the United States, and on 11 August 2026 FinCEN issued a final rule, effective 14 August 2026: US companies are exempt from BOI reporting and no longer have to file (fincen.gov/boi). The obligation remains for foreign entities registered to do business in a US state: they report beneficial owners who are not US persons (FinCEN release, 11.08.2026). A Ukrainian company with a branch or state registration in the US should check BOI separately.
Sales tax and payroll
Sales tax in the US is set by the states; there is no single federal sales tax. Since the Supreme Court's decision in South Dakota v. Wayfair (2018), a state may require a seller to collect sales tax without physical presence in the state (585 U.S. 162). Economic nexus thresholds and rules for digital services differ by state, so sales tax registration is checked against actual sales: which states the customers are in, what is sold, and which marketplaces already collect the tax for the seller.
A company with US employees adds federal payroll reporting: Form 941 quarterly, Form 940 and W-2 by January 31, plus state taxes where the employee works. Withheld taxes are deposited monthly by the 15th or on a semi-weekly schedule, depending on the amounts. Payments to US contractors are reported on Form 1099-NEC by January 31.
Taking over from the previous agent
We start with a check: formation date, state status, the EIN and the IRS letter assigning it, forms filed for earlier years, bank statements and money flows between the company and the owner. If forms were missed, the partner accountant prepares them for all open years, and the owner receives a risk assessment before anything is filed. Differences are recorded in a handover report.
What the service includes
- diagnostic: entity type, tax classification, state status, EIN, filing and payment history;
- selecting and setting up the US partner accountant: scope, document flow, access;
- bookkeeping in cloud software with related-party transactions tracked separately;
- Form 5472 and pro forma 1120 for an LLC, Form 1120 and estimated tax for a corporation, Form 1065 and K-1s for a multi-member LLC;
- Forms 1042 and 1042-S for payments to foreign persons;
- payroll and sales tax monitoring in the states where the company sells or hires;
- state annual report and tax, liaison with the registered agent;
- management reporting for the owner: profit, cash flow, taxes due;
- a financial statements pack for the Ukrainian owner's CFC report, consolidation with a Ukrainian company on request.
How we work
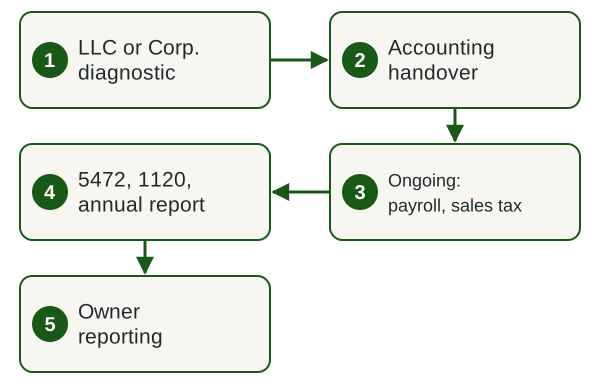
- Diagnostic. We confirm entity type and tax classification and check state status, EIN and past filings.
- Handover. We take over the books from the previous agent, rebuild missed years and record differences.
- Ongoing cycle. Documents, bank reconciliation, payroll and sales tax where they apply.
- Annual cycle. Form 5472, 1120 or 1065, 1042-S, state annual report and tax.
- Owner reporting. Management report, CFC and consolidation pack.
Reporting for the owner in Ukraine
For an owner who is a Ukrainian tax resident, a US LLC or corporation is usually a controlled foreign company: a stake above 50%, or above 10% where Ukrainian residents together hold 50% or more (Tax Code of Ukraine, sub-para. 39-2.1.2). Ukrainian law treats the LLC as a foreign legal entity, even though it is transparent for the IRS. Certified copies of the company's financial statements are attached to the CFC report (sub-para. 39-2.5.2), so the US books are kept to produce full year-end statements. We prepare the CFC pack together with reporting for foreign companies. The group's US market entry overview is at innovacg.com.
Registration and visas: other group companies
Forming the LLC or corporation, obtaining the EIN and appointing a registered agent is handled by crystal.tax: start a company in the USA. A US company gives no visa or right of residence by itself. Immigration matters are handled by legal.ua. Key Solutions steps in once the company exists or is being formed and is responsible for accounting and reporting.
What we need from you
- certificate of formation or incorporation, state and formation date;
- the IRS EIN assignment letter;
- LLC operating agreement or corporate bylaws, list of owners and their stakes;
- IRS forms and annual reports filed for earlier years, if the company has been operating;
- bank and payment platform statements;
- a list of transactions with the owner and the owner's other companies: contributions, loans, payments, services;
- employees and sales by state, if any;
- the owners' tax residence and tax numbers for Form 5472 and the CFC pack.
Documents are exchanged electronically. We do not need bank passwords.
Result
- the company's tax classification is confirmed and documented;
- Form 5472 with pro forma 1120, Form 1120 or Form 1065 filed on time and in the required way;
- state annual report and tax paid, company in good standing;
- payroll and sales tax filed without gaps where they apply;
- related-party records ready for IRS review;
- management report and CFC pack for the owner;
- an IRS and state deadline calendar for the next year.
Legal basis and sources
Official sources behind this page (IRS, FinCEN, Delaware and Wyoming, checked 10.2026)
- Instructions for Form 5472 — foreign-owned U.S. DE, filing method, $25,000 penalty, records;
- Instructions for Form 1120 (2025) — due date, 21% rate, estimated tax;
- Instructions for Form 7004 — 6-month extension to file, not to pay;
- Instructions for Form 1065 (2025) — partnership return of an LLC;
- Instructions for Form 1042, NRA withholding — withholding on payments to foreign persons;
- Employment tax due dates — Forms 941, 940, W-2, 1099-NEC;
- FinCEN: Beneficial Ownership Information — final rule of 11.08.2026, effective 14.08.2026;
- Delaware Division of Corporations — franchise tax, annual report, LLC annual tax;
- Wyoming Secretary of State — annual report and license tax;
- South Dakota v. Wayfair, 585 U.S. 162 (2018) — sales tax without physical presence;
- Tax Code of Ukraine, sub-paras. 39-2.1.2 and 39-2.5.2: controlling person and CFC report.
Why Key Solutions
- Company
- KEY SOLUTIONS AUDIT FIRM LLC, Ukrainian company code 39610085, registered since 30.01.2015.
- Roles
- US books, IRS forms, payroll, sales tax and state reports are prepared and filed by a US partner accountant; an audit or review requested by a bank or investor is carried out by an independent US audit firm; an authorized officer signs the returns; coordination, control and owner reporting are done by Key Solutions.
- Group
- We are part of Innova Consulting Group: company formation and US tax by crystal.tax, market entry by innovacg.com.
- Contract
- Scope, liability and confidentiality are set in a contract before work starts.
Frequently asked questions
What does a US LLC owned from Ukraine file?
A single-member LLC with a foreign owner is a disregarded entity by default and files a pro forma Form 1120 with Form 5472 with the IRS every year by the 15th day of the 4th month after year end (April 15 for a calendar year). The state of formation also requires an annual report or annual tax, and US employees or sales add payroll and sales tax.
Can Form 5472 be filed electronically?
Not for a foreign-owned LLC. Under the IRS instructions, the pro forma Form 1120 with Form 5472 goes by fax (300 DPI or higher) or by mail to the IRS unit in Ogden, marked "Foreign-owned U.S. DE". Form 7004 for an extension goes the same way.
What is the penalty for not filing Form 5472?
$25,000 per form per year. If the failure continues more than 90 days after IRS notice, another $25,000 applies for each 30-day period. A substantially incomplete form counts as not filed.
Does an LLC with no income still file Form 5472?
Often yes. For a foreign-owned LLC, reportable transactions include amounts paid in connection with forming and maintaining the company and contributions and distributions to the owner, so the form can be required in a year with no income.
Is BOI reporting to FinCEN required in 2026?
Not for companies created in the United States: FinCEN's final rule of 11.08.2026, effective 14.08.2026, exempts them from BOI. Foreign entities registered to do business in a US state still report beneficial owners who are not US persons.
What tax does a US corporation pay?
21% federal tax on taxable income on Form 1120, plus tax in the states where it does business. Dividends to a foreign owner are taxed at source at 30% unless a tax treaty reduces the rate.
What does Delaware charge to keep a company in good standing?
A corporation pays franchise tax (minimum $175 or $400 depending on the method) and a $50 annual report fee by March 1; an LLC pays $400 annual tax by June 1. Late payment costs $200 plus 1.5% interest per month. These are state charges; our service fee is set individually.
Does a Ukrainian owner need a CFC report for a US LLC?
Usually yes: under the Tax Code of Ukraine an LLC is a foreign legal entity even if it is transparent for the IRS. The company's financial statements are attached to the CFC report, so the US books are kept to produce them at year end.
Related services
Request a tailored proposal for your US company's accounting
Send the state and entity type, number of owners, whether there is an EIN, US employees and sales, which forms were filed for earlier years and who keeps the books today. We will reply with the scope, the split of roles and how to start.
Request a tailored proposal Telegram WhatsApp