
A review of financial statements is an engagement under ISRE 2400 in which an independent auditor performs mainly inquiries and analytical procedures and gives a conclusion with limited assurance. Key Solutions runs the review end to end for owners, banks and investors, from agreeing the format and preparing documents to the review report and a list of issues for your accountants. The review report is signed by an audit entity with a current entry in the Register.
+38 (068) 777-14-74 Telegram WhatsApp
In short
- When you need it: the owner wants an independent check, a bank or investor asks for a review, a parent company needs interim statements, or you want a check before a first audit.
- What you get: a review report with the auditor's conclusion and a letter listing errors and corrections for your accountants.
- Timing is fixed in the contract. A review is usually shorter than an audit of the same statements.
- The fee is agreed individually and depends on transaction volume, the number of entities, the reporting framework and the state of the books.
- Where to start: send the balance sheet and income statement and tell us who needs the conclusion.
What a review engagement is
Under Art. 1(1)(7) of Law No. 2258-VIII, a review of financial statements is an audit service. The auditor performs analytical procedures and inquiries of management and accounting staff and expresses a conclusion on the statements as a whole. The engagement follows ISRE 2400 (Revised), Engagements to Review Historical Financial Statements; where the company's annual auditor reviews interim statements, ISRE 2410 applies.
Review, audit or agreed-upon procedures
| Format | What it gives | Typical user |
|---|---|---|
| Review (ISRE 2400) | Limited assurance, conclusion on the statements as a whole | Owner, bank, investor, interim reporting |
| Voluntary audit under ISA | Reasonable assurance, audit report with an opinion | Tender, loan, sale of the business |
| Mandatory audit | Audit report for publication, signed by a partner firm entitled to perform statutory audits | Company required by law to publish audited statements |
| Agreed-upon procedures (ISRS 4400) | Factual findings without an auditor's conclusion | Donor, grant, checks of specific items |
What the service includes
- agreeing the purpose, the user of the report, the period and the reporting framework (Ukrainian GAAP or IFRS);
- assessing the accounting system, accounting policies and internal control;
- analytical procedures: trends, ratios, comparison with budget and prior periods;
- inquiries of management and accounting staff on material items, estimates, related parties and subsequent events;
- additional procedures where analytics point to a risk;
- a review report with a conclusion and a letter with errors and recommendations.
How we work
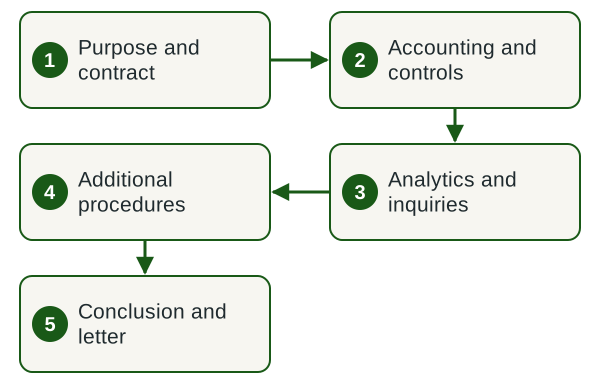
- Purpose, statements and contract. We agree the user of the report, the period, the framework and the engagement terms.
- Accounting and controls. We study accounting policies, the accounting system and internal control.
- Analytics and inquiries. We compare figures and put questions to management and accounting staff.
- Additional procedures. Where analytics point to a risk, we request documents and extend the work.
- Conclusion and letter. We deliver the review report and a list of corrections for your accountants.
Timing and cost
We fix the timing in the contract after a first look at the statements. It depends on transaction volume, the number of entities, the state of the books and how quickly your accountants respond. The fee is agreed individually and depends on the same factors plus the reporting framework and the deadline. Market price ranges from public procurement are collected in our article how much a financial statement audit costs.
What we need from you
- financial statements for the review period and the prior period;
- trial balance and accounting policies;
- read-only access to the accounting system;
- a contact in accounting who answers queries quickly;
- a management representation letter at the end of the review.
Result
- a review report with the auditor's conclusion;
- a letter listing errors found, their effect on the figures and corrections for the next reporting period;
- recommendations on accounting policies and internal control.
A review report and an audit report are different documents: under Art. 1(1)(6) of Law No. 2258-VIII an audit report is issued after an audit of financial statements. If your user needs an audit report, choose an audit.
Legal framework
Rules the work relies on
- Art. 1(1)(6), (7) and (9-3) of Law No. 2258-VIII: review as an audit service, audit report, interim reviews required by law.
- Art. 10(1) of Law No. 2258-VIII: independence of the reviewer.
- Art. 20(1) of Law No. 2258-VIII: audit services only after registration in the Register.
- ISRE 2400 (Revised) and ISRE 2410: review procedures and the form of the conclusion.
Why hand this to a team under contract
Statements without an independent check can hide errors that a bank, investor or the tax office will find later, at greater cost. The review report is signed by a registered audit entity that is independent of your accounting team, which is what banks and investors usually ask for. Scope, timing, liability and confidentiality are fixed in the contract.
Why Key Solutions
- Turnkey, with no extra hassle
- We take the whole task: documents, calculations, reporting and correspondence with the State Tax Service. You make the decisions, provide source documents and sign; we do the rest and contact you only when it matters.
- We take on the tax office
- Information requests, blocked tax invoices, inspection reports: we prepare explanations, rework documents and appeal until the issue is closed. Where the law is in dispute, we work together with the group's lawyers.
- We see it through
- Your case stays on track: the specialist running it remains with you, even if an inspection or audit drags on for months. Statutory audits are performed, and the report signed, by a partner audit firm entitled to perform them; we handle preparation and support through publication, so you deal with one team from start to finish.
- Boutique-level involvement
- A senior specialist runs your project personally (see the Our employees page), backed by 14 years of Innova group practice in 50+ countries. Non-standard tasks are our field: where you hear “it can’t be done”, we look for a lawful way, and group companies cover the rest: legal.ua for legal matters, crystal.tax for crypto-asset taxation.
- Your affairs stay yours
- Information about your company, turnover, payroll and counterparties reaches neither competitors nor third parties. We disclose only what the law or a procedure requires, and the contract says so.
- Faster and right the first time
- Full involvement: your specialist learns your books, contracts and business, so documents and reports are ready on time with no rework. The group's 14 years of experience let us get right the first time what takes some firms three attempts.
Frequently asked questions
What is a review of financial statements?
A review is an assurance engagement under ISRE 2400 (Revised) in which an independent auditor performs mainly inquiries and analytical procedures and expresses a conclusion with limited assurance. The auditor reports whether anything has come to their attention that suggests the financial statements are materially misstated.
How does a review differ from an audit?
A review gives limited assurance and is based mainly on inquiries and analytics. An audit gives reasonable assurance and ends with an audit report containing the auditor's opinion. A review is shorter and cheaper; an audit is needed where the law, a bank or an investor requires an audit report.
Who may perform a review in Ukraine?
A review of financial statements is an audit service (Art. 1(1)(7) of Law No. 2258-VIII), so only audit entities registered in the Register may provide it (Art. 20(1)). The reviewer must be independent of the company (Art. 10(1)). You can check the Register entry of the firm that signs the review report on the website of the Audit Public Oversight Body before signing the contract.
Can you review statements if you also keep our books?
A review requires independence from the company whose statements are reviewed (Art. 10(1) of Law No. 2258-VIII). The review report is therefore signed by an audit firm that neither keeps your books nor prepares your statements. If Key Solutions keeps your books, we prepare the statements and answer the auditor's queries.
Can a review replace a mandatory audit?
A mandatory audit requires an audit report for publication, so a review cannot take its place. If your company is subject to a mandatory audit, Key Solutions organises it end to end: a partner audit firm listed in the relevant section of the Register carries out the audit and signs the report, while we prepare the books and support you to publication.
How much does a review cost?
The fee is agreed individually. It depends on the volume of transactions, the number of legal entities, the reporting framework (Ukrainian GAAP or IFRS), the state of the books and the deadline. Send us the balance sheet and income statement and tell us who needs the conclusion, and we will quote before signing.
Related services
Let's discuss a review of your statements
Tell us who needs the conclusion (owner, bank, investor), the period and the reporting framework, and attach the balance sheet and income statement. We will reply with the format, timing and a quote.
Book a consultation Order the service +38 (068) 777-14-74 Telegram WhatsApp