A court appeal against a blocked tax invoice is an administrative claim to cancel the State Tax Service commission's refusal to register the invoice and to order its registration in the Unified Register of Tax Invoices. Key Solutions prepares the documentary evidence, calculations and tax position, and an advocate of the group at legal.ua represents the company in court.
+38 (068) 777-14-74 Telegram WhatsApp
In short
- When: the tax commission refused to register a tax invoice or adjustment, a complaint did not help, or you choose court straight away.
- You get an analysis of the decision and deadlines, an evidence register, calculations and a tax position for the claim.
- The court deadline is six months, or three months after a complaint to the tax authority (Art. 122 CAP). Our preparation time is fixed in the contract.
- Fees are agreed individually and depend on the number of invoices and the state of the documents. The court fee is paid separately.
- To start, send the suspension notices, the commission's decision and the explanations you filed.
Complaint or court: which route
The regional commission's refusal can be appealed administratively or in court (para. 12 of Procedure No. 520). An administrative appeal is a pre-trial procedure, and a decision already challenged in court is not appealed administratively (para. 56.18 of the Tax Code).
| Route | Deadline | Key point |
|---|---|---|
| Complaint to the tax authority | 10 working days after the decision (subpara. 56.23.1 TC) | No court fee; reviewed by the central commission |
| Claim without complaint | 6 months (Art. 122(2) CAP) | The court decision binds the tax authority |
| Claim after complaint | 3 months from receiving the complaint decision (Art. 122(4) CAP) | 6 months from the complaint if no decision was delivered |
Explanations and documents must go to the commission first; without them there is no refusal to appeal. We handle that stage under unblocking tax invoices and complaints under complaints to the tax authorities.
What the court decides and who carries the burden of proof
The claim usually asks the court to declare the decision unlawful, cancel it and order registration. Having cancelled the decision, the court may order the authority to take the steps needed to restore the claimant's rights (Art. 245(3) CAP); in these disputes that usually means registering the invoice. The tax authority must prove its decision was lawful (Art. 77(2) CAP), while the company shows the reality of the transaction with its documents: contracts, delivery and warehouse documents, bank statements and quality certificates (para. 5 of Procedure No. 520).
What the service includes
- Review of suspension notices, commission decisions and court deadlines.
- Checking primary documents and ledgers for each invoice.
- Reconciling stock balances by product code and recalculating the indicators behind the block.
- An evidence register referencing each document for the claim.
- VAT calculations and the effect on the buyer's input VAT.
- A tax position for the advocate and after the ruling, monitoring registration and adjusting the accounts.
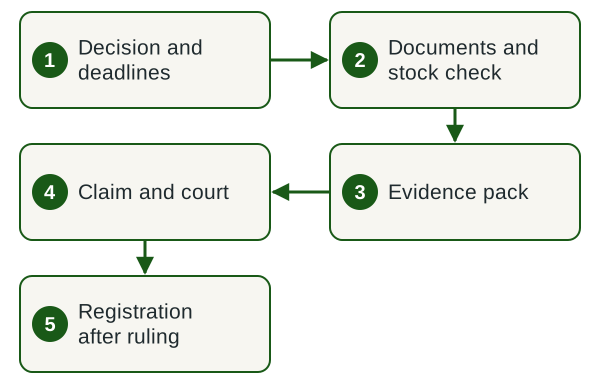
- Decision and deadlines We review the notices, the decision, the explanations filed and the Art. 122 deadlines.
- Documents and stock check We reconcile documents, ledgers and stock by product code.
- Evidence pack We build the evidence register, calculations and tax position.
- Claim and court An advocate at legal.ua files and runs the case; we answer accounting questions.
- Registration after ruling We monitor registration in the register and adjust the accounts.
Timing and cost factors
Our preparation time is fixed in the contract and depends on the number of invoices and decisions, how similar the transactions are and how complete the documents are. In our experience, collecting documents from suppliers and carriers takes longest, so start right after the suspension. The court sets its own timetable. Our fee is agreed individually; the court fee and the advocate's fee are paid separately.
What we need from you
- Suspension notices and the commission's decisions.
- The explanations filed and any complaint decision.
- Contract, primary, transport and warehouse documents.
- Bank statements for the payments.
- A power of attorney for the advocate if legal.ua takes the case.
Result
- An opinion on deadlines and the accounting side of the dispute.
- An evidence register and document pack for the claim.
- VAT calculations and a tax position for the advocate.
- After the ruling, a registered invoice and adjusted accounts.
Legal basis
Rules the work relies on
- Paras. 201.16, 56.1, 56.18 of the Tax Code — suspension and appeal of tax invoice registration.
- Paras. 5, 6, 9, 12 of Procedure No. 520 — explanations, documents, commission review, appeal.
- Arts. 122, 77, 245, 55, 57 of the Code of Administrative Procedure — deadlines, burden of proof, court powers, representation.
- Para. 20 of Procedure No. 1246 — registration based on a court decision.
- Art. 4 of Law No. 3674-VI — court fee rates.
Risks and why a contracted team helps
If the deadline is missed without valid reasons, the claim is returned, or left without consideration once proceedings have opened (Art. 123 CAP). Until the invoice is registered, the buyer cannot claim the input VAT (para. 198.6 of the Tax Code). Inconsistent dates, quantities or product codes across documents work against the taxpayer, so they should be found and explained before filing. We prepare the accounting side under a contract that fixes scope, timing and liability, and the court stage is run by an advocate of the group at legal.ua, so the court position rests on the same figures as your returns.
Why Key Solutions
- Turnkey, with no extra hassle
- We take the whole task: documents, calculations, reporting and correspondence with the State Tax Service. You make the decisions, provide source documents and sign; we do the rest and contact you only when it matters.
- We take on the tax office
- Information requests, blocked tax invoices, inspection reports: we prepare explanations, rework documents and appeal until the issue is closed. Where the law is in dispute, we work together with the group's lawyers.
- We see it through
- Your case stays on track: the specialist running it remains with you, even if an inspection or audit drags on for months. Statutory audits are performed, and the report signed, by a partner audit firm entitled to perform them; we handle preparation and support through publication, so you deal with one team from start to finish.
- Boutique-level involvement
- A senior specialist runs your project personally (see the Our employees page), backed by 14 years of Innova group practice in 50+ countries. Non-standard tasks are our field: where you hear “it can’t be done”, we look for a lawful way, and group companies cover the rest: legal.ua for legal matters, crystal.tax for crypto-asset taxation.
- Your affairs stay yours
- Information about your company, turnover, payroll and counterparties reaches neither competitors nor third parties. We disclose only what the law or a procedure requires, and the contract says so.
- Faster and right the first time
- Full involvement: your specialist learns your books, contracts and business, so documents and reports are ready on time with no rework. The group's 14 years of experience let us get right the first time what takes some firms three attempts.
Frequently asked questions
How do you challenge a blocked tax invoice in court?
Once the regional commission refuses to register the tax invoice, the taxpayer files an administrative claim asking the court to declare the decision unlawful, cancel it and order the State Tax Service to register the invoice (para. 12 of Procedure No. 520; Art. 245 of the Code of Administrative Procedure). The notices, the decision, the explanations filed and the primary documents are attached to the claim.
What is the deadline for going to court?
Without a prior complaint to the tax authority, the deadline is six months from the day the taxpayer learned of the violation (Art. 122(2) of the Code of Administrative Procedure). After a complaint, it is three months from receiving the decision on it, or six months from filing the complaint if no decision was delivered in time (Art. 122(4)).
Do we have to complain to the tax authority first?
A complaint is optional: the decision may be appealed administratively or in court (para. 56.1 of the Tax Code). An administrative appeal is a pre-trial procedure, and a decision already challenged in court can no longer be appealed administratively (para. 56.18). We choose the route together based on the number of invoices and the deadlines.
What is the court fee?
A legal entity pays one subsistence minimum for able-bodied persons per non-property claim (Art. 4 of Law No. 3674-VI), which is UAH 3,328 in 2026 (Art. 7 of Law No. 4695-IX). A 0.8 coefficient applies to electronic filing. The total depends on the number of claims.
Who represents the company in court?
An advocate (Art. 57(1) of the Code of Administrative Procedure) or the company's director or another authorised person as self-representation (Art. 55(3)). Key Solutions prepares the evidence, calculations and tax position, and an advocate of the group at legal.ua handles the representation.
When is the invoice registered after the court decision?
The invoice is entered in the Unified Register of Tax Invoices on the basis of a court decision that has entered into force. The registration date is the date stated in the decision or the date it entered into force (para. 20 of Procedure No. 1246). We then check the buyer's input VAT and your VAT return.
Related services
Let's assess your blocked invoice dispute
Send the suspension notices, the commission's decision and the date you received it. We will reply with the court deadlines, the missing documents and the cost of preparation.
Book a consultation Order the service +38 (068) 777-14-74 Telegram WhatsApp