


Working with non-residents means accounting for and taxing a Ukrainian company's transactions with foreign counterparties: exports, imports, services, royalties, loans and dividends. Key Solutions reviews the tax consequences of a deal before signing, calculates the taxes and keeps the accounts and returns for these transactions.
+38 (068) 777-14-74 Telegram WhatsApp
In short
- When: a first foreign contract, services bought from abroad, dividends, interest or royalties paid abroad, related-party deals.
- You get a written opinion, a tax calculation and a list of documents the deal needs.
- Timing is set after a first look at the documents and fixed in the contract.
- Fees are agreed individually and depend on deals, countries and the type of income.
- To start, send the draft contract or invoice and say who pays whom and for what.
Which transactions with non-residents need attention
In business, a non-resident is usually a foreign company, organisation or partnership formed under the laws of another state, or its branch or representative office in Ukraine; foreign diplomatic missions and individuals who are not Ukrainian residents are non-residents too (subpara. 14.1.122 of the Tax Code). The most common issues are:
- taxation of exports and imports;
- re-export of goods;
- transactions with related non-resident parties;
- sales through non-resident commission agents;
- transactions with counterparties in offshore jurisdictions;
- a non-resident's contribution to the charter capital of a Ukrainian company;
- work performed abroad using local subcontractors in that country.
Which taxes arise
What applies depends on the type of income, the counterparty's country and whether the parties are related.
| Transaction | What arises | Rule |
|---|---|---|
| Paying income to a non-resident | Withholding tax at payment: 15% base rate, 6% for freight; a treaty may lower it | subparas. 141.4.1, 141.4.2, 141.4.4 TC |
| Reduced treaty rate | Certificate of residence, beneficial owner of income | paras. 103.2, 103.4 TC |
| Non-resident services supplied in Ukraine | Recipient charges VAT and issues a tax invoice to itself | paras. 180.2, 208.2 TC |
| Purchases from listed jurisdictions | Financial result increased by 30% of the cost unless controlled | subpara. 140.5.4 TC |
| Related parties, commission agents | Controlled transactions above the thresholds | subparas. 39.2.1.1, 39.2.1.7 TC |
Currency deadlines and contract form
The National Bank sets settlement deadlines for exports and imports of goods (Art. 13 of Law No. 2473-VIII). For exported services the period runs from the date of the service certificate or invoice. Late settlement costs 0.3% per day, capped at the outstanding amount. Foreign trade contracts are made in simple written or electronic form, and exports of services can be documented by an accepted offer or an invoice (Art. 6 of Law No. 959-XII).
What the service includes
- Tax and accounting review of the draft contract: place of supply, currency, payment terms, supporting documents.
- Withholding tax, VAT, financial result adjustments and controlled transaction tests.
- Checking the certificate of residence and treaty conditions.
- Accounting for exchange differences, invoices, CMRs and customs declarations.
- Settlement deadline monitoring and reporting in the income tax and VAT returns.
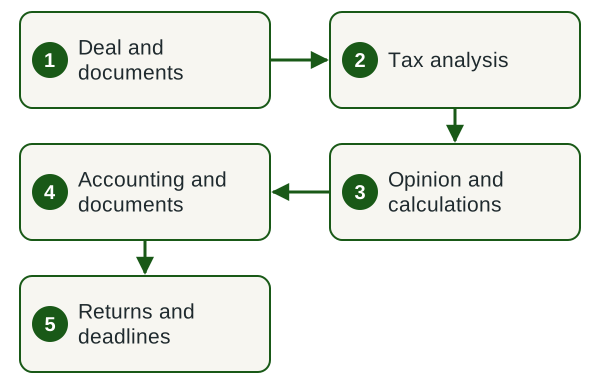
- Deal and documents We receive the draft contract, invoices, ownership chart and the counterparty's country.
- Tax analysis We check the Tax Code, the treaty, currency rules and controlled transaction tests.
- Opinion and calculations You receive a written opinion with the tax amounts and the documents the deal needs.
- Accounting and documents We set up the accounting entries, exchange differences and the document pack.
- Returns and deadlines We report the transaction in the returns and track the settlement deadlines.
Timing and cost factors
We name the timing after a first look at the documents and fix it in the contract. In our experience, the non-resident's certificate of residence takes the longest to obtain, so request it early. Fees depend on the number of deals and countries, the type of income, related parties, gaps in primary documents, and whether you need a one-off opinion or ongoing accounting.
What we need from you
- The draft or signed contract with the non-resident and its annexes.
- Invoices, service certificates, CMRs and customs declarations.
- The counterparty's certificate of residence, if you already have it.
- An ownership chart showing related counterparties.
- Foreign currency bank statements for the period.
- A contact person in accounting or finance.
Result
- A written opinion on the tax consequences with references to the law.
- Calculated withholding tax, VAT and adjustments.
- A document list for the deal and the accounts, and a schedule of settlement deadlines.
Legal basis
Rules the work relies on
- Subpara. 14.1.122 of the Tax Code — who is a non-resident.
- Subparas. 141.4.1, 141.4.2, 141.4.4 of the Tax Code — Ukrainian-source income of non-residents and the 15% and 6% (freight) rates.
- Art. 103 of the Tax Code — applying tax treaties and certificates of residence.
- Paras. 180.2, 208.2 of the Tax Code — VAT on services from non-residents.
- Art. 39 of the Tax Code — controlled transactions and reporting.
- Art. 13 of Law No. 2473-VIII — settlement deadlines and the penalty.
- Art. 6 of Law No. 959-XII — form of foreign trade contracts.
Risks and why a contracted team helps
Unwithheld tax is assessed on the Ukrainian tax agent with a fine, the treaty rate is lost without a certificate of residence, and late settlements accrue a daily penalty. We work under a contract that fixes scope, timing and liability. Contract drafting, registration with a foreign founder and disputes are handled by the group's lawyers at legal.ua.
Why Key Solutions
- Company
- ТОВ «АУДИТОРСЬКА ФІРМА «КЕЙ СОЛЮШНЗ», a Ukrainian limited liability company, EDRPOU code 39610085. The company's details are public in the Unified State Register (ЄДР).
- Contract
- We work under a contract: scope, timing, liability and confidentiality are agreed before work starts.
- Group
- Key Solutions is part of Innova Consulting Group: legal matters are handled by legal.ua, crypto-asset taxation by crystal.tax.
- Office
- Our office is at 77 Velyka Vasylkivska St., Kyiv. We serve clients across Ukraine remotely. The specialists who run engagements are listed on the Our employees page.
Frequently asked questions
Do we have to withhold tax when paying a non-resident?
Withholding tax applies to Ukrainian-source income listed in subpara. 141.4.1 of the Tax Code: interest, dividends, royalties, freight, engineering, lease payments and others. The base rate is 15% (subpara. 141.4.2) and freight is taxed at 6% (subpara. 141.4.4); a tax treaty may reduce the rate or exempt the income. We check each payment against the contract and invoice.
How do we apply a reduced treaty rate?
The reduced rate applies at payment if the non-resident is a resident of the treaty country and the beneficial owner of the income (para. 103.2 of the Tax Code). You need a certificate of residence from that country's competent authority, legalised and translated (paras. 103.4, 103.5).
Who pays VAT on services from a non-resident?
If the place of supply is in Ukraine, the Ukrainian recipient charges the VAT (para. 180.2 of the Tax Code). A VAT payer issues a tax invoice to itself, which then supports its input VAT (para. 208.2). The place of supply depends on the type of service under Article 186.
When do transactions with a non-resident become controlled?
Transactions with related non-residents, through non-resident commission agents or with counterparties in jurisdictions on the Cabinet of Ministers list are controlled when annual income exceeds UAH 150 million and the volume with one counterparty exceeds UAH 10 million (subpara. 39.2.1.7 of the Tax Code). The report is due by 1 October of the following year (subpara. 39.4.2). Documentation is prepared under our transfer pricing service.
Can you help with the foreign trade contract?
Yes, on the tax and accounting side: we review the price, currency, payment terms and supporting documents that drive the taxes on the deal. The legal text and disputed clauses are drafted by the group's lawyers at legal.ua, so both parts stay consistent.
How much does support for non-resident transactions cost?
Fees are agreed individually and depend on the number of deals and countries, the type of income, related parties and the state of the documents. Send a draft contract or invoice and we will quote the scope, timing and fee before signing.
Related services
Let's review your deal with a non-resident
Send the draft contract or invoice and tell us the counterparty's country and the type of payment. We will reply with the taxes on the deal, the documents to add, and the timing and fee for an opinion.
Book a consultation Order the service +38 (068) 777-14-74 Telegram WhatsApp