

Accounting and reporting for a Czech s.r.o. means ongoing bookkeeping under the Czech Accounting Act, VAT (DPH) and corporate income tax returns, and the annual financial statements (účetní závěrka) filed with the public register. Key Solutions coordinates this work for owners from Ukraine: a Czech partner accountant keeps the books in the Czech system and files with the tax authority, while we set the tasks, control deadlines and figures, and prepare reporting for the owner.
Request a tailored proposal Telegram
In brief
- For: owners from Ukraine who have or plan a Czech s.r.o., and groups where the Czech company works alongside a Ukrainian LLC.
- What we do: take over the books from the previous accountant, set up accounting and VAT, control the annual accounts, and prepare the company for an audit when one is required.
- Who signs: returns are filed by a Czech accountant or tax adviser, and the audit report is signed by a Czech auditor listed with the Chamber of Auditors (Komora auditorů ČR). Key Solutions is responsible for coordination, control and owner reporting.
- Fees: a tailored proposal after a short description of the company; we publish no price list.
- To start: tell us whether the company is registered, whether it is a VAT payer, how many transactions it has per month and who keeps the books now.
What Czech law requires from an s.r.o.
A Czech s.r.o. is an accounting entity under Act No. 563/1991 Coll. on Accounting and keeps full double-entry books (§ 9(1) and (4)). The books are kept in Czech; source documents in a foreign language are allowed when they are comprehensible (§ 4(13)). A company registered in Czechia follows Czech rules even when its owner and director live in Ukraine.
| Obligation | What and when | Legal basis |
|---|---|---|
| Annual accounts (účetní závěrka) | Balance sheet (rozvaha), profit and loss account (výkaz zisku a ztráty) and notes (příloha) as at the last day of the accounting period; medium and large companies add a cash flow statement and a statement of changes in equity | § 18 and § 19, Act 563/1991 Coll. |
| Publication | Filing with the collection of deeds (sbírka listin) of the Commercial Register within 12 months of the balance sheet date; with the auditor's report when an audit is mandatory | § 21a(2)–(4), Act 563/1991 Coll. |
| Corporate income tax (DPPO) | Rate 21%. Return due 3 months after the period ends, 4 months if filed electronically, 6 months with a mandatory audit or when filed by a tax adviser | § 21, Act 586/1992 Coll.; § 136, Act 280/2009 Coll. |
| VAT (DPH) | Rates 21% and 12%. A VAT payer files the return and the control statement (kontrolní hlášení) electronically within 25 days after the period | § 47, § 101a, § 101e, Act 235/2004 Coll.; § 136(4), Act 280/2009 Coll. |
| Audit | Medium and large entities; for periods starting on or after 1 January 2026, small s.r.o. companies have no statutory audit duty under the Accounting Act | § 20, Act 563/1991 Coll., as amended by Act 316/2025 Coll. |
Tax rates and thresholds follow the laws in force on 9 October 2026: Act 563/1991 Coll., Act 235/2004 Coll., Act 586/1992 Coll., Act 280/2009 Coll..
VAT: when an s.r.o. becomes a payer and how it reports
A company seated in Czechia becomes a VAT payer from 1 January of the following year once its domestic turnover for a calendar year exceeds CZK 2,000,000 (§ 6(1), Act 235/2004 Coll.). If turnover in the current year exceeds CZK 2,536,500, the company becomes a payer from the day after that threshold is crossed (§ 6(2)). Turnover is therefore worth tracking monthly from the first invoice.
- the tax period is a calendar month; quarterly periods are possible when the previous year's turnover did not exceed CZK 15,000,000, except in the calendar year of registration and the following calendar year; the switch is notified to the tax office by the end of January (§ 99, § 99a);
- the VAT return is due within 25 days after the period ends (§ 136(4), Act 280/2009 Coll.);
- a legal entity files the control statement monthly within 25 days after the month ends, and this deadline cannot be extended (§ 101e);
- returns, control statements and EC sales lists are filed electronically only (§ 101a); an EC sales list (souhrnné hlášení) is required for supplies of goods and services to VAT payers in other EU states (§ 102).
For a Czech company with a Ukrainian owner, the typical questions are transactions with the Ukrainian LLC, services bought from abroad under reverse charge, and EU supplies. We map these flows before the first return so the books and VAT agree from month one.
When a Czech s.r.o. needs a statutory audit
The statutory audit duty is set by § 20 of Act 563/1991 Coll. Amending Act No. 316/2025 Coll. changed it from 1 January 2026: an audit is mandatory for medium and large accounting entities, and wherever a special law requires one. Small companies have no statutory audit duty under the Accounting Act for periods starting on or after 1 January 2026. The Czech Ministry of Finance explained the transition in a letter dated 4 September 2025 (Ministry of Finance position).
| Category | Limits: does not exceed at least 2 of 3 at the balance sheet date | Audit |
|---|---|---|
| Micro | total assets CZK 11m, net turnover CZK 22m, 10 employees | only if a special law requires it |
| Small | total assets CZK 120m, net turnover CZK 240m, 50 employees | from periods starting 01.01.2026, only if a special law requires it |
| Medium | total assets CZK 600m, net turnover CZK 1.2bn, 250 employees | mandatory |
| Large | exceeds 2 of 3 medium limits | mandatory |
The category changes from the next period once the company exceeds, or stops exceeding, the limits at two consecutive balance sheet dates (§ 1e(2)). Category limits: § 1b of Act 563/1991 Coll. as currently in force.
Accounts for 2025. For accounting periods that started before 1 January 2026 the previous wording applies. A small s.r.o. needed an audit when, at the balance sheet date and in the preceding period, it reached or exceeded at least two of three values: total assets CZK 40m, net turnover CZK 80m, 50 employees. Calendar-year 2025 accounts are still tested against these criteria.
In Czechia only auditors licensed by Komora auditorů ČR and entered in its register may carry out audit work (§ 2, § 3(1) and § 11 of Act 93/2009 Coll. on Auditors). Such an auditor signs the statutory audit report of a Czech s.r.o. Key Solutions prepares the books, the document pack and explanations for the audit and coordinates the work with the Czech auditor until the accounts are published in the register.
Handing over the books of a Czech s.r.o.
A change of accountant is the most common reason clients contact us: the previous provider stopped responding, the owner cannot see the figures, or last year's accounts were never filed. We run the handover against a checklist so the new accountant starts without gaps.
- accounting books and trial balance at the handover date, the last signed účetní závěrka;
- corporate income tax and VAT returns, control statements and filing confirmations for recent periods;
- statements for all bank accounts, registers of issued and received invoices, contracts with counterparties;
- employee and payroll data, where relevant;
- a check that prior years' accounts are published in the sbírka listin;
- access to the company's data box (datová schránka) and a filing power of attorney for the new accountant.
Any discrepancies found during the handover are recorded in a separate memo with a correction plan and deadlines.
What the service includes
- diagnostics: entity category, VAT status, audit duty, state of prior years' reporting;
- setting up the books with a Czech partner accountant: chart of accounts, document flow, month-end schedule;
- control of monthly VAT returns and control statements before the filing date;
- control of the annual účetní závěrka, the corporate income tax return and publication in the sbírka listin;
- audit preparation and coordination with the Czech auditor when an audit is mandatory;
- management reporting for the owner: profit, cash flow, taxes payable;
- a financial statements pack for the Ukrainian owner's CFC report, IFRS statements or consolidation with the Ukrainian LLC on request.
How we work
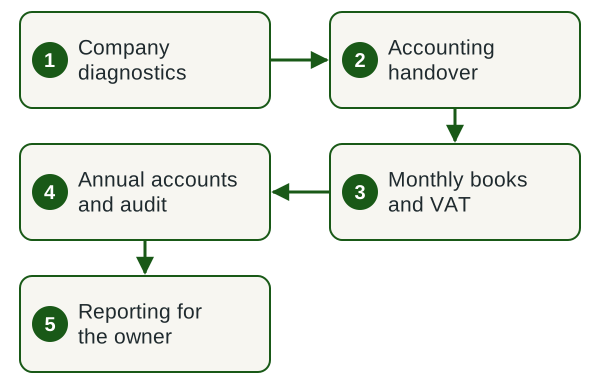
- Diagnostics. We obtain the register extract, the latest accounts and returns, and determine the company's category and obligations.
- Accounting handover. We take over the books from the previous accountant against a checklist and record discrepancies.
- Monthly cycle. Source documents, month-end close, VAT returns and control statements on time.
- Annual reporting. Účetní závěrka, corporate income tax return, audit where required, publication in the register.
- Owner reporting. Management report, CFC and consolidation pack.
Reporting for the owner in Ukraine
For an owner who is a Ukrainian tax resident, a Czech s.r.o. is often a controlled foreign company: a stake above 50%, or above 10% where Ukrainian residents together hold 50% or more (subpar. 39-2.1.2 of the Tax Code of Ukraine). The CFC report must be accompanied by certified copies of the company's financial statements (subpar. 39-2.5.2), so the Czech účetní závěrka is needed in Ukraine as well. We prepare the statements and the CFC pack together with our financial reporting for foreign companies service, and the CFC report and the owner's tax calculation are handled by crystal.tax, a group company.
Registration, address and residence — through other group companies
Registration of an s.r.o., a registered address, changes of director or members, and a separate assessment of a business visa are arranged by INNOVA Consulting Group; see company services in Czechia by INNOVA. Registering a company does not by itself give the owner a right to live in Czechia. Key Solutions comes in once the company exists or is being registered and is responsible for accounting and reporting.
What we need from you
- company name and IČO, or the planned registration date;
- the latest annual accounts and tax returns, if the company is already trading;
- bank statements and a list of main counterparties;
- contact details of the previous accountant for the handover;
- the list of owners and their tax residence for the CFC pack.
We accept documents electronically. We never ask for banking passwords.
Result
- the Czech s.r.o.'s books are closed monthly, VAT returns and control statements filed on time;
- the annual účetní závěrka and corporate income tax return filed, and the accounts published in the sbírka listin;
- an audit report where the company falls under the statutory audit duty;
- a management report and CFC pack for the owner;
- a calendar of deadlines for the next year.
Legal basis
Czech rules behind the work (wording in force on 09.10.2026)
- Act No. 563/1991 Coll. on Accounting — § 1b and § 1e (categories), § 4(13) (language), § 9 (scope of bookkeeping), § 18–19 (účetní závěrka), § 20 (audit), § 21a (publication), § 37a (fine for non-publication up to 3% of total assets);
- Act No. 316/2025 Coll. — amendment: new category limits and removal of the statutory audit duty for small entities from 01.01.2026;
- Act No. 93/2009 Coll. on Auditors — § 3 and § 11: audit work only by auditors in the register of Komora auditorů ČR;
- Act No. 235/2004 Coll. on VAT — § 6 (registration thresholds), § 47 (rates), § 99–99a (tax period), § 101a, § 101e, § 102 (electronic filing, control statement, EC sales list);
- Act No. 586/1992 Coll. on Income Taxes — § 21: corporate income tax rate 21%;
- Act No. 280/2009 Coll., Tax Procedure Code — § 136: return deadlines;
- Tax Code of Ukraine — subpar. 39-2.1.2 and 39-2.5.2: controlling person and CFC report.
Why Key Solutions
- Company
- ТОВ «АУДИТОРСЬКА ФІРМА «КЕЙ СОЛЮШНЗ», a Ukrainian limited liability company, EDRPOU code 39610085, registered on 30.01.2015.
- Roles
- Czech bookkeeping and filing — a Czech partner accountant; audit — a Czech auditor in the register of Komora auditorů ČR; coordination, control and owner reporting — Key Solutions.
- Group
- We are part of Innova Consulting Group: company registration and corporate changes in Czechia — INNOVA, owner taxes and CFC — crystal.tax, legal matters — legal.ua.
- Contract
- Scope, deadlines, liability and confidentiality are fixed in a contract before work starts.
FAQ
Can a Czech s.r.o. be run from Ukraine for accounting purposes?
A Czech company keeps its books under Act No. 563/1991 Coll. in Czech (§ 4(13)), and its VAT and corporate income tax returns are filed electronically with the Czech Financial Administration. In practice the books and filings are handled by an accountant who works with Czech forms and has access to the company's data box; in our setup this is a Czech partner accountant. Key Solutions sets the tasks, controls deadlines and figures, and prepares owner reporting.
When must an s.r.o. register as a VAT payer?
From 1 January of the following year if its domestic turnover for a calendar year exceeds CZK 2,000,000, or from the day after turnover exceeds CZK 2,536,500 in the current year (§ 6, Act 235/2004 Coll.). A VAT payer files the return and the control statement electronically within 25 days after the period ends.
Does my s.r.o. need a statutory audit?
For accounting periods starting on or after 1 January 2026, § 20 of Act 563/1991 Coll. requires an audit for medium and large entities and wherever a special law requires one. A company becomes medium when, at two consecutive balance sheet dates, it exceeds 2 of 3 small-entity limits: total assets CZK 120m, net turnover CZK 240m, 50 employees. Accounts for 2025 are still tested against the old criteria: 2 of 3 values of CZK 40m assets, CZK 80m turnover, 50 employees.
Who signs the audit report of a Czech company?
An auditor licensed by Komora auditorů ČR and entered in its register (§ 3 and § 11, Act 93/2009 Coll.). Key Solutions prepares the books and the document pack for the audit and coordinates the work with the Czech auditor until the accounts are published in the sbírka listin.
What are the deadlines for annual accounts and the corporate tax return?
The corporate income tax return is due within 3 months after the period ends, 4 months if filed electronically, or 6 months if the company has a statutory audit or a tax adviser files the return (§ 136, Act 280/2009 Coll.). The účetní závěrka must be published in the sbírka listin within 12 months of the balance sheet date (§ 21a, Act 563/1991 Coll.).
How do we switch from our current accountant?
We collect the books and trial balance, the latest accounts, returns and filing confirmations, invoice registers and data box access from the previous accountant. Discrepancies are recorded in a memo with a correction plan, and then the monthly cycle starts.
Does a Czech s.r.o. give the owner a right to live in Czechia?
Not automatically: company registration and residence permits are separate procedures with separate requirements. INNOVA Consulting Group assesses business visas and residence separately, and Key Solutions is responsible for the company's accounting and reporting.
How much does accounting for a Czech s.r.o. cost?
We prepare a tailored proposal after a short description of the company. The scope depends on the number of transactions and accounts, VAT status, audit duty, the state of prior years' books, and whether CFC or consolidation reporting is needed.
Related services
Request a tailored proposal for your s.r.o.
Tell us whether the company is trading, whether it is a VAT payer, how many transactions it has per month and who keeps the books now. We will reply with the scope of work, the split of roles and timelines.
Request a tailored proposal Telegram WhatsApp