


Accounting for a sole proprietor (FOP) in Ukraine means recording income, calculating the single tax, social contribution and military levy, and filing the entrepreneur's returns through an outside accountant under a contract. Key Solutions supports Group 2 and Group 3 FOPs, with or without VAT, in Kyiv and remotely: we watch the income limit, deadlines and amounts due.
+38 (068) 777-14-74 Telegram WhatsApp
In short
- When you need it: registering as a FOP, VAT registration, the first employees, foreign-currency income, income close to the limit.
- What you get: income records, returns filed on time and a list of taxes and social contribution due, with dates.
- Start: with complete documents we take over from the next reporting period; if there are gaps, we first restore the records.
- Cost: depends on the group, VAT, number of transactions and employees. We quote the fee after reviewing your accounts.
- How to start: book a consultation and tell us your group, single-tax rate, VAT status and number of employees.
Accountant for Group 2 and Group 3 FOPs: records and returns
A FOP (фізична особа-підприємець) is an individual registered as an entrepreneur. A FOP can choose the simplified system and pay the single tax under the Tax Code of Ukraine (Податковий кодекс, ПКУ). The scope of accounting depends on the single-tax group, VAT status and employees. Paragraph references below are to the Tax Code unless stated otherwise.
| FOP group | Records we keep | Returns and payments |
|---|---|---|
| Group 2 | Monthly income records (para. 296.1), limit and headcount control | Annual return (para. 296.2), monthly single-tax advance (para. 295.1) |
| Group 3 without VAT | Monthly income records (para. 296.1), limit and foreign-currency income control | Quarterly return (para. 296.3), payment after the filing deadline (para. 295.3) |
| Group 3 with VAT | Income and expense records in the standard form (para. 296.1), tax invoices in the register (ЄРПН) | Monthly VAT return (para. 203.1) and quarterly single-tax return |
| FOP with employees | Payroll, personal income tax, military levy and social contribution for staff, HR records | Quarterly payroll tax report broken down by month (para. 51.1) |
Foreign-currency income is converted into hryvnias at the National Bank of Ukraine rate on the date of receipt (para. 292.5): both the tax and the income limit are based on this amount. For FOP contractors of IT companies, see accounting services for IT companies.
FOPs with foreign clients and foreign nationals as FOPs
Group 2 may provide services only to single-tax payers and to the general public (sub-para. 2 of para. 291.4), so a FOP who sells services to foreign companies works in Group 3. Individuals who are non-residents of Ukraine for tax purposes cannot pay the single tax (sub-para. 291.5.7). For a foreign national, we therefore check tax residence status at the start, together with the group and the permitted activities (para. 291.5).
Accounting for a Group 3 FOP with VAT
A Group 3 FOP with VAT pays the single tax at the reduced rate and VAT on general terms (para. 293.3). The VAT reporting period is a calendar month (para. 202.1), so reporting runs on two cycles: VAT monthly, single tax quarterly.
Mandatory VAT registration based on the supply threshold does not apply to single-tax payers in Groups 1–3 (para. 181.1). A Group 3 FOP may register for VAT voluntarily (para. 182.1), for example when customers need input VAT. If an invoice registration is suspended, we handle unblocking of tax invoices.
FOP income limits, taxes and social contribution in 2026
Limits and fixed payments are calculated from the minimum wage on 1 January: UAH 8,647 in 2026 (Art. 8 of the State Budget Law for 2026, № 4695-IX).
- Group 2 income limit: 834 minimum wages, UAH 7,211,598 a year, with up to 10 employees (sub-para. 2 of para. 291.4).
- Group 3 income limit: 1,167 minimum wages, UAH 10,091,049 a year, with no cap on employees (sub-para. 3 of para. 291.4).
- Single tax: Group 2 pays the local council rate of up to 20% of the minimum wage, up to UAH 1,729.40 a month (sub-para. 2 of para. 293.2); Group 3 pays 5% of income, or 3% for VAT payers (para. 293.3).
- Military levy: UAH 864.70 a month (10% of the minimum wage) for Group 2 and 1% of income for Group 3 (sub-para. 1.3 of para. 16-1, subsection 10, section XX).
- Social contribution (ЄСВ) for yourself: at least 22% of the minimum wage, UAH 1,902.34 a month, paid by the 20th day of the month after the quarter (Part 5 Art. 8, Part 8 Art. 9 of Law No. 2464-VI). The martial-law right to skip it (item 9-19, section VIII of that law) is suspended for 2026 (item 3 of the Final Provisions of Law No. 4695-IX).
When a FOP should consider an LLC
We discuss moving to an LLC when income approaches the Group 3 limit, partners join, or the business needs to separate the owner's property from the company's. The forms are compared on our page for small business in Ukraine, and LLC bookkeeping is described on the page on accounting services for an LLC.
What FOP accounting includes
- income records based on bank statements and cash;
- control of the income limit and of activities allowed under the simplified system (para. 291.5);
- single tax, military levy and social contribution calculations, with a list of amounts and payment dates;
- the single-tax return with the social contribution section; for VAT payers, tax invoices and VAT returns;
- payroll, HR records and the payroll tax report for FOPs with employees;
- checking whether your activity requires a software cash register (ПРРО) (Art. 9 of Law No. 265/95-ВР) and matching receipts to takings;
- reconciliation with the budget and replies to State Tax Service (ДПС) requests.
How we work
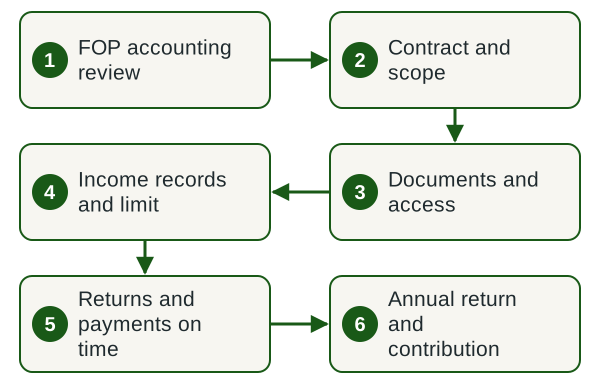
- FOP accounting review We check the group, returns, tax payments and social contribution.
- Contract and scope We agree the areas of work, bank statement handover dates and each party's responsibility.
- Documents and access We receive bank statements and agree how reports are signed with a qualified electronic signature (КЕП).
- Income records and limit Each month we record receipts and warn you when income approaches the limit.
- Returns and payments on time We file returns and send you the amounts and payment dates.
- Annual return and contribution We close the year and reconcile the social contribution (ЄСВ) paid.
Timelines
We take over from the next reporting period if the records for past periods are complete; if there are gaps, we first restore the records. Under the Tax Code, the quarterly return is due within 40 calendar days after the quarter ends (sub-para. 49.18.2) and the annual return within 60 days after the year ends (sub-para. 49.18.3). Group 3 single tax is paid within 10 calendar days after the filing deadline (para. 295.3).
What affects the cost of FOP accounting
- single-tax group and VAT status;
- number of bank transactions, accounts and contracts per month;
- employees and payments under civil-law contracts;
- foreign-currency income, imports or exports;
- state of the records at the start and whether past periods need restoring.
We quote the monthly fee after reviewing the accounts and fix it in the contract before the work starts. One-off tasks, such as amended returns for past periods, are priced separately.
What we need from you
- An extract from the register of single-tax payers and your list of activities (КВЕД).
- Bank statements for all FOP accounts for the current year.
- Returns filed and State Tax Service receipts for the last year.
- Contracts with your main customers and suppliers.
- An agreed procedure for signing reports with a КЕП, set out in the contract.
- A monthly date for sending bank statements and documents.
Result
- Returns filed on time, with State Tax Service receipts.
- A list of taxes and social contribution due, with amounts and dates.
- Income records ready for a tax inspection.
- A warning when income approaches the group limit.
- Replies to State Tax Service requests.
Find out the cost for your FOP
Tell us your group, VAT status and number of transactions per month. We will reply with the scope of work and the monthly fee.
Legal framework
Rules the work relies on
- sub-paras. 2–3 of para. 291.4, para. 291.5 and paras. 293.2–293.4 of the Tax Code — single-tax groups, income limits, eligibility and rates.
- paras. 181.1, 182.1, 202.1 and 203.1 of the Tax Code — VAT registration and VAT reporting.
- Arts. 295, 296 and para. 298.2.3 of the Tax Code — payment, records, returns, move to the general system.
- para. 16-1 and sub-para. 69.1 of para. 69, subsection 10, section XX of the Tax Code — military levy for FOPs, relief from fines under martial law.
- Arts. 4, 7, 8 and 9 of Law No. 2464-VI — social contribution (ЄСВ) for FOPs.
- Art. 8 and item 3 of the Final Provisions of Law No. 4695-IX — minimum wage for 2026, suspension of item 9-19, section VIII of Law No. 2464-VI.
- Arts. 9 and 17 of Law No. 265/95-ВР — software cash registers (ПРРО) and penalties.
Risks and why to hand the work to a team under contract
Income above the limit is taxed at 15% (sub-para. 1 of para. 293.4 of the Tax Code). A late return costs a UAH 340 fine, and a repeat within a year UAH 1,020 (para. 120.1). Under martial law, a taxpayer who could not file on time is released from the fine if the return is filed within six months after martial law ends (sub-para. 69.1 of para. 69, subsection 10, section XX). Taking payment without a ПРРО where one is required carries a fine of 100% of the sale amount, and 150% for a repeat violation (item 1 of Art. 17 of Law No. 265/95-ВР).
A FOP's limit, deadlines and amounts due need checking every month. A Key Solutions accountant does this under a contract that sets out the areas of work, deadlines and the firm's responsibility.
Why Key Solutions
- Company
- ТОВ «АУДИТОРСЬКА ФІРМА «КЕЙ СОЛЮШНЗ», a Ukrainian limited liability company, EDRPOU code 39610085. The company's details are public in the Unified State Register (ЄДР).
- Register
- Key Solutions is entered in the Register of Auditors and Audit Entities (Реєстр аудиторів та суб'єктів аудиторської діяльності) under No. 4669.
- Contract
- We work under a contract: the scope, deadlines and responsibility are agreed before the work starts. Client information is protected by professional secrecy (Art. 11 of Law No. 2258-VIII).
- Group
- We are part of Innova Consulting Group: legal matters are handled by legal.ua, crypto-asset taxation by crystal.tax.
- Office
- Our office is at 77 Velyka Vasylkivska Street, Kyiv. Clients elsewhere in Ukraine are served remotely. The specialists who run our projects are listed on the Our employees page.
Frequently asked questions
How much does accounting for a FOP cost?
The cost of accounting for a FOP depends on the group, VAT status, number of transactions per month, employees and foreign-currency income. We quote the fee after reviewing the accounts and fix it in the contract. One-off tasks, such as restoring records for past periods, are priced separately.
What does accounting for a Group 3 FOP include?
For a Group 3 FOP the accountant records income, watches the limit, calculates the single tax, military levy and social contribution, files quarterly returns and sends the amounts due. VAT payers also need tax invoices, and employers need payroll.
How is a Group 3 FOP with VAT accounted for?
A Group 3 FOP with VAT keeps income and expense records in the standard form (para. 296.1 of the Tax Code), registers tax invoices in ЄРПН and files two returns: a monthly VAT return and a quarterly single-tax return.
What happens if a FOP exceeds the income limit?
The excess is taxed at an increased rate (sub-para. 1 of para. 293.4 of the Tax Code). A Group 3 FOP moves to the general system from the first day of the month after the quarter of the excess (sub-para. 3 of para. 298.2.3); a Group 2 FOP does so unless it switches to Group 3 (sub-para. 1 of para. 298.2.3). That is why the accountant tracks the limit every month.
Does a FOP pay the social contribution for themselves in 2026?
Yes. A single-tax FOP pays the social contribution (ЄСВ) for themselves every quarter, at least the minimum contribution (item 3 of Part 1 Art. 7 of Law No. 2464-VI); the martial-law right to skip it is suspended for 2026. FOPs who receive an old-age or long-service pension, people with disabilities, and those of pensionable age who receive a pension or social assistance are exempt (Part 4 Art. 4 of Law No. 2464-VI).
Can a foreign national pay the single tax as a FOP?
It depends on the person's tax residence. Sub-para. 291.5.7 of the Tax Code closes the simplified system to non-resident individuals, and residence is determined under sub-para. 14.1.213. We check residence status at the start, together with the group and the list of activities.
How do you take over a FOP's accounts from a previous accountant?
We start with a review: we reconcile filed returns, tax and social contribution payments, bank statements and the budget settlement balance. Errors and gaps are corrected first with amended returns or restored records, and then we keep the accounts from the next reporting period.
Related services
Let's discuss your FOP accounts
Tell us your group and single-tax rate, whether you pay VAT or have employees, and the approximate number of transactions per month. We will reply with the scope of work, the monthly fee and a start date.
Book a consultation Order the service +38 (068) 777-14-74 Telegram WhatsApp