A tax complaint in Ukraine is a written appeal to a higher tax authority against a tax notice-decision or another decision of the State Tax Service. Key Solutions prepares objections to tax audit reports, complaints with calculations and evidence, and replies to tax authority requests.
+38 (068) 777-14-74 Telegram WhatsApp
In short
- Deadline: 10 working days after receiving the tax notice-decision; a complaint filed on time suspends payment of the assessed amount (Art. 56.3, 56.15 of the Tax Code).
- The tax authority must decide within 20 calendar days, extendable to 60; if it misses the deadline, the complaint is deemed fully upheld (Art. 56.8, 56.9).
- What you receive: an assessment of your position, the objection or complaint text with calculations, certified supporting documents and support during the review.
- Cost depends on the amount in dispute, the number of issues and the volume of documents.
- Where to start: send us the audit report, the tax notice-decision or the tax authority's request.
Which decisions can be appealed, and where
A taxpayer who believes the tax authority assessed the liability incorrectly, or made any other decision that breaches the law or exceeds its powers, may file a complaint with the higher-level authority (Art. 56.2 of the Tax Code). Complaints about decisions of regional tax offices go to the State Tax Service of Ukraine. At the same time, the taxpayer must notify the office that made the decision that it is being appealed. A liability the taxpayer assessed itself cannot be appealed.
A tax audit report usually comes first. Objections to it, with additional documents and explanations, are filed within 10 working days after the report is received and are reviewed by the tax office's objections committee (Art. 86.7). The tax notice-decision is then issued on the basis of the committee's conclusion.
Deadlines at a glance
| Step | Deadline | Tax Code |
|---|---|---|
| Objections to the audit report | 10 working days after the report is received | Art. 86.7 |
| Complaint about a tax notice-decision | 10 working days after the decision is received; up to 6 months with a request to restore the deadline | Art. 56.3 |
| Decision not related to a tax violation | 30 calendar days after the decision is received | Art. 56.12 |
| Review of the complaint by the authority | 20 calendar days, extendable to 60 | Art. 56.8, 56.9 |
| Court claim after the administrative appeal | one month after the procedure ends | Art. 56.19 |
Martial law rule. Until martial law ends, if tax assessed after a documentary audit resumed or started from 1 August 2023 is paid within 30 calendar days of receiving the tax notice-decision, the fines on that amount are cancelled and no late-payment interest accrues, but the amount paid can no longer be appealed (subpara. 69.37, para. 69, subsection 10, section XX of the Tax Code).
What a complaint must contain
The format is set by the Procedure approved by Ministry of Finance Order No. 916 of 21 October 2015. The complaint states the taxpayer's name and tax address, the tax authority and details of the decision, the grounds for the appeal and the facts the authority got wrong, the legal reasoning with references to law, the taxpayer's requests, whether the issuing office was notified and whether the decision is being challenged in court, an address for the reply and a list of attachments. Copies of documents must be duly certified. During the administrative appeal, the burden of proving that an assessment is lawful rests on the tax authority (Art. 56.4).
If a complaint was filed against your company
After a complaint by a third party, the tax authority sends a written request, and the company has 15 working days to answer with supporting documents (Art. 73.3.3). Without an answer, the authority gets grounds for an unscheduled documentary audit (Art. 78.1.1, 78.1.9). A request that breaches the requirements of paragraphs 1–5 of Art. 73.3 does not have to be answered (Art. 73.3.4). We check the request first and then prepare the reply.
What the service includes
- Review of the audit report, the tax notice-decision or the request, and a check of the assessment.
- Choosing between an administrative appeal and court.
- Objections to the audit report and the complaint text, with calculations and references to law.
- Selecting and certifying source documents and ledgers.
- Notifying the issuing office and taking part in the review, including by video conference.
How we work
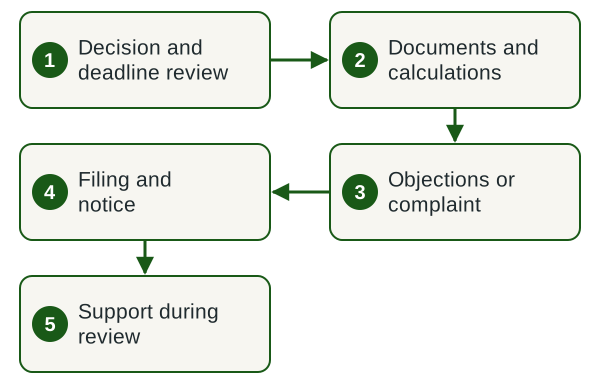
- Decision and deadline review We read the report and decision and fix the last filing day.
- Documents and calculations We gather source documents and explanations for each issue.
- Objections or complaint We draft the text with law references and attachments.
- Filing and notice We file the complaint and notify the issuing office.
- Support during review We attend the review and advise on the next step.
Timelines and cost
The Tax Code sets the pace: 10 working days for objections and for the complaint. We plan from the day you received the document, so the sooner you send it, the more time is left for evidence.
Pricing is individual, after we review your case: we look at the notice-decision and the documents, then confirm the scope of work and the fee in the contract.
What we need from you
- The audit report and any objections already filed.
- The tax notice-decision or request, with the date you received it.
- Contracts and source documents for the disputed transactions.
- A power of attorney for the review.
What you receive
- The objection or complaint with calculations and references to law.
- A certified set of supporting documents.
- Support during the review and advice on the authority's decision.
- If needed, a court strategy handed over to the group's lawyers at legal.ua.
Legal basis
Rules the work relies on
- Art. 56, 86.7 of the Tax Code of Ukraine — administrative and court appeals, objections to audit reports.
- Art. 73.3, 78.1.1, 78.1.9 of the Tax Code — tax authority requests and unscheduled audits based on complaints.
- Ministry of Finance Order No. 916 — form and filing of taxpayer complaints.
Risks, and why to hand this to a team under contract
A missed 10-day deadline makes the assessed amount final, and collection follows. Documents not provided during the audit or with the objections are treated as not having existed when the returns were prepared (Art. 44.6). Once a decision is challenged in court, the administrative route closes. We work under a contract that fixes scope, timing and liability; court representation goes to the group's lawyers at legal.ua.
Why Key Solutions
- Turnkey, with no extra hassle
- We take the whole task: documents, calculations, reporting and correspondence with the State Tax Service. You make the decisions, provide source documents and sign; we do the rest and contact you only when it matters.
- We take on the tax office
- Information requests, blocked tax invoices, inspection reports: we prepare explanations, rework documents and appeal until the issue is closed. Where the law is in dispute, we work together with the group's lawyers.
- We see it through
- Your case stays on track: the specialist running it remains with you, even if an inspection or audit drags on for months. Statutory audits are performed, and the report signed, by a partner audit firm entitled to perform them; we handle preparation and support through publication, so you deal with one team from start to finish.
- Boutique-level involvement
- A senior specialist runs your project personally (see the Our employees page), backed by 14 years of Innova group practice in 50+ countries. Non-standard tasks are our field: where you hear “it can’t be done”, we look for a lawful way, and group companies cover the rest: legal.ua for legal matters, crystal.tax for crypto-asset taxation.
- Your affairs stay yours
- Information about your company, turnover, payroll and counterparties reaches neither competitors nor third parties. We disclose only what the law or a procedure requires, and the contract says so.
- Faster and right the first time
- Full involvement: your specialist learns your books, contracts and business, so documents and reports are ready on time with no rework. The group's 14 years of experience let us get right the first time what takes some firms three attempts.
Frequently asked questions
How long do I have to appeal a tax notice-decision in Ukraine?
Ten working days after the day you receive it. If you miss the deadline, you can still file within six months together with a request to restore it and evidence of a valid reason. For decisions not related to a tax violation, the deadline is 30 calendar days.
Does a complaint suspend payment of the assessed tax?
Yes. A complaint filed on time suspends the obligation to pay the amounts in the tax notice-decision until the administrative appeal ends. During that period no tax demands are sent and the disputed amount is treated as not agreed.
What if the tax authority does not answer in time?
If the reasoned decision is not sent within 20 calendar days, or within the extended period of up to 60 days, the complaint is deemed fully upheld in the taxpayer's favour from the next day.
Where is a complaint about a tax decision filed?
With the higher-level tax authority; complaints about decisions of regional tax offices go to the State Tax Service of Ukraine. At the same time, the taxpayer must notify the office that issued the decision, in writing or electronically, that it is being appealed.
Can I go straight to court?
Yes. Taking the statute of limitations into account, a decision can be challenged in court at any time after it is received. A decision that has been challenged in court can no longer be appealed administratively, so the route has to be chosen at the start.
Can I file an anonymous complaint with the Ukrainian tax authority?
A written appeal without the author's name, address or signature is treated as anonymous and is not considered (Art. 8 of Law No. 393/96-VR on Citizens' Appeals). The author can instead ask that their name and address not be disclosed, and the authority must respect that request (Art. 10).
Related services
Discuss your complaint
Tell us which decision or request you received and when, the amount assessed and whether objections were filed. We will assess your position and deadlines and reply with the scope and fee.
Book a consultation Order the service +38 (068) 777-14-74 Telegram WhatsApp