


A fixed asset inventory in Ukraine is a check of the actual existence, condition and value of assets against the accounting records, required before the annual financial statements. Key Solutions drafts the order, sits on the commission and prepares count sheets, reconciliations and minutes under Regulation No. 879.
+38 (068) 777-14-74 Telegram WhatsApp
In short
- When it is needed: before the year-end statements, when the responsible person changes, after theft or fire, before moving to IFRS or selling the business, or on a tax authority demand.
- What you get: the order, count sheets, reconciliation statements, commission minutes and entries for surpluses and shortages with the VAT effect.
- Timing: in our experience it depends on the number of assets, sites and the state of the asset cards. We agree the site schedule before we start and put it in the contract.
- Cost: agreed individually, based on the number of assets and sites, the type of count and the state of records.
- How to start: send the trial balance for accounts 10 and 11 and the list of addresses where assets are kept. We reply with scope, team and fee.
When a fixed asset inventory is mandatory
Ukrainian companies must count assets and liabilities to keep the accounting data and financial statements reliable (Art. 10 of Law No. 996-XIV). Before the annual statements the count is mandatory (para. 12 of Procedure No. 419). The detailed rules are set by the Regulation on the Inventory of Assets and Liabilities, approved by Ministry of Finance Order No. 879 of 02.09.2014. It also covers branches and representative offices of foreign companies.
| Asset | Period before the balance sheet date |
|---|---|
| Fixed assets and other non-current assets | Three months (para. 10, Section I, Reg. 879) |
| Construction in progress | Two months |
| Land, buildings, other real estate | Once every three years, except state-owned real estate |
An unscheduled count is also required when the materially responsible person changes, when theft or damage is found, after an accident or fire, on liquidation, under a court decision and on the date of transition to IFRS. During a tax audit the tax authority may demand an inventory of fixed assets (subpara. 20.1.9 of the Tax Code).
What our fixed asset inventory service covers
- A draft director's order: assets, timing and members of the commission.
- A check of technical passports, title documents for real estate and land, lease, leasing and storage agreements.
- Inspection and count on site, including inventory and serial numbers and vehicle body, engine and chassis numbers.
- Count sheets by asset or group and separately for each materially responsible person, plus a separate list of unusable assets.
- Reconciliation statements and commission minutes with the reasons for differences and proposals to settle them.
- Entries for surpluses, shortages and disposals, VAT under para. 189.9 of the Tax Code and corrected asset cards.
How the work runs
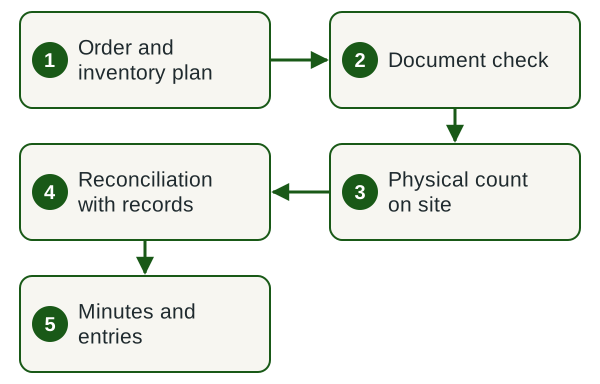
- Order and inventory plan Date, assets, sites and commission, set out in the director's order.
- Document check Asset cards matched with passports, title documents and leases.
- Physical count on site Each asset inspected with the responsible person present.
- Reconciliation with records Book data compared, every difference traced.
- Minutes and entries Minutes for the director and entries for the period of the count.
Timing and cost
In our experience, timing depends on three things: the number of assets, the number of sites and the condition of the asset cards. The director approves the commission minutes within 5 working days after the count ends (para. 2, Section IV of Regulation No. 879).
The fee is agreed individually: it depends on the number of assets and sites, missing documents, the type of count and VAT on disposals.
What we need from you
- The trial balance and asset cards for accounts 10 and 11 at the count date.
- The list of sites and the materially responsible person at each one.
- Technical passports, title documents, lease, leasing and storage agreements.
- Access to premises, sites and vehicles on the agreed days, with the responsible persons present.
- A contact person in accounting and the director's signature on the order and the minutes.
What you receive
- A signed order and an appointed commission.
- Count sheets signed by the commission and responsible persons, in at least two copies.
- Reconciliation statements and minutes with findings and proposals.
- Entries for surpluses, shortages and write-offs, with the VAT calculation.
- A list of unusable and idle assets for a write-off decision and a letter with recommendations.
Legal basis
Legal basis for the work
- Art. 10 of Law No. 996-XIV — the duty to count assets and liabilities.
- para. 12 of Procedure No. 419 — inventory before the annual statements.
- Regulation No. 879 (Ministry of Finance) — timing, commission, count sheets, minutes, surpluses and shortages.
- subparas. 20.1.9, 94.2.8 and para. 189.9 of the Tax Code — tax authority demand, arrest of property, VAT on disposal.
- Art. 164-2 of the Code of Administrative Offences — fine for a late or poor-quality inventory.
Why a contracted team is the safer choice
A count on paper without inspection gives the auditor grounds to modify the opinion. Key Solutions works under a contract with agreed scope, timing and liability, and our commission member is independent of the persons responsible for the assets.
Why Key Solutions
- Company
- ТОВ «АУДИТОРСЬКА ФІРМА «КЕЙ СОЛЮШНЗ», a Ukrainian limited liability company, EDRPOU code 39610085. The company's details are public in the Unified State Register (ЄДР).
- Contract
- We work under a contract: scope, timing, liability and confidentiality are agreed before work starts.
- Group
- Key Solutions is part of Innova Consulting Group: legal matters are handled by legal.ua, crypto-asset taxation by crystal.tax.
- Office
- Our office is at 77 Velyka Vasylkivska St., Kyiv. We serve clients across Ukraine remotely. The specialists who run engagements are listed on the Our employees page.
Frequently asked questions
How often must a company count its fixed assets in Ukraine?
At least once a year, before the annual financial statements, as required by para. 12 of Procedure No. 419 and para. 7, Section I of Regulation No. 879. Extra counts are required after a change of the responsible person, theft, fire, on liquidation and on transition to IFRS.
When is the annual count of fixed assets carried out?
Within three months before the balance sheet date for non-current assets and within two months for construction in progress (para. 10, Section I of Regulation No. 879). Vehicles and ships that will be away are counted before they leave.
Who sits on the inventory commission?
The director appoints it by order from management, accounting staff and employees who know the assets. Regulation No. 879 allows audit firm representatives to join, so Key Solutions specialists can sit on it.
What happens to surplus fixed assets found during the count?
Surplus fixed assets and intangible assets are recognised with an increase in deferred income (para. 4, Section IV of Regulation No. 879). Assets that were never recorded are measured at fair value.
What is the penalty for not carrying out an inventory?
Art. 164-2 of the Code of Administrative Offences sets a fine of 8 to 15 non-taxable minimum incomes of citizens (UAH 136–255), and 10 to 20 (UAH 170–340) for a repeat offence within a year. Refusing a count demanded by the tax authority is a ground for administrative arrest of property (subpara. 94.2.8 of the Tax Code).
How much does a fixed asset inventory cost?
The fee is agreed individually and depends on the number of assets and sites, the state of the records and the type of count. We quote after reviewing your fixed asset trial balance and list of locations.
Related services
Order a fixed asset inventory
Tell us the balance sheet date or the event (year-end, change of responsible person, accident, tax audit) and the number of sites. We will send an inventory plan, the team and the fee.
Book a consultation Order the service +38 (068) 777-14-74 Telegram WhatsApp