


Foreign company reporting is the annual financial and tax reporting of a company registered abroad, required by its jurisdiction, its bank or the Ukrainian tax authority for a CFC. Key Solutions keeps the books, prepares IFRS financial statements and tracks filing deadlines.
Telegram WhatsApp
In short
- Who needs it: midshore and onshore companies (Cyprus, UK, Hong Kong), classic offshore companies at a bank's or agent's request, CFCs of Ukrainian owners.
- What you get: IFRS or local GAAP accounts, nil accounts for dormant companies, a pack for the auditor and the CFC report.
- Timing: in our experience, 10–20 days after we receive the documents.
- Fee: agreed individually, based on the jurisdiction, volume and state of records.
- How to start: send the country, financial year, deadline and whether there is a Ukrainian controlling person.
What a foreign company files
The country of incorporation sets the content and deadlines: midshore and onshore jurisdictions require filings with the registry and tax authority, while classic offshore ones usually require records to be kept.
| Jurisdiction | Filing | Source |
|---|---|---|
| United Kingdom | Accounts to Companies House within 9 months of period end; UK company accounting and reporting | s. 442 Companies Act 2006 |
| Cyprus | IFRS accounts with audit or review, tax return | Companies Law, Cap. 113 |
| Hong Kong | Audited accounts with the profits tax return | s. 405 Cap. 622 |
| Czechia (s.r.o.) | Účetní závěrka filed with the sbírka listin within 12 months of the balance sheet date, corporate income tax and VAT returns; Czech s.r.o. accounting and reporting | § 21a, Act 563/1991 Coll. |
| Poland (sp. z o.o.) | Financial statements filed with the KRS within 15 days of approval (approval within 6 months of the balance sheet date), CIT-8, JPK_V7, CRBR; Polish sp. z o.o. accounting and reporting | Arts. 53 and 69, Accounting Act |
| Spain (SL) | Annual accounts deposited with the Registro Mercantil within one month of approval (approval within 6 months of the year end) with the beneficial ownership sheet, quarterly IVA and withholding, corporate tax return in July; Spanish SL accounting and reporting | Arts. 164 and 279, Capital Companies Act |
| Portugal (Lda) | Annual accounts submitted for approval within 3 months of the year end, Modelo 22 by the end of May, IES by 15 July, monthly or quarterly IVA, yearly RCBE beneficial ownership confirmation by 31 December; Portuguese Lda accounting and reporting | Art. 65, CSC; Arts. 120–121, CIRC |
| Cyprus (Ltd) | IFRS financial statements with an audit or review (turnover up to €300,000 and assets up to €500,000 for two consecutive years), annual return within 28 days of its made-up date, provisional tax on 31 July and 31 December, T.D.4; Cyprus company accounting and reporting | s. 152, Cap. 113; s. 5, Law 4/1978 |
| Germany (GmbH) | HGB annual accounts within 3 months (small companies up to 6), publication in the Unternehmensregister within 12 months, audit for medium-sized and large companies, advance VAT returns by the 10th, Transparenzregister; German GmbH accounting and reporting | § 264, 316, 325 HGB; § 18 UStG |
| Estonia (OÜ) | Annual report to the e-Business Register within 6 months, TSD by the 10th and KMD by the 20th, 22/78 tax on distributed profit, audit or review above the statutory limits; Estonian OÜ accounting and reporting | rik.ee; emta.ee; § 91–92 AudS |
| USA (LLC, corporation) | Foreign-owned LLC: Form 5472 with pro forma Form 1120 by the 15th day of the 4th month, fax or mail only; corporation: Form 1120 and 21% tax; state annual report or annual tax; US company accounting and reporting | irs.gov; corp.delaware.gov; fincen.gov |
| Canada (corporation) | T2 within 6 months of year end, GST/HST once sales exceed $30,000, payroll and T4, NR4, annual return and ISC information; Canadian corporation accounting and reporting | canada.ca; Corporations Canada |
| UAE (mainland, free zone) | Corporate Tax registration and return within 9 months of year end (0% up to AED 375,000, 9% above; a QFZP pays 0% only on qualifying income and must be audited), 5% VAT from AED 375,000 of supplies; UAE company accounting and reporting | mof.gov.ae; tax.gov.ae |
| Singapore (Pte Ltd) | ACRA annual return within 7 months with XBRL statements, ECI within 3 months, Form C-S or C by 30 November, 17% tax, 9% GST from S$1 million turnover; Singapore company accounting and reporting | acra.gov.sg; iras.gov.sg |
| BVI, Seychelles, Panama | Records and accounts on request of agent, bank or tax office | local law |
CFC accounts under the Ukrainian Tax Code
A Ukrainian resident holding over 50 %, or over 10 % where Ukrainian residents together hold 50 % or more, or exercising actual control, is a controlling person (subpara. 39-2.1.2). Certified copies of the CFC's financial statements are attached to the annual CFC report (subpara. 39-2.5.2), so CFC accounts are needed every year. Profit is exempt if total income of all the owner's CFCs does not exceed EUR 2 million (subpara. 39-2.4.2.1), but the report is still filed. We prepare the accounts; the CFC report and tax calculation are handled by our group company crystal.tax.
What the service includes
- review of local requirements: content, standards, deadlines and who files;
- bookkeeping from bank statements, invoices and contracts;
- IFRS or local GAAP accounts, including nil accounts, and local tax returns with the agent;
- an audit file where the jurisdiction or bank requires an audit;
- CFC accounts pack and adjusted profit calculation for the Ukrainian owner.
How we work
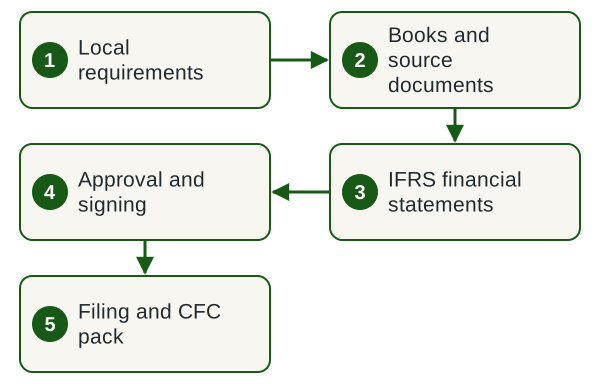
- Local requirements. Content, standards and deadlines for your jurisdiction.
- Books and source documents. Statements, invoices and contracts; books for the year.
- IFRS financial statements. Accounts and notes reconciled to the bank.
- Approval and signing. Figures agreed with the owner, approved by the director.
- Filing and CFC pack. Filing via the agent or tax office, copies for the CFC report.
Timing and fees
In our experience, preparing the accounts takes 10–20 days after we receive a complete set of documents. An individual files the CFC report with the annual return by 1 May (subpara. 49.18.4 of the Tax Code), so CFC accounts are best prepared in the first quarter. The fee is agreed individually and depends on the jurisdiction, framework, transactions, accounts and currencies, and any audit.
What we need from you
- country of incorporation, constitutional documents and registered agent details;
- bank statements for the year for all accounts;
- invoices, contracts and payment confirmations;
- ownership details for the CFC report.
Deliverables
- financial statements under IFRS or local rules, approved by the director;
- local tax returns filed on time;
- certified copies and adjusted profit calculation for the CFC report;
- a filing calendar for the next year.
Legal basis
Legal basis for the work
- Subparas 39-2.1.2, 39-2.3.1, 39-2.4.2.1, 39-2.5.2 of the Tax Code of Ukraine: CFC control, accounts, exemption and reporting;
- Para. 120.7 of the Tax Code: fines of 100 subsistence minimums for an unfiled CFC report and up to 1,000 for omissions;
- Ss. 442 and 477 Companies Act 2006: UK filing deadline and small company audit exemption.
Why Key Solutions
- Company
- ТОВ «АУДИТОРСЬКА ФІРМА «КЕЙ СОЛЮШНЗ», a Ukrainian limited liability company, EDRPOU code 39610085. The company's details are public in the Unified State Register (ЄДР).
- Contract
- We work under a contract: scope, timing, liability and confidentiality are agreed before work starts.
- Group
- Key Solutions is part of Innova Consulting Group: legal matters are handled by legal.ua, crypto-asset taxation by crystal.tax.
- Office
- Our office is at 77 Velyka Vasylkivska St., Kyiv. We serve clients across Ukraine remotely. The specialists who run engagements are listed on the Our employees page.
Frequently asked questions
Does a dormant foreign company need accounts?
In most midshore and onshore jurisdictions, yes: nil accounts are filed for a year without transactions. For a CFC of a Ukrainian owner, accounts are needed even where the jurisdiction does not require them, and they are then prepared under IFRS (subpara. 39-2.3.1 of the Tax Code).
Which standards apply to CFC accounts?
CFC profit is based on the company's standalone financial statements under the standards it applies. If the jurisdiction requires none, the controlling person must have IFRS accounts prepared (subpara. 39-2.3.1). Foreign currency profit is translated into hryvnia at the NBU weighted average rate for the year (subpara. 39-2.3.4).
What if CFC accounts are not ready by the tax return deadline?
The controlling person files a short-form CFC report with company and ownership details (subpara. 39-2.5.4). The full report follows by the end of the next calendar year, with an amended return if tax increases, without penalties or late-payment interest.
What does a UK company file?
A private company files annual accounts with Companies House within nine months of the period end (s. 442 Companies Act 2006). Small companies may be exempt from audit (s. 477). The tax return goes to HMRC separately.
Do CFC documents need a Ukrainian translation?
English is accepted: for a Ukrainian tax audit, copies of CFC source documents in English are filed without translation (subpara. 39-2.6.4.3 of the Tax Code). We prepare the accounts and ledgers in English and explanations in Ukrainian.
How much does foreign company reporting cost?
The fee is agreed individually and depends on the jurisdiction, reporting framework, volume of transactions, state of records and any audit. We quote after a short description of the company and fix the fee in the contract.
Related services
Let's discuss your company's reporting
Send us the country of incorporation, financial year, deadline and whether you need a CFC pack. We will reply with the scope, timing and fee.
Book a consultation Order the service Telegram WhatsApp