


A mandatory (statutory) audit of financial statements is an audit that Ukrainian law requires of companies that must publish or submit their statements together with an audit report. Key Solutions in Kyiv prepares your books and statements, arranges the audit with a partner audit firm authorised to perform mandatory audits, and supports the company through publication.
+38 (068) 777-14-74 Telegram WhatsApp
In short
- Who needs it: medium and large companies, public joint-stock companies, financial institutions, natural monopolies, extractive companies and the other groups in Art. 14(3) of Law No. 996-XIV.
- Who does what: a partner audit firm from the Register performs the audit and signs the report; Key Solutions prepares the books and statements, organises the audit and supports publication.
- Timing: preparation should start in the fourth quarter of the reporting year, before the year-end inventory count, to meet your group's publication deadline.
- Cost: agreed individually, based on transaction volume, the state of the records, the reporting framework and the time left before the deadline. We quote after reviewing the statements.
- Where to start: send us last year's balance sheet and income statement and your average headcount.
Which companies need a mandatory audit in Ukraine in 2026
A mandatory audit applies to companies that, under Art. 14(3) of Law No. 996-XIV, must publish their annual financial statements together with the audit report on their own website. The duty depends on the company's size category and its type of business.
Who publishes statements with an audit report, and by when
| Group | Publication deadline | Rule |
|---|---|---|
| Public-interest entities (except large non-issuers), public JSCs, natural monopolies on the national market, extractive companies | by 30 April | Art. 14(3), para 1 |
| Large companies that are not issuers, and medium-sized companies | by 1 June | Art. 14(3), para 2 |
| Financial institutions and non-state pension funds that are micro or small | by 1 June | Art. 14(3), para 3 |
| Small state-sector companies, where the law requires an audit | by 1 June | Art. 14(3), para 4 |
| Parent companies of a large group | by 1 June | Art. 14(3), para 6 |
Deadlines fall in the year after the reporting year. Published statements with the audit report stay on the company website for at least six years (Art. 14(7) of Law No. 996-XIV).
Most often the duty arises when a company becomes medium-sized. That happens when it exceeds the small-company limits on two of three measures: total assets above EUR 4 million, net revenue above EUR 8 million, average headcount above 50 (Art. 2(2) of Law No. 996-XIV). The figures come from the annual statements for the year before the reporting year, and the category changes once the criteria are not met for two years in a row. All criteria and exceptions are covered in our article who needs a mandatory audit in Ukraine.
Note. Law No. 996-XIV applies to legal entities and to branches and representative offices of foreign companies (Art. 2(1)), so individual entrepreneurs (FOPs) have no audit duty under it. A small company outside the table may still need an audit report for a bank or investor; for that, a voluntary audit of financial statements fits.
How we organise a mandatory audit: who is responsible for what
The mandatory audit is performed, and the audit report signed, by a partner audit firm entered in the relevant section of the Register of Auditors and Audit Entities for firms authorised to perform mandatory audits. Key Solutions organises the work, prepares the books and financial statements, and supports the company through publication.
You deal with one team for the whole cycle, from the assessment of your duty to the audited statements on your website.
Roles in a mandatory audit
| Party | What it does | Basis |
|---|---|---|
| Your company | The governing body appoints the auditor; the company approves and publishes the statements | Art. 29(1), Law No. 2258-VIII |
| Partner audit firm | Performs the audit under ISA, forms an opinion and signs the audit report | Arts 6(1), 21(1), Law No. 2258-VIII |
| Key Solutions | Prepares books and statements, proposes the partner, organises the audit and publication | our contract with you |
The auditor is appointed by the general meeting of participants or shareholders, by the supervisory board where the law provides, or by another supreme body (Art. 29(1) of Law No. 2258-VIII). We propose the partner firm and help prepare the appointment resolution. A firm performing mandatory audits must hold third-party liability insurance (Art. 43(2) of the same Law). Public-interest entities select their auditor through a tender among firms in section 4 of the Register (Arts 29(3) and 21(1) of the same Law).
What the service includes
- A written assessment: whether the company is subject to a mandatory audit, which group it falls into, and its publication deadline.
- Selection of a partner audit firm from the relevant section of the Register and an agreed audit timetable.
- Getting the books ready: reconciling the trial balance with source documents, reviewing the accounting policy, correcting errors; where gaps are serious, restoration of accounting records.
- Organising the year-end inventory count of assets and liabilities and balance confirmations with counterparties.
- Preparing the annual financial statements under national standards or IFRS, and the management report where the law requires one.
- A document pack and account analyses for the auditor, and answers to the auditor's requests during fieldwork.
- Preparing the statements with the audit report for publication on the company website and for filing with the State Tax Service.
How we work
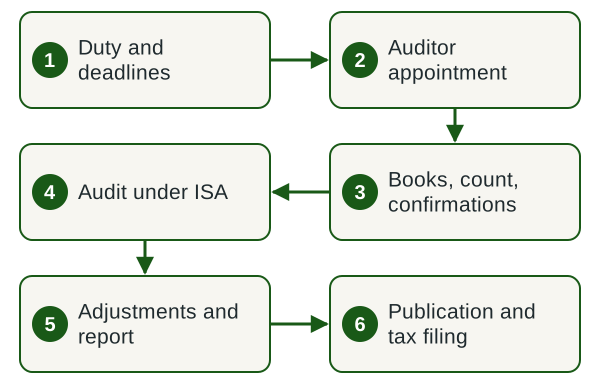
- Duty and deadlines From last year's statements we set the size category, the Art. 14(3) group and the publication deadline.
- Auditor appointment We propose a partner firm from the Register; your governing body resolves to appoint it.
- Books, count, confirmations We reconcile the books with source documents, correct errors and organise the year-end count.
- Audit under ISA The partner firm audits the statements; we provide documents and answer the auditor's requests.
- Adjustments and report We post the agreed corrections; the auditor forms an opinion and signs the report.
- Publication and tax filing We prepare the pack for your website and the annual statements for the tax service on time.
Timing
In our experience, it makes sense to start preparation in the fourth quarter of the reporting year. The auditor is engaged before the year-end count: where inventories are material, the auditor attends the count unless that is impracticable (ISA 501, para 4).
The audit itself, in our experience, takes a few weeks from receipt of the full document pack. Timing depends on transaction volume, the state of source documents, whether there is a group, and how quickly counterparties return confirmations.
What affects the cost
The fee for the mandatory audit and preparation is agreed individually. The state sets no tariffs; we fix the amount in the contract after reviewing the statements. It depends on:
- transaction volume, the number of accounts and group companies;
- the state of the records: whether corrections or restoration are needed;
- the reporting framework: national standards or IFRS, consolidated statements;
- first-year audit or recurring engagement;
- the number of warehouses and sites for the inventory count;
- the time left before the publication deadline.
Market benchmarks for audit fees are collected in our article how much a financial statement audit costs.
What we need from you
- Last year's balance sheet and income statement, and the average headcount.
- View-only access to the accounting system (BAS or other).
- The accounting policy order, the trial balance, key contracts and bank statements.
- The charter, to identify the body that appoints the auditor.
- Previous audit reports and management letters, if any.
- A contact person who answers questions from the auditor and our team promptly.
Result
- A written assessment of the audit duty, group and publication deadline.
- Corrected books and annual financial statements.
- An audit report of the partner audit firm, prepared under ISA.
- A pack for publication on the company website and the annual statements for the tax service.
- The auditor's findings with a correction plan for the next year.
Get a quote for your mandatory audit
Send last year's balance sheet and tell us your line of business. We will reply with the scope, timing and fee.
Fines for non-publication, and filing with the tax service
Breaching the rules for publishing financial statements with the audit report carries a fine of 1,000–2,000 non-taxable minimum incomes of citizens (UAH 17,000–34,000), and UAH 34,000–51,000 (2,000–3,000 minimums) for a repeat breach within a year (Art. 163-16 of the Code of Administrative Offences). During martial law and for three months after it ends, missed publication deadlines carry no fine (Law No. 2115-IX, cl. 1(4-1)), except for state unitary enterprises and companies more than 50% owned by the state directly or through a state company.
Statements for the whole missed period are published within three months after martial law ends (Law No. 2115-IX, cl. 1(4-2)).
Corporate income tax payers in these groups must file with the State Tax Service, by 10 June, the annual statements that are published with the audit report (Tax Code of Ukraine, cl. 46.2, para 4). Late or missing filing is fined UAH 340, or UAH 1,020 for a repeat within a year (Tax Code, cl. 120.1), and while martial law lasts, cl. 69.1 of subsection 10, section XX of the Tax Code releases the company from liability for not filing these statements, provided it files within three months after martial law ends.
Legal framework
Rules the work relies on
- Law No. 2258-VIII On Audit of Financial Statements and Auditing Activity, Arts 1(1)(16), 6(1), 21(1), 29(1), 29(3), 43(2) — mandatory audit, the Register, auditor appointment, liability insurance.
- Law No. 996-XIV On Accounting and Financial Reporting, Arts 2(1), 2(2), 14(3), 14(7) — scope, size categories, publication deadlines and retention.
- Code of Ukraine on Administrative Offences, Art. 163-16 — liability for breaching publication rules.
- Law No. 2115-IX, cl. 1(4-1), 1(4-2) — publication during martial law.
- Tax Code of Ukraine, cl. 46.2, 120.1, and cl. 69.1 of subsection 10, section XX — filing with the tax service and liability.
- ISA 501, para 4 — auditor attendance at the inventory count.
Risks, and why to hand a mandatory audit to a team under contract
Material misstatements the company has not corrected by the end of the audit lead to a modified opinion: qualified or adverse. If the auditor cannot obtain sufficient evidence, for example because of an incomplete inventory count, the opinion is modified too, up to a disclaimer. That report is published and seen by banks, counterparties and the tax authority.
Common causes are an incomplete count, unreconciled receivables, inconsistencies in the accounting policy and a late auditor appointment. We run the preparation and audit organisation under a contract: scope, timing and liability are agreed before work starts, and legal matters are handled by the group's lawyers. Advice from a chatbot or a one-off freelancer carries no liability for the publication deadline.
Why Key Solutions
- Company
- ТОВ «АУДИТОРСЬКА ФІРМА «КЕЙ СОЛЮШНЗ», a Ukrainian limited liability company, EDRPOU code 39610085. The company's details are public in the Unified State Register (ЄДР).
- Contract
- We work under a contract: scope, timing, liability and confidentiality are agreed before work starts.
- Group
- Key Solutions is part of Innova Consulting Group: legal matters are handled by legal.ua, crypto-asset taxation by crystal.tax.
- Office
- Our office is at 77 Velyka Vasylkivska St., Kyiv. We serve clients across Ukraine remotely. The specialists who run engagements are listed on the Our employees page.
Frequently asked questions
Which companies must have a mandatory audit in Ukraine?
A mandatory audit is required for companies that publish annual statements with an audit report under Art. 14(3) of Law No. 996-XIV: public-interest entities, public joint-stock companies, large and medium-sized companies, natural monopolies on the national market, extractive companies, micro and small financial institutions and pension funds, small state-sector companies where the law requires an audit, and parent companies of large groups.
Who performs a mandatory audit and signs the audit report?
The mandatory audit is performed, and the report signed, by a partner audit firm entered in the relevant section of the Register of Auditors and Audit Entities for firms authorised to perform mandatory audits (Art. 6(1) of Law No. 2258-VIII). Key Solutions organises the work, prepares the books and statements and supports the company through publication. The auditor is appointed by your governing body: the general meeting or the supervisory board.
How much does a mandatory audit cost?
The fee is agreed individually. It depends on transaction volume, the state of the records, the reporting framework (national standards or IFRS), whether there is a group, whether it is the first audited year, and the time left before the publication deadline. We quote after reviewing last year's balance sheet and income statement and fix the amount in the contract.
Does an LLC need a mandatory audit?
For an LLC the duty depends on its size category and type of business. An LLC is audited if under Art. 2(2) of Law No. 996-XIV it is medium or large, or if it is a financial institution, a natural monopoly on the national market or an extractive company (Art. 14(3)). A small LLC outside these groups orders an audit at the owners' decision or at a bank's or investor's request.
When is the mandatory audit carried out, and when must statements be published?
The audit of the annual statements takes place after year-end so that the publication deadline can be met: 30 April for public-interest entities, public joint-stock companies, natural monopolies and extractive companies, and 1 June for the other groups (Art. 14(3) of Law No. 996-XIV). Preparation of the books usually starts in the fourth quarter, before the year-end count.
What happens if the statements are not published with the audit report?
Art. 163-16 of the Code of Administrative Offences provides for a fine; the amounts and the martial-law relief are given in the section on fines. Statements for the missed period are published within three months after martial law ends (Law No. 2115-IX, cl. 1(4-2)), and they need an audit report as well.
Can a company pass a mandatory audit if its books contain errors?
Yes, errors are corrected before the audit is completed. We reconcile the books with source documents, prepare a list of corrections with journal entries, and restore the records where gaps are serious. Uncorrected material misstatements lead to a modified audit opinion, so preparation should start before year-end.
What is the difference between a mandatory and a voluntary audit?
A mandatory audit is required by law, performed by a firm from section 3 or 4 of the Register, and published with the statements. A voluntary audit is ordered by owners, a bank, an investor or a buyer, and the report goes to the client. Both follow ISA.
Related services
Let's discuss your mandatory audit
Tell us your line of business and attach last year's balance sheet and income statement. We will tell you whether the company is subject to a mandatory audit and propose a plan with timing and fees.
Book a consultation Order the service +38 (068) 777-14-74 Telegram WhatsApp