Transfer pricing in Ukraine is the set of rules in Article 39 of the Tax Code of Ukraine (ПКУ) that requires transactions with related non-residents and other controlled counterparties to meet the arm's length principle. Key Solutions identifies controlled transactions, prepares the report and TP file, and handles tax authority requests.
+38 (068) 777-14-74 Telegram WhatsApp
In short
- When you need it: your Ukrainian company deals with related non-residents, counterparties on the Cabinet of Ministers lists or a non-resident's permanent establishment above the thresholds of subpara. 39.2.1.7 of the Tax Code.
- What you get: a list of controlled transactions, the controlled transactions report, the notice of participation in a multinational enterprise group (MNE group) and a local file supporting each price.
- Timing: set after a diagnostic and fixed in the contract; it depends on the number of transactions and how ready your data is.
- Cost: depends on the number and type of controlled transactions, the method and whether a benchmarking study is needed.
- Where to start: send a list of non-resident counterparties with annual turnover for each.
What transfer pricing covers in Ukraine
Transfer pricing rules set the taxable value of transactions between related and equivalent parties: their terms must match what unrelated parties would agree in comparable circumstances. The rules sit in Article 39 of the Tax Code and are enforced by the State Tax Service of Ukraine (ДПС). The three-tier documentation structure came with Law No. 466-IX of 16.01.2020, and we check the version of Article 39 in force every year.
Controlled transactions report: who files and by when
Companies that carried out controlled transactions in a year file the controlled transactions report by 1 October of the following year, so the 2025 report is due by 1 October 2026 (subpara. 39.4.2 of the Tax Code). A transaction is controlled when both value thresholds in the table are met.
| Criterion | Condition | Rule |
|---|---|---|
| Taxpayer's annual income | over UAH 150 million, net of indirect taxes | Tax Code, subpara. 39.2.1.7 |
| Transactions with each counterparty | over UAH 10 million a year, net of indirect taxes | Tax Code, subpara. 39.2.1.7 |
| Non-resident and its permanent establishment | income test is disregarded; the UAH 10 million test is enough | Tax Code, subpara. 39.2.1.7 |
| Local file (TP documentation) | 30 calendar days from a tax authority request | Tax Code, subpara. 39.4.4 |
Values for these thresholds are measured at arm's length prices (subpara. 39.2.1.9). Errors found after the deadline are corrected with an amended report, which does not release the company from penalties under paras 120.4 and 120.6. An amended report cannot be filed while a documentary tax audit of that period is under way (subpara. 39.4.2.1).
Which transactions are controlled
Subparas. 39.2.1.1 and 39.2.1.5 of the Tax Code define controlled transactions. In practice they are transactions:
- with related non-residents;
- through non-resident commission agents;
- through intermediaries with no significant functions or risks in the chain (subpara. 39.2.1.5);
- with non-residents from states on the list of Cabinet of Ministers Resolution No. 1045, which Resolution No. 1505 of 27.12.2024 cut from 78 to 46 jurisdictions from 1 January 2025;
- with non-residents whose legal form is on the list of Cabinet of Ministers Resolution No. 480;
- between a non-resident and its permanent establishment in Ukraine.
The UAE, Ireland and Moldova are among the jurisdictions removed from list No. 1045. The tax authority applies the new list from 1 January 2025, while subpara. 39.2.1.2 gives changes approved after 30 November effect from the second year, so we check 2025 transactions against both versions.
What our transfer pricing services include
- Diagnostic: which transactions are controlled, with checks on each counterparty's relationship to you, jurisdiction and legal form.
- Functional analysis: the functions, assets and risks of each party.
- Choice among the five methods of subpara. 39.3.1, a search for comparables and the arm's length range of prices or margins.
- The controlled transactions report and the MNE group participation notice.
- The local file; the master file on a tax authority request; advice on the country-by-country report.
- Replies to tax authority requests and objections to audit reports; court disputes together with the lawyers of legal.ua.
How we work
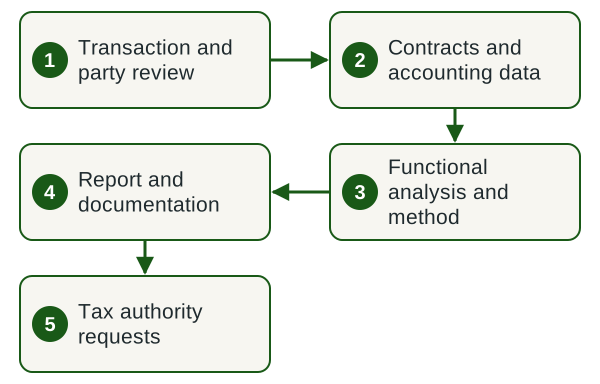
- Transaction and party review We check counterparties against Article 39 and the lists and identify the year's controlled transactions.
- Contracts and accounting data We collect contracts, invoices, payment documents and ledgers for each transaction.
- Functional analysis and method We describe functions, assets and risks, choose the method and comparables and calculate the range.
- Report and documentation We complete the report and the group notice and prepare the local file.
- Tax authority requests We draft replies and objections and recommend prices for the next year.
Timing
Timing depends on the number of transactions and counterparties, whether a benchmarking study is needed and how quickly contracts and data arrive. We fix the schedule in the contract after the diagnostic, around the official deadlines above. If the deadline has passed, we file the report first: the late-filing penalty of 1 SM a day, up to 300 SM, accrues for every calendar day (para. 120.6 of the Tax Code).
What drives the cost
- Number of controlled transactions and non-resident counterparties.
- Type of transactions: goods, services, royalties, loans, commodities with exchange quotations.
- Transfer pricing method and whether a benchmarking study is needed.
- Package contents: report, group participation notice, local file, master file.
- State of source documents and whether documentation exists for earlier years.
- An open tax authority request or transfer pricing audit.
What we need from you
- A list of non-resident counterparties and the turnover with each for the reporting year.
- Contracts, invoices and payment documents for controlled transactions, the year's financial statements and ledgers.
- Ownership structure: shareholders with 25% or more, subsidiaries and ultimate beneficial owners (subpara. 39.4.6 of the Tax Code).
- Each party's functions: who manufactures, who sells, who bears inventory, credit and currency risk.
- A contact person in accounting or finance who can answer questions quickly.
What you receive
- A conclusion on the year's controlled transactions.
- The controlled transactions report and, where needed, the group participation notice.
- A local file with the functional analysis and the reasoning behind the method and the price or margin range.
- Recommendations on prices and contract terms for the next year and, where needed, on a self-adjustment (subpara. 39.5.4 of the Tax Code).
- Replies to tax authority requests.
Get a quote for transfer pricing work
Send the list of non-resident counterparties and the annual turnover with each. We will reply with the scope, timing and price.
Transfer pricing penalties
Penalties are set in subsistence minimums for able-bodied persons (SM) as of 1 January of the tax year: UAH 3,328 in 2026 (Art. 7 of Law No. 4695-IX), so 300 SM equals UAH 998,400.
Important. Under martial law, a company is released from these penalties only if it had no way to meet the obligation on time and files the documents within six months after martial law ends (subpara. 69.1, subsection 10, section XX of the Tax Code).
| Breach | Penalty | Rule |
|---|---|---|
| Controlled transactions report not filed | 300 SM; if the report is still not filed 30 days after the deadline for paying that penalty, a further 5 SM a day, up to 300 SM | Tax Code, para. 120.3 |
| Controlled transactions left out of the report | 1% of the undeclared amount, up to 300 SM | Tax Code, para. 120.4 |
| Local file not submitted | 3% of the transaction amount, up to 200 SM; late: 2 SM a day, up to 200 SM | Tax Code, paras 120.3, 120.6 |
| Master file, CbC report, group notice not filed | 300 SM, 1,000 SM and 100 SM respectively | Tax Code, para. 120.3 |
Paying a penalty leaves the filing obligation in place (para. 120.3 of the Tax Code).
Legal framework
Rules the work relies on
- subparas. 39.2.1.1, 39.2.1.5, 39.2.1.7 of the Tax Code — which transactions are controlled and the value thresholds.
- subparas. 39.4.2–39.4.11 of the Tax Code — report, group participation notice, local file, master file, country-by-country report.
- paras 120.3–120.6 of the Tax Code — penalties for transfer pricing reporting breaches.
- subpara. 69.1, subsection 10, section XX of the Tax Code — release from liability under martial law.
- Cabinet of Ministers Resolutions No. 1045 and No. 480 — lists of jurisdictions and legal forms.
Risks and why to hand this to a team under contract
Transfer pricing errors cost more than the report. Typical ones: a counterparty from a Cabinet of Ministers list is missed, an outdated jurisdiction list is used, or the method has no comparables behind it. The result is penalties under Article 120 and additional corporate income tax after an audit (subpara. 39.5.2.15 of the Tax Code).
Key Solutions works under a contract that fixes scope, timing and liability; the group's lawyers take court disputes. A template or a chatbot answer ignores the functions and risks of your group, and those are what the tax authority examines first.
Why Key Solutions
- Turnkey, with no extra hassle
- We take the whole task: documents, calculations, reporting and correspondence with the State Tax Service. You make the decisions, provide source documents and sign; we do the rest and contact you only when it matters.
- We take on the tax office
- Information requests, blocked tax invoices, inspection reports: we prepare explanations, rework documents and appeal until the issue is closed. Where the law is in dispute, we work together with the group's lawyers.
- We see it through
- Your case stays on track: the specialist running it remains with you, even if an inspection or audit drags on for months. Statutory audits are performed, and the report signed, by a partner audit firm entitled to perform them; we handle preparation and support through publication, so you deal with one team from start to finish.
- Boutique-level involvement
- A senior specialist runs your project personally (see the Our employees page), backed by 14 years of Innova group practice in 50+ countries. Non-standard tasks are our field: where you hear “it can’t be done”, we look for a lawful way, and group companies cover the rest: legal.ua for legal matters, crystal.tax for crypto-asset taxation.
- Your affairs stay yours
- Information about your company, turnover, payroll and counterparties reaches neither competitors nor third parties. We disclose only what the law or a procedure requires, and the contract says so.
- Faster and right the first time
- Full involvement: your specialist learns your books, contracts and business, so documents and reports are ready on time with no rework. The group's 14 years of experience let us get right the first time what takes some firms three attempts.
Frequently asked questions
Which transactions are controlled in Ukraine in 2026?
Transactions with related non-residents, non-resident commission agents and counterparties on the Cabinet of Ministers lists are controlled when the taxpayer's annual income exceeds UAH 150 million and transactions with one counterparty exceed UAH 10 million, both net of indirect taxes (subpara. 39.2.1.7 of the Tax Code). For a permanent establishment, the second test is enough.
When is the 2025 controlled transactions report due?
The controlled transactions report for 2025 is filed electronically by 1 October 2026 (subpara. 39.4.2 of the Tax Code). By the same date, members of a multinational group that had controlled transactions file the notice of participation in the group.
What is the penalty for not filing the controlled transactions report?
The penalty is 300 subsistence minimums for able-bodied persons as of 1 January of the tax year, which is UAH 998,400 in 2026 (para. 120.3 of the Tax Code). Late filing is penalised for each calendar day of delay (para. 120.6).
Who files a master file and a country-by-country report?
Members of a multinational group with consolidated revenue of at least EUR 50 million equivalent file a master file within 90 calendar days of a tax authority request (subpara. 39.4.7 of the Tax Code). For groups with EUR 750 million equivalent or more, a country-by-country report is due within 12 months after the financial year ends (subparas. 39.4.10, 39.4.11).
Does a company without controlled transactions need to file transfer pricing reports?
A company whose dealings with non-residents fall outside the criteria of Article 39 of the Tax Code files neither the report nor the group notice (subpara. 39.4.2). Counterparty status is worth checking every year, because lists No. 1045 and No. 480 change.
How much do transfer pricing services cost?
We quote after the transaction diagnostic. The price depends on the number and type of controlled transactions, the method, whether a benchmarking study is needed, the documents in the package and any open tax authority request. Scope and price are fixed in the contract before work starts.
Related services
Discuss your controlled transactions
Tell us which non-residents your company deals with, the annual turnover with each and whether the tax authority has sent a request. We will reply with the transactions under control, a work plan, timing and price.
Book a consultation Order the service +38 (068) 777-14-74 Telegram WhatsApp