


An accounting review (financial inspection) is a documentary check of a company's books, reporting, settlements and physical assets, ordered by the owner or management. Key Solutions reviews the books independently of your accounting team and delivers findings, their impact and a correction plan.
+38 (068) 777-14-74 Telegram WhatsApp
In short
- When: a new chief accountant or CEO, doubts about the numbers, a coming tax audit, a share sale or a new investor.
- You get: a report of discrepancies, their impact and a correction plan with owners and deadlines.
- Timing: in our experience, 2–4 weeks for one company and one financial year, counted from receipt of the documents.
- Fee: agreed case by case, based on scope, period, transaction volume and the state of the records.
- Start: tell us what worries you, which period to cover and who will use the result.
Accounting review versus audit
In a review, the owner sets the scope: the whole ledger for a period or selected areas. The report lists facts, discrepancies and a correction plan without an audit opinion, so it suits the owner's internal decisions.
| Format | What you get | When to choose |
|---|---|---|
| Accounting review for the owner | Findings and a correction plan | New accountant, selected areas, doubts |
| Review of statements, ISRE 2400 | Limited assurance conclusion | Reporting to a partner or bank |
| Voluntary audit, ISA | Audit report with an opinion | Investor, business sale, loan |
Reviews and audits are audit services under Law No. 2258-VIII, which only firms entered in the Register may provide (Part 1 of Art. 20). These reports are signed by a partner audit firm, while Key Solutions organises the work and prepares the books. For a full audit, see financial statement audit; for limited assurance, see review audits.
What the review covers
| Area | What we check | Rule |
|---|---|---|
| Financial | Source documents, ledgers, balance sheet, income statement | Arts. 9, 11, Law No. 996-XIV |
| Tax | Returns against ledgers and documents, reassessment risks | Para 44.1, Tax Code |
| Cash | Cash desk, bank accounts, employee advances | Section III, item 6, Order No. 879 |
| Fixed assets | Existence, condition, valuation, depreciation | Section III, item 1, Order No. 879 |
- source documents checked for mandatory details and links to contracts;
- ledgers reconciled to financial and tax reporting;
- settlements with counterparties, staff and the budget (see receivables and payables audit);
- sample counts of cash, inventory and fixed assets;
- internal controls: who approves payments and signs documents.
How we work
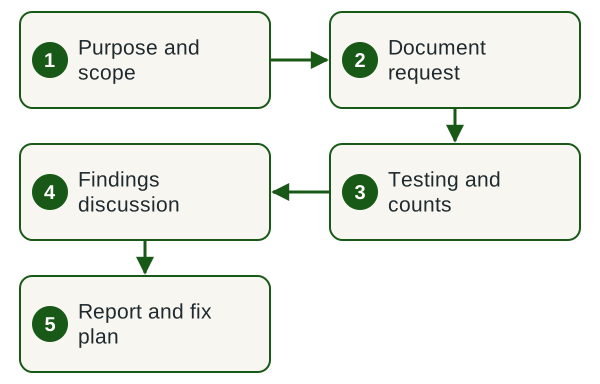
- Purpose and scope. Areas, period, count date and report format.
- Document request. Ledgers, source documents, returns and read-only system access.
- Testing and counts. Books reconciled to reports and documents, cash and assets counted.
- Findings discussion. Discrepancies explained with your accountant.
- Report and fix plan. The report goes to the owner with impact and adjustments.
The fee is agreed once we have assessed the scope and is fixed in the contract. It depends on the areas and period, the number of transactions and entities, the state of the records and on-site counts.
What we need from you
- read-only access to the accounting system or ledger exports;
- source documents and contracts for the period;
- financial statements and tax returns with filing receipts;
- a contact person in accounting;
- access to the cash desk, warehouse and fixed assets on the count date.
Deliverables
- a review report listing the discrepancies found;
- a list of errors with possible tax reassessments and penalties;
- a correction plan with owners and deadlines;
- recommendations on internal control.
Legal basis
Legal basis for the work
- Arts. 8–10 of Law No. 996-XIV: responsibility for accounting, source documents and inventory counts;
- Order No. 879 of the Ministry of Finance: inventory count procedure for fixed assets, cash and settlements;
- Paras 44.1 and 102.1 of the Tax Code: tax records based on source documents and the tax audit window;
- Part 1 of Art. 164-2 of the Code of Administrative Offences: fines of 8–15 tax-free minimum incomes for improper bookkeeping.
Why Key Solutions
- Company
- Key Solutions Audit Firm LLC (ТОВ «АУДИТОРСЬКА ФІРМА «КЕЙ СОЛЮШНЗ»), EDRPOU code 39610085. The company's details are public in the Unified State Register (ЄДР).
- Contract
- We work under a contract: scope, timing, liability and confidentiality are agreed before work starts.
- Group
- Key Solutions is part of Innova Consulting Group: legal matters are handled by legal.ua, crypto-asset taxation by crystal.tax.
- Office
- Our office is at 77 Velyka Vasylkivska St., Kyiv. We serve clients across Ukraine remotely. The specialists who run engagements are listed on the Our employees page.
Frequently asked questions
How does an accounting review differ from an audit?
An audit under ISA ends with the auditor's opinion on the financial statements as a whole. An accounting review covers the areas the owner selects and reports facts and discrepancies without an audit opinion. It is faster and cheaper; an audit is needed when a bank, investor or buyer will rely on the report. Audit reports for third parties are signed by a partner audit firm entered in the Register.
Can an accounting review replace a statutory audit?
A review prepares the company for a statutory audit and finds errors before the auditor does. The statutory audit itself is carried out and signed by a partner audit firm listed in the relevant section of the Register for statutory audit engagements. Key Solutions organises the engagement, prepares the books and statements and supports the company until publication.
Which period should the review cover?
Usually the periods the State Tax Service can still audit: as a general rule, 1,095 days after the filing deadline of the return (para 102.1 of the Tax Code). For a change of chief accountant, the current year and the previous reporting period are usually enough.
Can we order only a cash or fixed asset review?
Yes, you choose the scope. A cash review covers the cash desk, bank accounts and advances to employees; a fixed asset review covers existence, condition, valuation and depreciation.
How much does an accounting review cost?
The fee is agreed case by case. It depends on the areas reviewed, the period, the number of transactions and accounts, the state of supporting documents and whether on-site counts are needed. We fix it in the contract after a short call.
Related services
Let's plan your accounting review
Tell us which areas worry you, the period to cover and whether a count is needed. We will reply with the scope, timing and fee.
Book a consultation Order the service +38 (068) 777-14-74 Telegram WhatsApp