A budget VAT refund in Ukraine is the return of a negative VAT value from the State Budget, limited to the tax actually paid to suppliers or to the budget and to the registration limit. Key Solutions checks your entitlement and the amount, prepares the application with the calculation and supports the tax audit until the amount is agreed.
+38 (068) 777-14-74 Telegram WhatsApp
In short
- When a company needs it: a negative VAT value recurs month after month, for example because of zero-rated exports, equipment purchases or large purchases ahead of future sales.
- What you get: a verified calculation, the filing package for the VAT return, support through the desk and documentary audits, and objections and a complaint if the refund is refused.
- Timing: audit and payment deadlines are set by Art. 200 of the Tax Code of Ukraine (ПКУ). Our preparation time depends on the number of transactions and the state of primary documents, and we fix it in the contract.
- Cost: depends on the amount claimed, the number of suppliers and customs declarations, and whether a documentary audit or an appeal follows.
- How to start: a VAT consultation based on your latest VAT return. Send it and briefly describe where the negative value comes from.
Who is entitled to a VAT refund
A registered VAT payer (an LLC, another legal entity or an individual entrepreneur, ФОП) is entitled when input VAT for the period exceeds output VAT and the payer decides to take the difference back in cash (Tax Code, paras 200.1 and 200.4). The negative value first reduces any VAT debt from earlier periods; with no debt, it is refunded on application and/or carried forward to the next period's input VAT.
- Only VAT actually paid to suppliers or to the State Budget qualifies, and the amount may not exceed the registration limit calculated under para. 200-1.3 on the date the tax authority receives the return.
- Payers subject to sanctions, including sanctions on their founders, members or ultimate beneficial owners, have no refund right while the sanctions apply (para. 200.4-1).
- VAT on goods and services used for first supplies of housing is excluded from the refundable value (para. 200.4-2).
Exports are zero-rated, so exporters often carry a systematic negative value. VAT that is unsupported by tax invoices registered in the Unified Register of Tax Invoices (ЄРПН), customs declarations or other documents under para. 201.11 is excluded from input VAT. That is why unblocking tax invoices and removal from the risky payer list directly affect the amount you can claim.
How VAT is refunded from the budget
The procedure has five steps, and each rests on its own rule in Art. 200 of the Tax Code.
- The payer files the VAT return with a refund application and a refund calculation (paras 200.7 and 200.8).
- The application enters the Register of refund applications on the day of receipt and joins the queue (subpara. 200.7.2).
- The State Tax Service (ДПС, STS) runs a desk audit and, where subpara. 78.1.8 applies, an unscheduled documentary audit (paras 200.10 and 200.11).
- The amount becomes agreed in the Register or is reduced by a tax notice-decision (податкове повідомлення-рішення) (paras 200.12 and 200.14).
- The Treasury transfers the agreed amount to the payer's bank account and/or against other budget payments (para. 200.13).
What our VAT refund support includes
- Entitlement check: tax debt, sanctions restrictions, first supplies of housing.
- Reconciliation of input VAT with the ЄРПН: registered invoices and adjustment calculations, suspended invoices, receipts.
- Reconciliation of actual payments to suppliers and to the budget with bank statements.
- Control of the amount claimed against the registration limit on the filing date.
- Preparation or review of the VAT return, the refund application and the refund calculation.
- For exporters: reconciliation of customs declarations with the accounts and primary documents.
- Answers to STS requests, support through the desk and documentary audits, monitoring of the Register entries.
- Objections to the audit report and a complaint against the notice-decision. The court stage is handled by the group's lawyers at legal.ua.
How we work
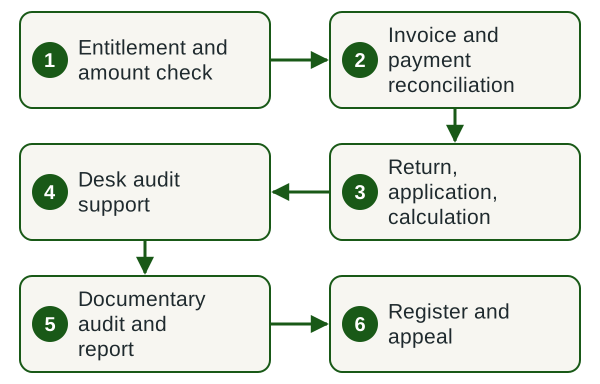
- Entitlement and amount check. We analyse recent VAT returns, tax debt and the sources of the negative value.
- Invoice and payment reconciliation. We compare ЄРПН data, bank statements and customs declarations with the accounts and list the discrepancies.
- Return, application, calculation. We prepare the filing package or review the one prepared by your accountant.
- Desk audit support. We answer STS requests and follow the entries in the Register of applications.
- Documentary audit and report. We prepare documents for the audit and, where needed, objections to the report (Tax Code, para. 86.7).
- Register and appeal. We follow the agreement and transfer of the amount and, after a refusal, draft a complaint to the higher-level authority.
Timelines
Our preparation time depends on the number of suppliers and customs declarations and on the state of primary documents; we name it after the entitlement check and fix it in the contract. Deadlines for the STS and the Treasury are set by Art. 200 of the Tax Code. A documentary audit extends the wait for the money, so we collect documents for it together with the application.
| Procedure | Deadline | Counted from |
|---|---|---|
| Desk audit of a return with a refund application (para. 200.10) | 20 calendar days | The filing deadline, or the actual filing date if later |
| Documentary audit of the refund claim (para. 200.11) | 40 calendar days (a right of the STS) | The filing deadline, or the actual filing date if later |
| Treasury transfer of the agreed amount (para. 200.13) | 5 operating days | The day after the amount becomes agreed |
| Filing a refund application (para. 102.5) | No later than day 1,095 | The day the right to the refund arose |
An unscheduled documentary audit is possible when the return claims a refund and there are grounds under Section V of the Tax Code, and/or the negative VAT value exceeds UAH 100,000 (subpara. 78.1.8). It covers only the lawfulness of the declared amount.
Important. In September 2026 the Government submitted draft law No. 16037 to the Verkhovna Rada, proposing to raise this threshold to UAH 1 million. Until the change is adopted and takes effect, the UAH 100,000 threshold of subpara. 78.1.8 applies.
What affects the cost
| Factor | Effect on scope | What to prepare |
|---|---|---|
| Amount claimed and number of periods | More periods mean more returns and calculations to reconcile | VAT returns for the refund periods |
| Number of suppliers and invoices | Each invoice is matched to the ЄРПН and to the payment | Register of received invoices, bank statements |
| Exports and customs declarations | Customs declarations are reconciled with the accounts and primary documents | Customs declarations, foreign trade contracts |
| Documentary audit | Adds requests, explanations and objections to the report | STS requests and notices, if any |
| Appeal against a refusal | A complaint to the higher-level authority and, if needed, court via legal.ua | Audit report, tax notice-decision |
What we need from you
- VAT returns with annexes for the periods in which the negative value built up.
- Registers of received and issued tax invoices and registration receipts.
- Bank statements showing payments to suppliers and to the budget.
- Contracts with key suppliers and buyers; for exports, customs declarations.
- An export from the accounting system: trial balances for VAT settlements.
- A contact person in accounting who answers STS requests promptly during the audit.
What you receive
- A conclusion on your refund entitlement and the amount you can claim, with a list of risky transactions.
- The filing package: refund application, refund calculation, list of supporting documents.
- An audit file: answers to requests, explanations, copies of primary documents.
- Where needed, objections to the audit report and a complaint against the notice-decision.
- Monitoring of the application in the Register until the money arrives.
Find out the cost of refund support
Send your latest VAT return and state the amount claimed. We will reply with the scope, timing and cost.
When the amount is agreed and paid
The amount becomes agreed in the Register on one of five dates set by para. 200.12, and three of them work in the payer's favour when the tax authority fails to act: for example, when the audit dates or the report date are missing from the Register, the amount becomes agreed on the day after the relevant deadline. The Treasury then transfers it within five operating days. If the payer has tax debt, the refund is reduced by that debt.
Refusal and appeal
A refusal or reduction is issued as a tax notice-decision, which can be appealed administratively or in court (Tax Code, para. 200.14). At the documentary audit stage the payer may file objections and additional documents within 10 working days after receiving the audit report (para. 86.7).
- A complaint to the higher-level tax authority is filed within 10 working days after receiving the notice-decision; the authority must send a reasoned decision within 20 calendar days, which its head may extend to 60 days with notice (paras 56.3, 56.8, 56.9).
- If no decision arrives within these periods, the complaint is deemed fully upheld in the payer's favour from the next day.
- Court deadlines differ between the Tax Code and the Code of Administrative Procedure of Ukraine (КАС): after a complaint, one month under para. 56.19 or three months under Art. 122(4) КАС. We plan the claim by the shorter period.
- A refusal issued because sanctions were imposed during the audit cannot be appealed (para. 200.14-1).
Amounts not refunded on time become budget arrears, and a penalty (пеня) of 120% of the National Bank of Ukraine (NBU) discount rate accrues on them in the payer's favour (para. 200.23). The penalty does not accrue where the arrears are caused by force majeure linked to martial law or a state of emergency, or where the refund was suspended or refused because of sanctions.
Legal basis
Rules the work relies on
- Tax Code of Ukraine, paras 200.1, 200.4, 200.4-1, 200.4-2 — refund entitlement, uses of the negative value, restrictions.
- Tax Code of Ukraine, paras 200.7–200.15 — application, Register, audits, agreement, transfer and refusal.
- Tax Code of Ukraine, subpara. 78.1.8 and para. 200-1.3 — grounds for a documentary audit and the registration limit.
- Tax Code of Ukraine, para. 86.7 and Art. 56 — objections to the audit report, administrative and court appeals.
- Tax Code of Ukraine, para. 200.23 — penalty for late budget refunds.
Risks, and why to hand this to a team under contract
An error in the claim costs more than the preparation. If the audit finds that the amount claimed exceeds the amount due, the STS reduces it with a notice-decision (para. 200.14) and charges a fine calculated on the overstated refund (para. 123.1). VAT on an unregistered or suspended invoice drops out of input VAT (para. 198.6), and tax debt reduces the amount returned.
We work under a contract that fixes scope, timing and the liability of the parties. Key Solutions handles the tax side, and the group's lawyers at legal.ua handle the court stage. Generic chatbot answers and one-off advice given without the documents miss your invoices, payments and audit history. Refund preparation can be combined with ongoing accounting services.
Why Key Solutions
- Turnkey, with no extra hassle
- We take the whole task: documents, calculations, reporting and correspondence with the State Tax Service. You make the decisions, provide source documents and sign; we do the rest and contact you only when it matters.
- We take on the tax office
- Information requests, blocked tax invoices, inspection reports: we prepare explanations, rework documents and appeal until the issue is closed. Where the law is in dispute, we work together with the group's lawyers.
- We see it through
- Your case stays on track: the specialist running it remains with you, even if an inspection or audit drags on for months. Statutory audits are performed, and the report signed, by a partner audit firm entitled to perform them; we handle preparation and support through publication, so you deal with one team from start to finish.
- Boutique-level involvement
- A senior specialist runs your project personally (see the Our employees page), backed by 14 years of Innova group practice in 50+ countries. Non-standard tasks are our field: where you hear “it can’t be done”, we look for a lawful way, and group companies cover the rest: legal.ua for legal matters, crystal.tax for crypto-asset taxation.
- Your affairs stay yours
- Information about your company, turnover, payroll and counterparties reaches neither competitors nor third parties. We disclose only what the law or a procedure requires, and the contract says so.
- Faster and right the first time
- Full involvement: your specialist learns your books, contracts and business, so documents and reports are ready on time with no rework. The group's 14 years of experience let us get right the first time what takes some firms three attempts.
Frequently asked questions
Who is entitled to a VAT refund from the budget in Ukraine?
A registered VAT payer with a negative VAT value that has filed a refund application. The refund is limited to VAT actually paid to suppliers or to the budget and to the amount calculated under para. 200-1.3 of the Tax Code. Any tax debt reduces the amount claimed. Payers subject to sanctions have no refund right while the sanctions apply.
How long does a VAT refund take in Ukraine?
The desk audit of a return with a refund application takes 20 calendar days following the filing deadline, and the Treasury transfers the agreed amount within five operating days after it becomes agreed. If the STS orders a documentary audit, the process is longer: the tax authority may carry it out within 40 calendar days.
What is the Register of VAT refund applications?
It is a state register where applications are entered automatically, in chronological order, during the operating day they are received, and agreed amounts are paid in the same order. It records the audit dates and type, the audit report, the notice-decision, the appeal, the agreed amount and the date of payment.
When can the STS order a documentary audit of a refund claim?
An unscheduled documentary audit is possible when the return claims a VAT refund and there are grounds under Section V of the Tax Code, and/or the negative VAT value exceeds UAH 100,000 (subpara. 78.1.8). The decision must be taken before the desk audit deadline expires, and the audit is limited to the lawfulness of the declared amount.
What can a company do if the VAT refund is refused?
A refusal or reduction is issued as a tax notice-decision, which can be appealed to the higher-level tax authority within 10 working days after receipt, or in court. If the reasoned decision on the complaint is not sent within the 20-day period or its extension, the complaint is deemed fully upheld in the payer's favour.
Is a penalty charged on late VAT refunds?
Yes, and the budget pays it to the company. Amounts not refunded on time accrue a penalty (пеня) of 120% of the NBU discount rate set when the penalty arises, for the whole period including the day of repayment. The exceptions are force majeure linked to martial law or a state of emergency, and refunds suspended or refused because of sanctions.
Which documents are needed for a VAT refund?
The company files a VAT return with a refund application and a refund calculation, and exporters add customs declarations (Tax Code, paras 200.7 and 200.8). During the STS audit you will need tax invoices registered in the ЄРПН, payment documents, contracts and primary documents for the transactions that created the negative value.
How much does VAT refund support cost?
The cost depends on the amount claimed and the number of periods, the number of suppliers and customs declarations, and whether a documentary audit or an appeal follows. We quote after reviewing your latest VAT return and fix the price in the contract before the work starts.
Related services
Discuss your VAT refund
In your request, give the period and the amount of the negative VAT value, and say whether you export and whether the STS has sent requests or an audit report. We will assess your entitlement and reply with the scope, timing and cost.
Book a consultation Order the service +38 (068) 777-14-74 Telegram WhatsApp