


An audit of accounts receivable and payable checks that the debts in the books exist, are confirmed by counterparties, are valued correctly and are written off on time. Key Solutions reconciles balances, analyses overdue amounts and gives you a plan to collect, provide for or write off each debt.
+38 (068) 777-14-74 Telegram WhatsApp
In short
- When: before year-end reporting, an audit or a business sale, after a change of accountant, or when old balances pile up.
- You get: a debt register by counterparty and age, reconciliations, a write-off list and a bad debt allowance calculation.
- Timing: in our experience, 1–3 weeks after we receive the documents; counterparty replies take the longest.
- Fee: agreed case by case, based on counterparties, transaction volume, period and the state of reconciliations.
- Start: send the trial balance for the settlement accounts and tell us which balances look doubtful.
How we audit accounts receivable
Receivables testing confirms that customers really owe the amounts shown and that the company will collect them. For Ukrainian companies we work on settlement accounts 36, 37 and 68 of the national chart of accounts.
- aged receivables listing reconciled to the general ledger;
- external balance confirmations (the ISA 505 method) and reconciliation statements under Order No. 879;
- invoices tested against contracts and delivery documents, with cut-off at period end;
- cash received after the period end;
- the bad debt allowance, calculated by specific identification or a doubtfulness ratio (para 8 of NP(S)BO 10);
- related-party balances.
Accounts payable audit: what we check
The payables audit looks for completeness: every liability recorded, nothing released too early, nothing kept after it has lapsed. We work on accounts 63 and 68.
- supplier statements reconciled and balances confirmed;
- a search for unrecorded liabilities in post-period payments and invoices;
- payables past the limitation period, which are released to income (para 5 of NP(S)BO 11);
- priority debts: wages, taxes and secured loans.
If a bank or buyer needs a report under international standards, the audit or agreed-upon procedures report is signed by a partner audit firm entered in the Register. Key Solutions prepares the debt register, reconciliations and documents for it.
How we work
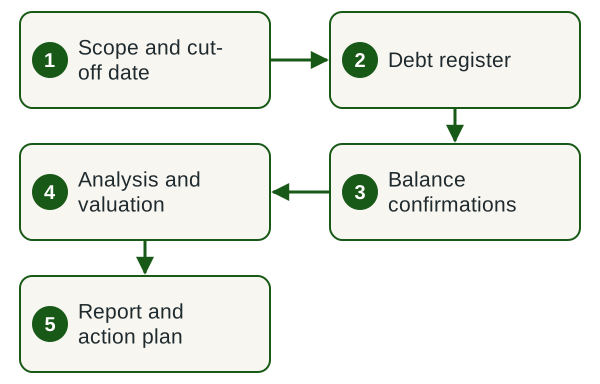
- Scope and cut-off date. Accounts, counterparties, period and confirmation date.
- Debt register. Balances by counterparty, contract and age.
- Balance confirmations. Requests sent and replies collected.
- Analysis and valuation. Limitation periods, allowance, classification and write-off documents.
- Report and action plan. Debts to collect, provide for and write off.
What we need from you
- trial balance for settlement accounts for the period;
- contracts, acceptance certificates, invoices and existing reconciliations;
- bank statements;
- correspondence with debtors and a list of disputed balances;
- a contact person in accounting.
Deliverables
- a debt register by counterparty and age;
- counterparty replies and signed reconciliations;
- a write-off list with reasons;
- a bad debt allowance calculation;
- an action plan for each problem debt. Court collection is handled by our group company legal.ua.
Legal basis
Legal basis for the work
- Arts. 257, 264 and 530 of the Civil Code: limitation period, its interruption and payment on demand;
- Law No. 4434-IX: limitation periods resumed after the martial-law suspension;
- NP(S)BO 10 and NP(S)BO 11: receivables, bad debts, allowance and release of liabilities;
- Order No. 879 of the Ministry of Finance: inventory of settlements and reconciliation with debtors.
Why Key Solutions
- Company
- Key Solutions Audit Firm LLC (ТОВ «АУДИТОРСЬКА ФІРМА «КЕЙ СОЛЮШНЗ»), EDRPOU code 39610085. The company's details are public in the Unified State Register (ЄДР).
- Contract
- We work under a contract: scope, timing, liability and confidentiality are agreed before work starts.
- Group
- Key Solutions is part of Innova Consulting Group: legal matters are handled by legal.ua, crypto-asset taxation by crystal.tax.
- Office
- Our office is at 77 Velyka Vasylkivska St., Kyiv. We serve clients across Ukraine remotely. The specialists who run engagements are listed on the Our employees page.
Frequently asked questions
How do you audit accounts receivable?
We reconcile the aged receivables listing to the ledger, send external balance confirmations (the ISA 505 method), test invoices against contracts and delivery documents, check cash received after the period end and assess the bad debt allowance. The result shows which balances exist and what the company will actually collect.
What does an accounts payable audit check?
An accounts payable audit checks that liabilities are complete and accurate. We reconcile supplier statements, confirm balances, search for unrecorded liabilities in post-period payments and invoices, and identify payables that are no longer due and should be released to income under Ukrainian GAAP.
What is the limitation period for debts in Ukraine?
The general limitation period is three years (Art. 257 of the Civil Code). It restarts when the debtor acknowledges the debt, for example by a partial payment (Art. 264). During martial law the period was suspended until Law No. 4434-IX took effect on 4 September 2025, so each debt needs an individual calculation.
How are bad debts written off in Ukraine?
A receivable is written off when it becomes irrecoverable: the limitation period has expired or the debtor will certainly not pay (para 4 of NP(S)BO 10). It is removed from assets against the bad debt allowance; any shortfall goes to other operating expenses (para 11). The tax criteria are listed in sub-para 14.1.11 of the Tax Code. The write-off needs an inventory count report, a list of time-barred debts and a management order.
How much does a receivables and payables audit cost?
The fee is agreed case by case, based on the number of counterparties and transactions, the period, the state of reconciliations and whether confirmations are needed. We quote after reviewing the trial balance for the settlement accounts and fix the fee in the contract.
Related services
Let's review your receivables and payables
Send the trial balance for your settlement accounts and tell us which balances look doubtful. We will reply with the scope, timing and fee.
Book a consultation Order the service +38 (068) 777-14-74 Telegram WhatsApp