
A company tax audit is an independent review of tax accounting, returns and primary documents commissioned by the owner or management. Key Solutions finds errors before a State Tax Service (ДПС) inspection, estimates the risk of additional assessments and gives you a correction plan.
+38 (068) 777-14-74 Telegram WhatsApp
In short
- When you need it: before a scheduled tax inspection, after a change of accountant or director, before a sale or an investor's entry.
- What you get: a report listing errors and potential assessments, with references to the Tax Code of Ukraine (ПКУ), and a correction plan.
- Timing: fixed in the contract after an initial review.
- Cost: depends on the tax regime, transaction volume, periods and the state of the documents.
- How to start: tell us your tax regime, the periods and whether an audit order has arrived.
When a company needs a tax audit
Companies order a tax audit to:
- check accounting and returns and correct errors in time;
- take over the books after a change of chief accountant, finance director or CEO;
- prepare for a scheduled documentary audit (see audit before a tax inspection);
- prepare the company for a sale, an investor's entry or a reorganisation.
What the audit covers
We check returns against registers, and registers against primary documents and contracts. This shows where an error started and how many periods it affects.
| Area | What we reconcile | Typical risk |
|---|---|---|
| Corporate income tax | Financial result, tax differences, expenses | Expenses disallowed, tax assessed |
| VAT | Tax invoices in the Unified Register (ЄРПН), input VAT, returns | Input VAT disallowed, invoices blocked |
| Payroll taxes and the unified social contribution (ЄСВ) | Salaries and payments to individuals | Additional tax and a tax-agent penalty |
| Primary documents and contracts | Acts, waybills, reality of transactions | Transactions treated as not having taken place |
| Data for e-audit (SAF-T UA) | Registers, trial balances, accounting system | Late documents treated as missing (paras 44.6, 86.7 Tax Code) |
How we work
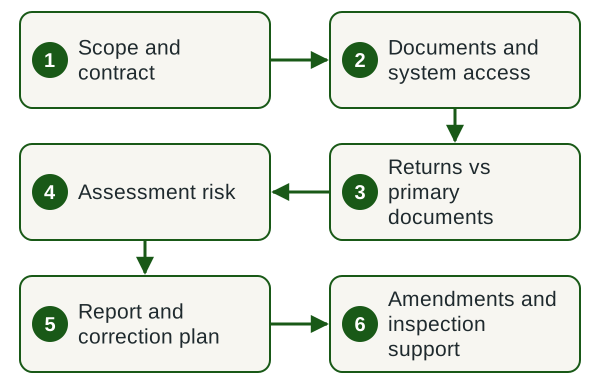
- Scope and contract We agree taxes, periods, timing and liability.
- Documents and system access We receive returns, registers, contracts and read-only access to the accounting system.
- Returns vs primary documents We test transactions on a sample basis.
- Assessment risk For each error we calculate the tax and possible penalties.
- Report and correction plan We review the report with management and the accountant.
- Amendments and inspection support We prepare amended returns with your accountant and support the inspection if needed.
Timing
We fix the timing in the contract after the initial review; it depends on the taxes, periods and volume of documents. The State Tax Service gives notice of a scheduled documentary audit at least 10 calendar days in advance (para 77.4 of the Tax Code). If the order has arrived, we start with the taxes in its scope.
What affects the cost
- the tax regime and the number of taxes in scope;
- the number of transactions, counterparties and periods;
- the state of primary documents and the accounting system;
- foreign trade, settlements with non-residents and controlled transactions;
- a short deadline before an inspection.
What we need from you
- Tax returns for the periods under review, with filing receipts.
- Trial balances, registers and financial statements.
- Key contracts and primary documents from our sample.
- Read-only access to the accounting system and your integrated taxpayer card data (інтегрована картка платника).
- Recent letters and audit reports from the tax authority, if any.
Result of the tax audit
Management receives a written report with:
- violations of the law, if any, with references to specific articles of the Tax Code;
- potential additional taxes, and underpaid or overpaid amounts;
- a list of returns that need amending;
- an assessment of the risk of a documentary audit;
- a correction plan.
Cost of an error: penalties and martial-law relief
| Situation | Penalty | Rule |
|---|---|---|
| Understatement found by the tax authority | 10%, intentional 25%, repeated 50%. Under martial law, paying within 30 days of the tax notice-decision cancels the penalty and late-payment interest | paras 123.1–123.3 Tax Code; sub-para 69.37, subsec. 10, sec. XX |
| Late payment of an agreed liability | 5% up to 30 days, 10% over 30 days; 25% if intentional; 50% if repeated or over 90 days | paras 124.1–124.3 Tax Code |
| Self-correction of an error | 3% or 5%; under martial law, no penalty or interest | para 50.1 Tax Code; sub-para 69.38, subsec. 10, sec. XX |
Important. Once a documentary audit starts, an amended return for the period under review can no longer be filed (para 50.2 of the Tax Code). Penalty-free self-correction for that period is available only before the audit.
Legal framework
Rules the work relies on
- Art. 75 of the Tax Code — types of tax inspections: desk, documentary and field.
- Para 102.1 of the Tax Code — limitation period for assessments.
- Arts. 123 and 124 of the Tax Code — penalties for understatement and late payment.
- Sub-paras 69.35-1, 69.36–69.38, subsec. 10, sec. XX of the Tax Code — moratorium on inspections and martial-law relief.
Risks, and why to hand this to a team under contract
One error often affects several taxes and periods, and an accountant reviewing their own work tends to miss it. Key Solutions works under a contract, and each conclusion rests on a specific rule of the Tax Code. Disputes that may reach court are handled with the lawyers of legal.ua. If the books need rebuilding, the same team takes it on: restoration of accounting.
Why Key Solutions
- Turnkey, with no extra hassle
- We take the whole task: documents, calculations, reporting and correspondence with the State Tax Service. You make the decisions, provide source documents and sign; we do the rest and contact you only when it matters.
- We take on the tax office
- Information requests, blocked tax invoices, inspection reports: we prepare explanations, rework documents and appeal until the issue is closed. Where the law is in dispute, we work together with the group's lawyers.
- We see it through
- Your case stays on track: the specialist running it remains with you, even if an inspection or audit drags on for months. Statutory audits are performed, and the report signed, by a partner audit firm entitled to perform them; we handle preparation and support through publication, so you deal with one team from start to finish.
- Boutique-level involvement
- A senior specialist runs your project personally (see the Our employees page), backed by 14 years of Innova group practice in 50+ countries. Non-standard tasks are our field: where you hear “it can’t be done”, we look for a lawful way, and group companies cover the rest: legal.ua for legal matters, crystal.tax for crypto-asset taxation.
- Your affairs stay yours
- Information about your company, turnover, payroll and counterparties reaches neither competitors nor third parties. We disclose only what the law or a procedure requires, and the contract says so.
- Faster and right the first time
- Full involvement: your specialist learns your books, contracts and business, so documents and reports are ready on time with no rework. The group's 14 years of experience let us get right the first time what takes some firms three attempts.
Frequently asked questions
How is a tax audit different from a State Tax Service inspection?
A tax audit is a voluntary review commissioned by the owner. A State Tax Service inspection is state control under Art. 75 of the Tax Code, with the power to assess tax and penalties. The audit lets you file amended returns before the inspector arrives.
How often should a company have a tax audit?
Usually every one or two years, plus after a change of chief accountant, director or owner and before a scheduled inspection. Management sets the frequency based on the scale of the business and the findings of earlier reviews.
How many years back can the tax authority check a company?
Generally 1,095 days after the filing deadline; for transfer pricing and non-resident income, 2,555 days (para 102.1 of the Tax Code). For taxpayers under the martial-law moratorium the period is suspended (sub-para 69.36, subsec. 10, sec. XX).
What is SAF-T UA and who must submit it?
SAF-T UA is the Standard Audit File, an electronic export of accounting data in a format set by the Ministry of Finance. A large taxpayer provides it on request during an audit within two working days (para 85.2 of the Tax Code). As of September 2026, the law does not require regular filing by all VAT payers.
Are tax inspections suspended in Ukraine in 2026?
Partly. The moratorium covers taxpayers in temporarily occupied territories and areas of active or possible hostilities, with exceptions (sub-para 69.35-1, subsec. 10, sec. XX of the Tax Code). Other companies are inspected as usual.
How much does a tax audit cost?
It depends on the tax regime, transaction volume, the number of periods and the state of the documents. We quote after the initial review and fix the price in the contract.
Related services
Let's discuss your tax audit
Tell us your tax regime, monthly number of transactions, the periods to review and whether an audit order has arrived. We will reply with the document list, scope and price.
Book a consultation Order the service +38 (068) 777-14-74 Telegram WhatsApp