


Agricultural accounting is accounting for biological assets, harvest, production cost, land and taxes of a farm business under Ukrainian standard NP(S)BO 30 and the Tax Code of Ukraine (ПКУ). Key Solutions keeps these books under contract for farms across Ukraine.
+38 (068) 777-14-74 Telegram WhatsApp
In short
- When you need it: the business has no in-house accountant with farming experience, harvest and cost are recorded without costing by crop, or the company is moving to single tax group 4 or registering for VAT.
- What you get: accounting for biological assets and harvest, single tax group 4 with the minimum tax liability, VAT, taxes on land share rent, payroll and filings on Tax Code deadlines.
- Timing: depends on the number of open periods, the state of primary documents and lease agreements. We name the handover date after a review and fix it in the contract.
- Cost: depends on land area and number of leases, lines of production, VAT, headcount and document volume. We quote after a review.
- First step: book a consultation and tell us the owned and leased land area, your tax system and lines of production.
What makes accounting in agriculture different
Farm accounting differs in its subject: the main items are live animals and plants, harvest and land, and taxes depend on land area and the share of agricultural production. The Ukrainian standard NP(S)BO 30 “Biological Assets” (НП(С)БО 30 «Біологічні активи») defines a biological asset as a live animal or plant that, through biological transformation, can yield agricultural produce and/or additional biological assets.
| Transaction | How we record it | Legal basis |
|---|---|---|
| Animals: breeding herd, young stock | At fair value less costs to sell, where it can be measured reliably | NP(S)BO 30, paras. 7, 10 |
| Current-year crops | Without a reliable fair value, as work in progress under NP(S)BO 9 | NP(S)BO 30, para. 11 |
| Harvest | Recognised in the harvest period at fair value less costs to sell, or at cost | NP(S)BO 30, para. 12 |
| Land share leases from individuals | As tax agent, the lessee withholds personal income tax (ПДФО) 18% and military levy (військовий збір) 5% | Tax Code, subpara. 170.1.1, para. 167.1; para. 16-1 subsec. 10 sec. XX |
| Sales of grain and oilseeds | VAT 14% on wheat, barley, maize, soya, rapeseed and sunflower seed | Tax Code, subpara. «г» of para. 193.1; tariff codes 1001, 1003, 1005, 1201, 1205, 1206 00 |
Bearer plants such as orchards are accounted for under other standards, while their produce falls under NP(S)BO 30 (subpara. 3.4). We set the accounting policy, with biological asset groups, the measurement method and costing by crop, before the first month-end close.
Single tax group 4 and the minimum tax liability
A legal entity can pay single tax group 4 (єдиний податок 4 групи) if its share of agricultural production for the previous year is 75% or more (Tax Code, subpara. «а» of subpara. 4 of para. 291.4). A sole proprietor (ФОП) qualifies when farming within a family farm with family members, with 0.5 to 20 hectares of farmland and without hired staff (subpara. «б»).
- The tax object is the area of farmland and water fund land owned or used, including under lease or emphyteusis (para. 292-1.1). The base is the indexed normative monetary valuation of land (para. 292-1.2). Land under conservation, contaminated by explosive objects or recognised as potentially contaminated is excluded from the tax object for that period (para. 292-1.1, third paragraph).
- The rate for arable land, hayfields and pastures outside mountain zones, Polissia territories and greenhouses is 0.95% of the base (subpara. 293.9.1).
- The return for the current year is due by 20 February; the tax is paid quarterly within 30 days after each quarter, in shares of 10%, 10%, 50% and 30% (para. 295.9).
- The single tax VAT exemption does not extend to group 4 (subpara. 3 of para. 297.1). A VAT-registered group 4 payer registers tax invoices in the Unified Register of Tax Invoices (ЄРПН) and faces the risk of suspension.
- The minimum tax liability (МПЗ) is calculated for each farmland plot with a normative monetary valuation: valuation × K × months / 12. The base K is 0.05 (subpara. 38-1.1.1); for 2025 and later years, up to and including the year martial law ends or is lifted, K is 0.057 (para. 67-1 subsec. 10 sec. XX). The calculation is filed as an annex to the annual return (para. 297-1.1).
Important. If a legal entity’s share of agricultural production for the year falls below the threshold, it pays tax under the general rules the following year (Tax Code, subpara. 298.8.4). Check the share every quarter, before the year ends.
Outsourced agricultural accounting: what the business gets
Outsourcing a farm’s accounting means that the Key Solutions team keeps the books, taxes, payroll and filings under contract, and the owner receives ready figures and payment dates. We assign an accountant who knows the seasons, land shareholders and harvest warehouse accounting.
- You save the cost of a workstation, salary, holiday pay and sick pay for an in-house accountant.
- When the assigned accountant is on leave or ill, a colleague from the team steps in and the books keep moving.
- Payments, bank and cash transactions, VAT and HR records are covered by one contract.
- During tax inspections the accountant supports the business and prepares explanations.
If the company also imports fruit, vegetables or seeds, customs payments and currency settlements are covered on the page accounting for importers and foreign trade. All our accounting services are collected in the Key Solutions accounting services section.
What the service includes
- Accounting policy under NP(S)BO 30: biological asset groups, measurement, costing by crop and by type of animal.
- Primary documents: write-off reports for seed, fertiliser, crop protection products and fuel, harvest receipt documents, delivery notes.
- Biological assets, harvest, inventories and work in progress.
- Land leases: agreements with land shareholders, rent accruals, withholding of personal income tax and military levy.
- Single tax group 4, minimum tax liability, VAT, tax invoices and their registration in ЄРПН.
- Payroll and HR records, including seasonal workers (payroll calculation and payment).
- Financial, tax and statistical reporting, replies to tax authority requests.
- Stock and harvest counts before the year-end close (inventory count).
How we work
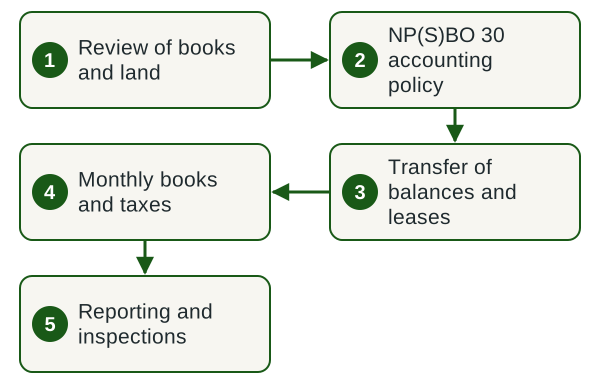
- Review of books and land. We review the books, lease agreements, tax system and open periods, and name the risks.
- NP(S)BO 30 accounting policy. We agree asset groups, measurement, cost items and document flow with the agronomist and the warehouse.
- Transfer of balances and leases. We take over balances, the register of plots and landowners, and access to the accounting system (BAS or another).
- Monthly books and taxes. We process primary documents, calculate taxes and payroll, and report amounts and due dates.
- Reporting and inspections. We file reports, answer tax authority requests and support inspections.
Timing
The start depends on the number of open periods, the state of primary documents and how many lease agreements need to be transferred. We name the handover date after a review and fix it in the contract. After that, we file on Tax Code deadlines. The heaviest workload in farming falls on the harvest, the year-end stock count and the annual single tax return.
What affects the cost
- Land area and the number of lease agreements with land shareholders.
- Lines of production: crops, livestock, processing, harvest storage.
- Tax system, VAT, exports of produce.
- Number of employees, including seasonal workers.
- Volume of primary documents and the state of the books at the start.
What we need from you
- Founding documents and registration details of the company or sole proprietor.
- A list of land plots with cadastral numbers, lease agreements and normative monetary valuation data.
- Opening balances and primary documents for the current period.
- Access to the accounting system and bank statements.
- A contact person (agronomist or warehouse manager) for data on sowing, harvest and write-offs.
- Approval of payments and documents within the agreed time.
What you receive
- Books kept under NP(S)BO 30, with production cost by crop.
- Single tax group 4 returns with the minimum tax liability annex, VAT returns and financial statements, filed on time.
- Taxes on rent and payroll accrued and withheld.
- Registered tax invoices and written replies to tax authority requests.
- Notices of tax amounts and due dates for each period.
Find out the cost of the service
Name your lines of production, the number of lease agreements and whether you pay VAT. We will offer a review of your books and quote the fee.
Legal basis
Rules this work relies on
- Tax Code, subpara. 14.1.235 and subpara. 4 of para. 291.4 — who counts as an agricultural producer and the conditions for group 4.
- Tax Code, Art. 292-1, paras. 293.9, 295.9, 298.8 — tax object, rates, payment deadlines and moving to group 4.
- Tax Code, Arts. 38-1, 297-1, para. 67-1 subsec. 10 sec. XX — minimum tax liability.
- Tax Code, subpara. 170.1.1 — the lessee as tax agent of the owner of a land share.
- Tax Code, subpara. «г» of para. 193.1, subpara. 3 of para. 297.1 — VAT rate for grain and oilseeds, VAT for group 4 payers.
- NP(S)BO 30 “Biological Assets”, Ministry of Finance Order No. 790 of 18 November 2005 — recognition and measurement of biological assets and agricultural produce.
- Art. 2(1) of Law No. 996-XIV (Закон «Про бухгалтерський облік та фінансову звітність в Україні») — the duty of every legal entity, whatever its legal form and ownership, to keep accounts and file financial statements.
Risks and why to hand accounting to a contracted team
In farming, errors build up over a season and surface at an inspection or in the annual return. Typical ones: the agricultural share is checked only after year-end, and the company loses group 4 the following year; the minimum tax liability is calculated without some leased plots; personal income tax is not withheld from land share rent; the harvest is recorded without documents, and a shortage appears at the stock count; tax invoices for grain sales are suspended in ЄРПН.
Key Solutions works under a contract that sets out scope, deadlines and liability. We handle legal matters, such as disputes under land lease agreements, together with the group’s lawyers. A one-off answer from a chatbot or a freelancer settles a single question; a season’s books need a team that is accountable for the whole year.
Why Key Solutions
- Company
- ТОВ «АУДИТОРСЬКА ФІРМА «КЕЙ СОЛЮШНЗ», a Ukrainian limited liability company, EDRPOU code 39610085. The company's details are public in the Unified State Register (ЄДР).
- Contract
- We work under a written contract: scope, deadlines and liability are agreed before work starts. Client information is protected by professional confidentiality (Art. 11 of the Law on Audit of Financial Statements and Auditing Activities No. 2258-VIII, Закон «Про аудит фінансової звітності та аудиторську діяльність»).
- Group
- We are part of Innova Consulting Group: legal matters are handled by legal.ua, crypto-asset taxation by crystal.tax.
- Office
- Our office is at 77 Velyka Vasylkivska St, Kyiv. We serve clients across Ukraine remotely. The specialists who run projects are listed on the Our employees page.
Frequently asked questions
How is accounting kept at an agricultural company in Ukraine?
An agricultural company keeps its books under Law No. 996-XIV and NP(S)BO 30: animals and crops are recorded as biological assets, the harvest is recognised in the harvest period, and cost is calculated by crop. Tax accounting depends on the tax system: single tax group 4, group 3, or the general system with corporate income tax.
Who can pay single tax group 4?
Single tax group 4 is open to agricultural producers: a legal entity whose share of agricultural production for the previous year meets the threshold in subpara. «а» of subpara. 4 of para. 291.4 of the Tax Code, or a sole proprietor farming within a family farm with family members, without hired staff and with land within the limits of subpara. «б». We check the conditions during the review.
How are biological assets accounted for?
Biological assets are carried at fair value less expected costs to sell, where fair value can be measured reliably (NP(S)BO 30, paras. 7, 10). Where it cannot, the asset is carried at initial cost, and current crop assets are shown as work in progress (NP(S)BO 30, para. 11).
Does a group 4 agricultural producer pay VAT?
Yes, a group 4 producer pays VAT if it is registered as a VAT payer: the exemption in subpara. 3 of para. 297.1 of the Tax Code does not extend to group 4. A reduced rate applies to grain and oilseeds under subpara. «г» of para. 193.1. Tax invoices are registered in ЄРПН on the general terms.
Who pays tax on rent for land shares?
Tax on rent for land shares is withheld and paid by the lessee as tax agent of the landowner (Tax Code, subpara. 170.1.1). The lessee withholds personal income tax and the military levy; the base is the rent under the lease or the minimum rent payment, whichever is higher (subpara. 170.1.1, second paragraph). We keep the register of landowners and calculate the withholdings.
Can a farm outside Kyiv outsource its accounting?
Yes, a farm in any region of Ukraine can outsource its accounting. The Key Solutions office is in Kyiv, and we serve clients in other regions, including Lviv region, remotely: documents arrive electronically and the books are kept in an accounting system agreed at the start.
Related services
Let’s discuss your farm’s accounting
Tell us the owned and leased land area, the number of agreements with land shareholders, your tax system and whether you pay VAT. We will reply with the service format, the handover timing and the fee.
Book a consultation Order the service +38 (068) 777-14-74 Telegram WhatsApp