


Payroll outsourcing for foreign and offshore companies is the calculation, accrual and reporting of pay for people who work in Ukraine for a non-resident. Key Solutions determines who withholds income tax and pays social contributions, runs the payroll and files the reports under Ukrainian rules.
+38 (068) 777-14-74 Telegram WhatsApp
In short
- Who it is for: foreign and offshore companies with staff or contractors in Ukraine, their representative offices and Ukrainian subsidiaries of international groups.
- What you get: a clear tax scheme, monthly payroll with income tax, military levy and USC, payslips, payment files and the monthly tax return.
- Timing: in our experience set-up depends on headcount and the state of HR documents; then payroll runs monthly on the agreed calendar.
- Cost: agreed individually, based on headcount, presence model and group reporting.
- How to start: tell us where the company is registered, whether it has an office in Ukraine and how many people it pays.
Who withholds tax when the employer is a non-resident
It depends on who pays people in Ukraine. The Tax Code treats a legal entity, its separate unit and a non-resident's representative office as tax agents (subpara. 14.1.180 of the Tax Code). A non-resident without an office is not a tax agent, and the person pays tax on that income personally.
| Model | Income tax and military levy | Social contribution (USC) |
|---|---|---|
| Representative office in Ukraine | Withheld by the office as tax agent | Paid by the office (Art. 4, Law 2464-VI) |
| Ukrainian subsidiary (LLC) | Withheld by the LLC | Paid by the LLC as employer |
| Non-resident pays directly | Declared by the person (para. 170.11.1) | Voluntary, under a contract (Art. 10) |
The rates are the same in all three models: personal income tax 18% (para. 167.1 of the Tax Code) and military levy 5%. An employer in Ukraine also pays a 22% USC on payroll, and at the main place of work (except non-fixed-hours contracts) the contribution is at least 22% of the minimum wage, UAH 8,647 in 2026 (Part 5, Art. 8 of Law No. 2464-VI).
When a team in Ukraine creates tax duties for the non-resident
A permanent establishment is a fixed place through which a non-resident carries on business in Ukraine, such as a place of management, office, branch or warehouse (subpara. 14.1.193 of the Tax Code). Operating through a permanent establishment without tax registration, confirmed by a tax audit report, is a ground for arrest of property (subpara. 94.2.9). legal.ua advises on the group structure and office registration; crystal.tax handles controlled foreign company (CFC) reporting for owners of offshore companies.
What the service covers
- A review of the employer's registration, any office in Ukraine and contracts with people.
- A tax scheme: who is tax agent, who pays USC, what people declare themselves.
- Monthly payroll, holiday and sick pay and bonuses for staff of the office or subsidiary.
- Withholding of income tax and military levy, USC, payment orders and bank payment files.
- The monthly tax return on individuals' income and USC, income certificates and payslips.
- Annual returns for people paid directly by the non-resident and a staff cost report for the parent company.
How the work runs
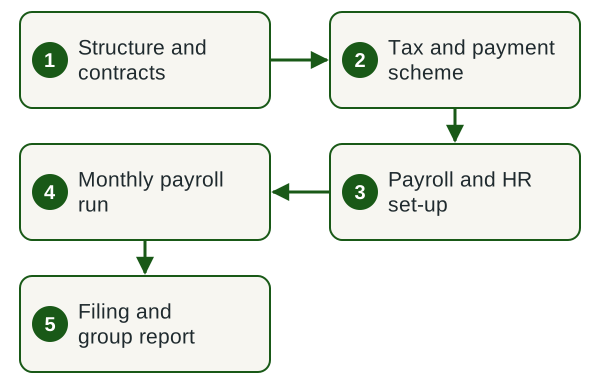
- Structure and contracts Where the employer is registered and how people are engaged.
- Tax and payment scheme Tax agent, USC payer and income people declare themselves.
- Payroll and HR set-up Pay calendar, payslip format and HR documents agreed.
- Monthly payroll run Pay, withholdings and contributions, bank payment file.
- Filing and group report Monthly tax return and a staff cost report for the parent.
Timing and cost
Salaries are paid at least twice a month (Art. 24 of Law No. 108/95-VR), and a legal entity files the tax return within 20 calendar days after month-end (para. 51.1, subpara. 49.18.1 of the Tax Code). The fee is agreed individually: headcount, presence model, HR records, group reporting and any catch-up for past months drive the scope.
What we need from you
- Registration documents of the non-resident and its Ukrainian office or subsidiary.
- Employment and service contracts, orders, bonus policy.
- Monthly timesheets, holiday and sick leave data by the agreed date.
- Payment details and a contact at the parent company for approvals.
What you receive
- A written scheme showing the tax agent and USC payer in your structure.
- Monthly payslips, payroll register and tax payment orders.
- Filed tax returns and income certificates for employees.
- A staff cost report for the parent company.
Legal basis
Legal basis for the work
- Tax Code of Ukraine — subparas. 14.1.180, 14.1.193, para. 167.1, para. 170.11, para. 64.5, subpara. 94.2.9, para. 16-1 of subsection 10 of Section XX.
- Law No. 2464-VI — Arts. 4, 8 and 10: USC payers, rate, voluntary payment.
- Law No. 108/95-VR on Remuneration of Labour — Arts. 23 and 24: form and frequency of pay.
Why a contracted team is the safer choice
A wrong payment scheme costs more than the payroll work: tax not withheld on time is assessed at a tax audit with a fine and late-payment interest, and an unregistered permanent establishment exposes the company to arrest of property. Key Solutions works under a contract with agreed scope, timing and liability, and the confidentiality of employee data is set out in the contract.
Why Key Solutions
- Company
- ТОВ «АУДИТОРСЬКА ФІРМА «КЕЙ СОЛЮШНЗ», a Ukrainian limited liability company, EDRPOU code 39610085. The company's details are public in the Unified State Register (ЄДР).
- Contract
- We work under a contract: scope, timing, liability and confidentiality are agreed before work starts.
- Group
- Key Solutions is part of Innova Consulting Group: legal matters are handled by legal.ua, crypto-asset taxation by crystal.tax.
- Office
- Our office is at 77 Velyka Vasylkivska St., Kyiv. We serve clients across Ukraine remotely. The specialists who run engagements are listed on the Our employees page.
Frequently asked questions
Who pays personal income tax if a foreign company without a Ukrainian office pays the salary?
The employee. A non-resident is not a tax agent, so the person reports the income in the annual return by 1 May and pays the tax by 1 August of the following year (subparas. 168.2.1 and 49.18.4, paras. 170.11.1 and 179.7 of the Tax Code). We can prepare these returns for your team.
Does a foreign company need a representative office to hire people in Ukraine?
A representative office acts as tax agent and pays the unified social contribution (USC) as an employer, so payroll follows standard Ukrainian rules. A non-resident operating through a separate unit must register with the tax authority (para. 64.5 of the Tax Code). legal.ua advises on the structure; we run the books and payroll.
Can salaries be paid in crypto or to a foreign bank card?
Employees of enterprises in Ukraine are paid in money that is legal tender in Ukraine, which is the hryvnia (Art. 23 of Law No. 108/95-VR; Art. 32 of the Law on the National Bank of Ukraine). Income a Ukrainian resident receives from a non-resident abroad is declared in Ukraine. Taxation of crypto payments is covered by crystal.tax.
Is the unified social contribution due on pay from a non-resident?
The law lists branches and representative offices of foreign companies located in Ukraine as USC payers (Art. 4 of Law No. 2464-VI). A non-resident without an office is not on that list; the person may pay the USC voluntarily under a contract (Art. 10).
Can tax paid abroad be credited in Ukraine?
Yes, if a double tax treaty ratified by the Verkhovna Rada allows it and the person holds documents confirming the income and the foreign tax (para. 170.11.2 of the Tax Code).
How much does payroll outsourcing for a foreign company cost?
The fee is agreed individually and depends on headcount, the presence model in Ukraine, HR records and group reporting. We quote after reviewing the structure and contracts.
Related services
Order payroll outsourcing for a foreign company
Describe the structure: country of registration, any office in Ukraine, headcount and contract types. We will send the tax scheme, calendar and fee.
Book a consultation Order the service +38 (068) 777-14-74 Telegram WhatsApp