


Tax compliance in Ukraine starts with a clean tax account: reconciling what the tax authority shows with your books, recovering or offsetting overpayments, and settling or rescheduling tax debt. Key Solutions does this under contract, explains every difference and prepares the filings.
+38 (068) 777-14-74 Telegram WhatsApp
In short
- When you need it: the e-cabinet shows a debt or overpayment your books do not; penalties or late-payment interest have appeared; a bank, tender or Diia City status requires a clean tax record.
- What you get: a reconciliation for each tax, a list of differences with causes, applications and amended returns, a payment plan.
- Timing: depends on how many taxes and years need checking. Statutory deadlines of the tax authority are given below with references.
- Cost: agreed individually, based on the number of taxes, periods and the state of the books.
- First step: book a consultation and send the settlement statement from the taxpayer's e-cabinet.
Where differences with the tax authority come from
A difference arises when the balance shown by the State Tax Service (ДПС) for a tax does not match the balance in the company's books. The Tax Code gives taxpayers the right to reconcile their settlements with the budget in the electronic cabinet and obtain a statement of their status (para. 42-1.2).
- a payment went to the wrong tax or budget because of incorrect details;
- a return or amended return was filed but not reflected in the books;
- a tax assessment notice after an audit charges an amount the company disputes;
- while a tax debt exists, new payments are applied to it in order of age, whatever their stated purpose (para. 87.9);
- late-payment interest on a delay nobody noticed: on self-assessed amounts it starts after 90 calendar days (subpara. 129.1.3).
Overpayments, debt and errors: what we do
| Situation | What we do | Tax Code |
|---|---|---|
| Overpayment | Refund or offset application within 1,095 days | paras. 43.3, 43.4 |
| Overpayment with a debt | Debt is cleared first, then the balance is refunded | para. 43.2 |
| Error in a filed return | Amended return before any audit | paras. 50.1, 50.2 |
| Disputed assessment | Review and administrative appeal | Art. 56 |
| No funds to pay | Instalment or deferral application with justification | Art. 100 |
The tax authority prepares a refund conclusion no later than five working days before the 20-day period from the application ends, and the treasury pays within five working days of receiving it (para. 43.5). Instalments are repaid in equal parts from the following month (para. 100.6) with interest at 120% of the NBU discount rate per year (para. 100.1). Under martial law, if tax assessed after a documentary audit is paid within 30 calendar days of receiving the decision, the related fines are cancelled and no late-payment interest is charged, but the amount can no longer be appealed (Tax Code, subpara. 69.37 of para. 69, subsection 10, Section XX; audits started or resumed from 1 August 2023). A second martial-law rule: when a company corrects an understatement itself with an amended return under Art. 50, no fine under para. 50.1 and no late-payment interest are charged (subpara. 69.38). We calculate whether paying or appealing makes more sense before those 30 days run out. Appeals are covered by our tax complaint service.
Tax planning within the law
Tax planning means choosing lawful tax treatment before transactions happen: the tax system, how contractors are engaged, the structure of deals and the split of functions within a group. We review transactions, settlements with counterparties, the legal form of the business and double taxation issues. Choosing or changing the tax system is covered by our tax system optimisation service, one-off questions by tax advisory.
What the service includes
- reconciliation of e-cabinet data with the books and bank payments for each tax and period;
- a list of differences with the cause and amount of each;
- refund and offset applications, amended returns;
- a check of penalties and late-payment interest, with objections;
- an instalment or deferral application with economic justification;
- a tax payment calendar for the coming periods.
How we work
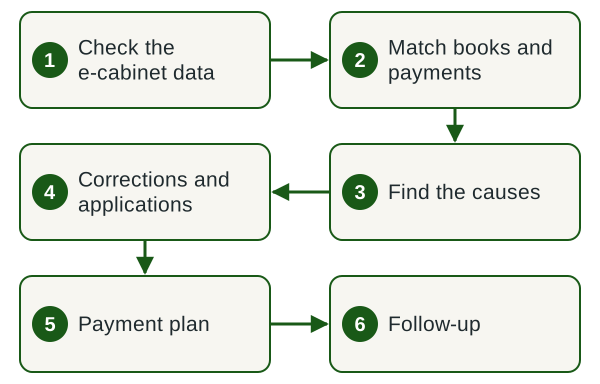
- Check the e-cabinet data We export the settlement status for each tax and budget.
- Match books and payments We compare it with the books, returns and bank statements.
- Find the causes We explain each difference and who needs to correct it.
- Corrections and applications We prepare amended returns, refund or offset applications and appeals.
- Payment plan We set a payment calendar and, if needed, an instalment request.
- Follow-up We confirm the changes appear in the e-cabinet.
Timelines
Our timing depends on the number of taxes and years, the state of the source documents and whether the books need restoring. A refund application must be filed within 1,095 days of the overpayment (para. 43.3), so older overpayments are checked first.
What affects the cost
- the number of taxes and budgets with differences;
- the number of periods to reconcile;
- the state of the books and source documents;
- tax assessment notices and appeals;
- an instalment request with economic justification.
The fee is agreed individually after a first look at the e-cabinet statement.
What we need from you
- The settlement statement from the taxpayer's e-cabinet.
- Returns filed for the reconciliation period.
- Bank statements showing tax payments.
- Tax assessment notices, audit reports and tax authority letters, if any.
- Access to the accounting database or tax ledgers.
Result
- A reconciliation for each tax with the differences explained.
- Filed applications, amended returns and appeals.
- A refunded or offset overpayment, a settled or rescheduled debt.
- A tax payment calendar.
Find out the cost
Send us the e-cabinet settlement statement and tell us what does not match. We will reply with the scope and the fee.
Legal framework
Rules the work relies on
- Tax Code, para. 42-1.2 — reconciliation of settlements in the electronic cabinet.
- Tax Code, Art. 43 — refund of overpaid amounts, the 1,095-day limit and refund deadlines.
- Tax Code, Arts. 50 and 56 — amended returns and administrative appeals.
- Tax Code, para. 87.9 and Art. 100 — order of applying payments to debt, instalments and deferrals.
- Tax Code, subpara. 129.1.3, para. 129.4 — when late-payment interest starts and its rate.
- Tax Code, subparas. 69.37, 69.38 of para. 69, subsection 10, Section XX — martial-law relief from fines and interest.
Risks and why to hand the work to a team under contract
An unnoticed debt accrues late-payment interest every day at 120% of the NBU discount rate per year (para. 129.4; on self-assessed amounts after 90 days of delay), and an overpayment older than 1,095 days can no longer be recovered by application. A tax debt above 10 minimum wages for more than 30 days bars a company from Diia City status (Art. 5(2) of Law No. 1667-IX). During a documentary tax audit the company may not file amended returns for the audited period (para. 50.2), so errors are corrected beforehand. Key Solutions is responsible for the reconciliation and filings under contract; court disputes with the tax authority are handled by legal.ua.
Why Key Solutions
- Company
- AUDIT FIRM KEY SOLUTIONS LLC (ТОВ «АУДИТОРСЬКА ФІРМА «КЕЙ СОЛЮШНЗ»), EDRPOU code 39610085. The company's details are public in the Unified State Register (ЄДР).
- Contract
- We work under a contract: the scope, deadlines and responsibility are agreed before the work starts. Client information is protected by professional secrecy (Art. 11 of Law No. 2258-VIII).
- Group
- We are part of Innova Consulting Group: legal matters are handled by legal.ua, crypto-asset taxation by crystal.tax.
- Office
- Our office is at 77 Velyka Vasylkivska Street, Kyiv. Clients elsewhere in Ukraine are served remotely. The specialists who run our projects are listed on the Our employees page.
Frequently asked questions
How do I reconcile my tax account with the Ukrainian tax authority?
Start with the settlement statement in the taxpayer's electronic cabinet (Tax Code, para. 42-1.2). Each tax balance is then compared with the books, returns and bank payments, and every difference gets an explanation and a way to correct it.
How can a company get a tax overpayment refunded in Ukraine?
By filing a free-form application within 1,095 days of the overpayment (paras. 43.3, 43.4). The company chooses a bank account or an offset against other tax liabilities. If it has a tax debt, the refund is made only after the debt is paid (para. 43.2).
Can an overpayment be offset against another tax?
Yes. The refund application may direct the money to other liabilities or debts controlled by the tax authority, regardless of the budget (para. 43.4). The application must be filed within 1,095 days of the overpayment (para. 43.3).
Can tax debt be paid in instalments?
Yes. The company applies with evidence of circumstances threatening a tax debt and an economic justification of its ability to pay (para. 100.4). Instalments are repaid in equal parts with interest at 120% of the NBU discount rate per year (para. 100.1).
Is tax optimisation legal in Ukraine?
Yes, when it relies on choices the Tax Code provides: the tax system, the way contractors are engaged, the structure of deals. Each decision must match real business activity and be documented, which is why we agree the plan before the transactions.
How much does a tax account reconciliation cost?
The fee is agreed individually and depends on the number of taxes and periods, the state of the books and any applications or appeals needed. We quote after reviewing the e-cabinet statement and fix the amount in the contract.
Related services
Let's reconcile your tax account
Send us the e-cabinet settlement statement and a short note on what does not match your books. We will reply with the causes we can see straight away, the scope and the fee.
Book a consultation Order the service +38 (068) 777-14-74 Telegram WhatsApp