

Accounting and reporting for an Estonian OÜ means an annual report filed with the e-Business Register within 6 months of the financial year end, even for a year without activity, a monthly TSD return by the 10th for the previous month's payments (salaries, management board fees, dividends), a monthly KMD VAT return by the 20th if the company is VAT-registered, an audit or review once the statutory limits are exceeded, and 22/78 corporate income tax that is paid only when profit is distributed. Key Solutions coordinates this work for owners from Ukraine: an Estonian partner accountant keeps the books and files the returns, a sworn auditor (vandeaudiitor) carries out any audit or review, the management board approves the annual report, and we set the tasks, check deadlines and figures and prepare owner reporting.
Request a tailored proposal Telegram
In short
- For: owners from Ukraine who have or plan an Estonian private limited company (osaühing, OÜ), including one opened through e-Residency, and groups where the Estonian company invoices clients in the EU.
- What we do: take over the books from the previous accountant, set up the EMTA and register calendar, monitor TSD, KMD, board fees and dividends, prepare the annual report and any audit, keep the contact person and register data current, and give the owner clear reporting.
- Who files: an Estonian partner accountant prepares and files TSD and KMD; the management board (juhatus) approves and signs the annual report; a sworn auditor signs the auditor's report.
- Cost: a tailored proposal after a short description of the company, with no public price list.
- To start: send the OÜ registry code, where the management board actually works, whether the company is VAT-registered and pays board members or employees, last year's turnover and who keeps the books today.
What an Estonian OÜ files and when
An Estonian company reports to two places. The Tax and Customs Board (EMTA, Maksu- ja Tolliamet) receives the monthly TSD and KMD returns through e-MTA. The e-Business Register run by the Centre of Registers and Information Systems (RIK) receives the annual report, which becomes public. The deadlines below are taken from emta.ee and rik.ee as of 10.2026.
| What to file or pay | When | Where and source |
|---|---|---|
| TSD (income and social tax return) | By the 10th of the month after the month of payment; if the 10th is a day off, the next working day | EMTA, e-MTA; emta.ee: TSD |
| Income tax on dividends | TSD Annex 7 and form INF 1 by the 10th of the month after the dividend is paid; payment by the same date | EMTA; emta.ee: taxation of dividends |
| KMD and KMD INF (VAT) | Monthly by the 20th of the following month, both filing and payment; a return is due even without transactions | EMTA; emta.ee: VAT returns |
| VAT registration | When taxable supplies with an Estonian place of supply exceed €40,000 from the start of the year | EMTA; emta.ee: VAT registration |
| Annual report | Within 6 months of the financial year end, including a year without activity; 30 June for a calendar year | e-Business Register; rik.ee: annual report |
| Audit or review | With the annual report, when the figures exceed the limits in § 91 or § 92 of the Auditors Activities Act | Sworn auditor; Riigi Teataja: AudS |
| Contact person | At all times when the management board is located abroad; the register shows the contact person's term of office and the board's foreign address | e-Business Register; § 63¹ of the Commercial Code, emta.ee |
Corporate income tax: the 22/78 model
An Estonian company pays corporate income tax when it distributes profit: dividends and other payments the law treats as distributions. Profit kept in the company is not taxed. The rate is 22/78 of the net payment, which equals 22% of the gross amount (emta.ee: taxation of dividends).
| Item | 2025 | 2026 |
|---|---|---|
| Tax on distributed profit | 22/78 | 22/78 |
| Reduced 14/86 rate for regular dividends | Abolished from 01.01.2025 | Abolished |
| 7% withholding on dividends to individuals | Abolished, except redistribution of dividends taxed at 14/86 up to the end of 2024 | Same |
| Withheld income tax | 22% | 22% |
| Social tax | 33% | 33% |
| Unemployment insurance | 0.8% employer, 1.6% employee | Unchanged |
| Funded pension | 2% by default (4% or 6% on application) | Unchanged |
Rates are taken from emta.ee: tax rates as of 10.2026. Older guides and some websites still quote 20/80 and 14/86 or forecast "24% corporate tax from 2026". For 2026 EMTA lists the 22/78 rate, and 24% is the standard VAT rate. The emta.ee example: on a net dividend of €1,200 the company pays €338.46 in tax (1,200 × 22/78).
The tax on dividends goes in TSD Annex 7 and the recipients in form INF 1. The payment date is the date of the source document or accounting entry, so a dividend booked as a debt to the shareholder also starts the deadline. Our group's tax practice reviews the tax side of distributions, the owner's residence and the tax treaty: crystal.tax: company in Estonia.
Management board fees and payroll
Fees paid to a non-resident management board member are subject to Estonian income tax and social tax wherever the member works. Social tax is not due when the recipient holds a valid A1 certificate from their home country. A board member receiving taxable fees is registered in the employment register (emta.ee: tax liabilities of companies established by e-residents). Payments are declared in TSD by the 10th of the following month.
Starting with payments for October 2026 (TSD due 10 November), payment data can be sent directly from accounting software: EMTA builds the return and calculates the tax, and errors come back to the software straight after submission (emta.ee). The books we set up run in software with this connection.
VAT: threshold, rates, KMD
- Registration is mandatory once taxable supplies with an Estonian place of supply exceed €40,000 from the start of the year. Since 01.01.2025 zero-rated supplies count towards the threshold, except sales of fixed assets. If a company applies late, EMTA registers it retroactively from the date the threshold was exceeded (emta.ee).
- VAT rates: 24% standard from 01.07.2025 (previously 22%), 13% for accommodation from 01.01.2025, 9%, including press publications from 01.01.2025, 0% for certain supplies (emta.ee: VAT).
- The tax period is a calendar month. KMD and its annex KMD INF are due by the 20th of the following month, and VAT is paid by the same date. Paper filing is allowed if the company has been VAT-registered for less than 12 months or the annex lists fewer than five invoices.
- A business from another EU Member State without a permanent establishment in Estonia may appoint a tax representative when registering for VAT.
Annual report, company size and audit
The annual report is filed electronically through the e-Business Register within 6 months of the financial year end, even if the company had no activity. The completion date is the date the management board approves it, and it can be signed digitally. Micro and small undertakings may file abridged accounts: a balance sheet, an income statement and notes; a micro undertaking does not file a management report. For a missing report the registrar may fine the company without warning, and if the report is still missing six months after the deadline a supervisory procedure starts, which may end with deletion from the register or compulsory dissolution (rik.ee: annual report).
The audit or review obligation is set by the Auditors Activities Act (Audiitortegevuse seadus) in the version in force from 17.01.2025 (Riigi Teataja):
| Obligation | Two of three indicators exceed | Or one indicator exceeds |
|---|---|---|
| Audit (§ 91) | Revenue €5,000,000, assets €2,500,000, 50 employees | Revenue €15,000,000, assets €7,500,000, 180 employees |
| Review (§ 92) | Revenue €2,000,000, assets €1,000,000, 24 employees | Revenue €6,000,000, assets €3,000,000, 72 employees |
A review can be replaced by an audit. An OÜ below the § 92 limits has no statutory audit or review, yet a bank, payment provider or counterparty may ask for checked accounts, so we plan the year-end schedule from the first year.
Management board abroad and the contact person
When the management board of an OÜ is located abroad, meaning management decisions are made outside Estonia, the company appoints a contact person with an Estonian address and enters the board's foreign address in the register. The contact person can be a notary, an advocate or law office, a sworn auditor or audit firm, a non-resident's tax representative or a trust and company service provider; if a board member, shareholder or procurator lives in Estonia, that person can also be designated (§ 63¹ of the Commercial Code, emta.ee). Since 01.02.2023 the register also shows the contact person's term of office (rik.ee).
EMTA also warns that a company managed from abroad will probably have a permanent establishment in another country, where its profit may be taxed. E-residency gives no automatic exemption from foreign tax (emta.ee). For an OÜ managed from Ukraine we settle this with crystal.tax before the first profit distribution.
Taking over the books
When the company already trades, we start with the e-Business Register record: status, management board, contact person and filed annual reports. We then reconcile bank and payment accounts, check the filed TSD and KMD returns, VAT registration, board fees and dividends. Differences are recorded in a handover report. If an annual report is missing, we rebuild the books and file it to stop the registrar's procedure.
What the service includes
- diagnostic: register data, contact person, history of annual reports, TSD and KMD, VAT, board fees;
- selecting and setting up the Estonian partner accountant: scope, document flow, access to e-MTA and the register;
- bookkeeping in software that sends payment data directly to EMTA;
- checks on TSD, KMD and KMD INF before each deadline;
- dividend paperwork and reporting: shareholder resolution, TSD Annex 7, INF 1;
- annual report and coordination of an audit or review where required;
- monitoring the contact person and their term of office;
- management reporting for the owner: profit, cash flow, taxes due;
- a financial statements pack for the Ukrainian owner's CFC report and consolidation with a Ukrainian LLC on request.
How we work
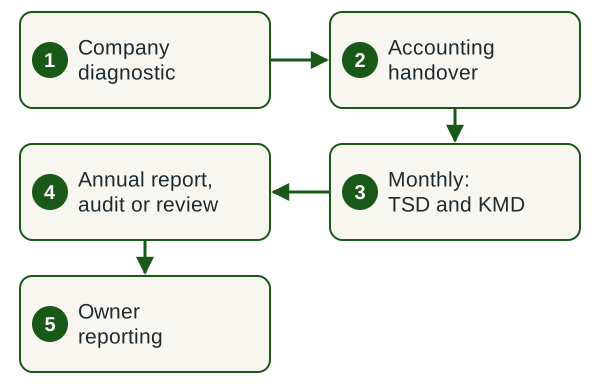
- Diagnostic. We obtain the register extract, the latest annual report, TSD and KMD, and check VAT and the contact person.
- Handover. We take over the books from the previous accountant against a checklist and record differences.
- Monthly cycle. Documents, bank reconciliation, TSD by the 10th, KMD by the 20th.
- Annual cycle. Annual report, audit or review where required, filing with the register.
- Owner reporting. Management report, CFC and consolidation pack.
Reporting for the owner in Ukraine
For an owner who is tax resident in Ukraine, an Estonian company is often a controlled foreign company: a stake above 50%, or above 10% when Ukrainian residents together hold 50% or more (subparagraph 39-2.1.2 of the Tax Code of Ukraine). Certified copies of the company's financial statements are attached to the CFC report (subparagraph 39-2.5.2), so the Estonian annual report is needed in Ukraine too. We prepare the reporting and CFC pack together with our reporting for foreign companies service. An overview of entering the Estonian market for the group is on innovacg.com.
Registration and residence within the group
Company registration in Estonia, tax structure and permanent establishment questions are covered by crystal.tax. An Estonian company and e-resident status by themselves give no right to live in Estonia. Key Solutions joins when the company exists or is being registered and is responsible for accounting and reporting.
What we need from you
- OÜ name and registry code, or the planned registration date;
- the latest annual report, TSD and KMD returns if the company already trades;
- bank and payment account statements and a list of main counterparties, including in the EU;
- management board members, where the board actually works, contact person details;
- payments to board members and employees, dividend resolutions;
- contacts of the previous accountant and auditor, if any;
- the shareholders and their tax residence for the CFC pack.
We accept documents electronically and never need bank passwords.
The result
- TSD and KMD filed every month on time, taxes paid;
- dividends documented and declared under the 22/78 rule;
- annual report filed with the e-Business Register within 6 months, with an audit or review where required;
- management board and contact person data in the register up to date;
- management report and CFC pack for the owner;
- a deadline calendar for the next year.
Legal basis and sources
Official sources behind this page (emta.ee, rik.ee, Riigi Teataja, checked 10.2026)
- EMTA: tax rates 2025–2026 — 22/78, income tax, social tax, contributions;
- EMTA: taxation of dividends — TSD Annex 7, INF 1, deadline;
- EMTA: submission of TSD — deadline on the 10th;
- EMTA: filing VAT returns, EMTA: VAT registration — KMD, €40,000 threshold;
- EMTA: companies established by e-residents — board fees, permanent establishment;
- RIK: annual report — 6-month deadline, consequences of non-filing;
- Audiitortegevuse seadus — § 91 (audit), § 92 (review);
- EMTA: e-services and communication — § 63¹ of the Commercial Code, contact person; RIK — term of office;
- Tax Code of Ukraine, subparagraphs 39-2.1.2 and 39-2.5.2: controlling person and CFC report.
Why Key Solutions
- Company
- KEY SOLUTIONS AUDIT FIRM LLC, Ukrainian company code 39610085, registered since 30.01.2015.
- Roles
- Estonian books, TSD and KMD are handled by an Estonian partner accountant; any audit or review by a sworn auditor; the management board approves and signs the annual report; coordination, control and owner reporting are done by Key Solutions.
- Group
- We are part of Innova Consulting Group: tax matters in Estonia and the owner's CFC by crystal.tax, market entry by innovacg.com.
- Contract
- Scope, liability and confidentiality are set in a contract before work starts.
FAQ
What does an Estonian OÜ file?
Every month, a TSD return by the 10th for the previous month's payments and, if the company is VAT-registered, a KMD return by the 20th. Every year, an annual report with the e-Business Register within 6 months of the financial year end, with an audit or review when the figures exceed the statutory limits.
What is the Estonian corporate income tax rate in 2026?
The company pays tax only when it distributes profit, at 22/78 of the net payment; emta.ee lists this rate for both 2025 and 2026. The reduced 14/86 rate was abolished from 01.01.2025. The 24% rate in 2026 is the standard VAT rate.
Is an annual report needed if there was no activity?
Yes. The annual report is filed within 6 months of the financial year end even for a year without activity. For a missing report the registrar may fine the company without warning and later start a procedure that can end in deletion from the register.
When does an OÜ need an audit?
When two of three indicators exceed €5,000,000 revenue, €2,500,000 assets and 50 employees, or one indicator exceeds €15,000,000, €7,500,000 or 180 employees (§ 91 of the Auditors Activities Act, version from 17.01.2025). The lower limits of § 92 trigger a mandatory review.
How are a non-resident board member's fees taxed?
With Estonian income tax and social tax wherever the member works; social tax is not due with a valid A1 certificate. Payments are declared in TSD by the 10th of the following month.
Is a contact person required if the board is in Ukraine?
Yes, when the management board is located abroad. The contact person can be a notary, advocate, sworn auditor, non-resident's tax representative, company service provider, or a board member or shareholder living in Estonia (§ 63¹ of the Commercial Code), and the register shows their term of office.
Who keeps the books when the owner is in Ukraine?
An Estonian partner accountant keeps the books and files TSD and KMD, the management board approves and signs the annual report, and a sworn auditor carries out any audit or review. Key Solutions sets the tasks, checks deadlines and figures and prepares owner reporting, including the CFC pack.
How much does accounting support for an OÜ cost?
It depends on transaction volume, VAT registration, payments to board members and staff, dividends and the state of past records. We prepare a tailored proposal after a short description of the company.
Related services
Request a tailored proposal for your Estonian OÜ's accounting
Send the company's registry code, where the management board works, whether it is VAT-registered and makes payments, last year's turnover and who keeps the books today. We will reply with the scope, the split of roles and how to start.
Request a tailored proposal Telegram WhatsApp