


Tax optimisation is the lawful choice among options the Ukrainian Tax Code provides directly: the tax regime, the group structure, contract models and specific relief. Key Solutions models your tax burden under several scenarios, tests each transaction for business purpose and aligns contracts and accounting policy with the chosen model.
+38 (068) 777-14-74 Telegram WhatsApp
In short
- When you need it: launching a business or new line, approaching single-tax or VAT thresholds, dealing with non-residents, splitting or merging companies.
- What you get: the tax burden under two or three scenarios, the risks of each and a transition plan.
- Timing: in our experience, a regime choice for one company takes a few working days after we receive the data; a group review takes longer.
- Fee: agreed individually, based on the number of entities, cross-border transactions and the state of the accounts.
- How to start: describe your business model and send last year's statements.
Where the line between optimisation and evasion lies
The line is drawn by two tests: the transaction is real and it has a business purpose. The Tax Code prohibits building tax figures on data not supported by documents (para. 44.1 of the Tax Code), and a business purpose exists only where the taxpayer intends to obtain an economic effect (subpara. 14.1.231 of the Tax Code). Saving tax cannot be the stated purpose of a transaction.
Choosing a tax regime
The regime choice has the biggest effect. Single-tax revenue caps are tied to the minimum wage on 1 January, which is UAH 8,647 in 2026.
Source: Arts. 136, 291, 293 of the Tax Code of Ukraine
| Regime | Who can use it | Rate |
|---|---|---|
| General regime | Any legal entity | 18 % corporate income tax (para. 136.1) |
| Single tax, group 2 | Sole proprietors, up to 10 employees, revenue up to UAH 7,211,598 in 2026 | Up to 20 % of the minimum wage per month |
| Single tax, group 3 | Sole proprietors and legal entities, revenue up to UAH 10,091,049 in 2026 | 3 % of revenue plus VAT, or 5 % including VAT (para. 293.3) |
| Diia City | IT companies meeting residency criteria | 9 % of the tax base (para. 136.8) |
VAT registration becomes mandatory once taxable supplies exceed UAH 1,000,000 over 12 months, except for single-tax groups 1–3 (para. 181.1 of the Tax Code). Parliament has been discussing VAT rules for single-tax payers, so we check the current text of the Code before any decision.
What the service includes
- a review of your activities, revenue and cost structure, related parties and non-resident counterparties;
- a check of the current regime against Tax Code restrictions and revenue thresholds;
- modelling of alternatives with the effective tax rate for each scenario;
- a business purpose test for planned transactions, with supporting documents;
- changes to contracts and accounting policy for the chosen model;
- a request for an individual tax ruling where the law is ambiguous.
How we work
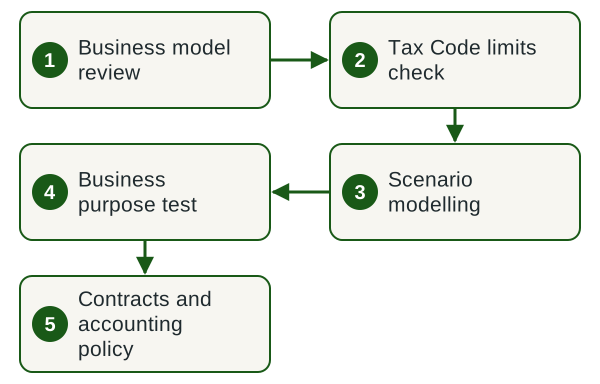
- Business model review. We look at revenue, costs, counterparties and ownership.
- Tax Code limits check. We test the current regime against single-tax, transfer pricing and VAT rules.
- Scenario modelling. We calculate taxes and contributions for two or three options on your forecast.
- Business purpose test. We check that each transaction can answer the tax authority's questions.
- Contracts and accounting policy. We prepare contract changes, policy updates and a dated transition plan.
Timing and fees
A regime choice for one company or sole proprietor usually takes a few working days after we receive the data; a group with non-resident transactions takes longer. The tax authority must answer a request for an individual tax ruling within 25 calendar days (para. 52.1 of the Tax Code). The fee is agreed individually and fixed in the contract.
What we need from you
- A description of what you sell, to whom and through which entities.
- Last year's financial and tax statements and a revenue forecast.
- A list of related parties and non-resident counterparties.
- Key contracts with customers, suppliers and group companies.
What you receive
- a tax burden table for two or three scenarios with effective rates;
- a risk assessment for each scenario with references to the Tax Code;
- a transition plan with dates, contract and policy changes;
- a list of documents supporting the business purpose of key transactions.
Legal basis
Legal basis for the work
- subparas. 14.1.159 and 14.1.231 of the Tax Code — related parties, business purpose.
- Arts. 291 and 293 of the Tax Code — simplified regime, groups, rates and caps.
- Art. 39 of the Tax Code — controlled transactions and transfer pricing.
- Arts. 50, 112 and 123 of the Tax Code — self-correction, liability, penalties.
Legal restructuring is handled by our group company legal.ua, crypto-asset taxation by crystal.tax.
Why Key Solutions
- Company
- ТОВ «АУДИТОРСЬКА ФІРМА «КЕЙ СОЛЮШНЗ», a Ukrainian limited liability company, EDRPOU code 39610085. The company's details are public in the Unified State Register (ЄДР).
- Contract
- We work under a contract: scope, timing and liability are agreed before work starts. Client information is protected by professional secrecy (Art. 11 of Law No. 2258-VIII).
- Group
- Key Solutions is part of Innova Consulting Group: legal matters are handled by legal.ua, crypto-asset taxation by crystal.tax.
- Office
- Our office is at 77 Velyka Vasylkivska St., Kyiv. We serve clients across Ukraine remotely. The specialists who run engagements are listed on the Our employees page.
Frequently asked questions
Is tax optimisation legal in Ukraine?
Yes, when it uses options the Tax Code provides directly and every transaction is real, has a business purpose and is backed by primary documents. Reporting transactions that did not happen, or transactions whose only point is to cut tax, is evasion and leads to additional tax, penalties of 10–50 % and late-payment interest.
Which tax regime should a Ukrainian LLC choose?
It depends on expected revenue, cost structure, owners and customers. The general regime means 18 % corporate income tax; group 3 of the simplified regime means 3 % of revenue plus VAT or 5 % including VAT, with a 2026 revenue cap of UAH 10,091,049. Companies with high documented costs usually do better on the general regime.
What is a business purpose and why does it matter?
Under subpara. 14.1.231 of the Tax Code a business purpose exists only if the taxpayer intends to obtain an economic effect, such as growth or preservation of assets. For transactions with non-residents the Code names two cases where it is deemed absent, for example when the main purpose is to avoid tax. We document the commercial reasons before the transaction.
When are transactions treated as controlled for transfer pricing?
Transactions with related non-residents and certain other non-residents are controlled when the taxpayer's annual revenue exceeds UAH 150 million and transactions with one counterparty exceed UAH 10 million. The controlled transactions report is due by 1 October of the following year, and documentation must be provided within 30 days of a request.
Is the Diia City regime a form of tax optimisation for IT companies?
It is a lawful regime set by the Tax Code: Diia City residents paying tax under special conditions pay 9 % on the tax base. Residency requires average monthly pay of at least the equivalent of EUR 1,200, at least nine engaged specialists and at least 90 % qualified income. We model it against the standard regime before you apply.
How much does tax optimisation advice cost?
The fee is agreed individually. It depends on the number of companies and sole proprietors in the structure, transactions with non-residents and related parties, the state of the accounts and the format: a one-off consultation, scenario modelling or support through the change. We quote after a first call and a look at your statements.
Related services
Let's model your tax burden
Describe your business model, revenue forecast and the entities involved. We will reply with the format, timing and fee.
Book a consultation Order the service +38 (068) 777-14-74 Telegram WhatsApp