

Tax advisory is a specialist's answer to a specific business tax question, backed by the Tax Code of Ukraine (ПКУ) and a risk assessment. Key Solutions advises companies, including foreign-owned ones, and sole proprietors in Kyiv and remotely, before a deal and during tax audits.
+38 (068) 777-14-74 Telegram WhatsApp
In short
- When you need it: a new contract, a payment to a non-resident, a choice of tax regime, a request or audit from the State Tax Service (ДПС).
- What you get: an answer with references to the Tax Code, or a written opinion with options and the risk of each.
- Timing: agreed in the contract after we review the documents.
- Cost: depends on the complexity of the question, the form of the answer and the volume of documents.
- How to start: describe the question and attach the contract or the tax authority letter.
What a tax consultant in Ukraine handles
The work is preventive (tax before a transaction), current (corrections without penalties) or defensive (a dispute with the tax authority). Typical tasks:
- a tax regime for a new subsidiary, representative office or sole proprietor;
- royalties, services from non-residents, dividends and related-party transactions;
- an error found in a return that has already been filed;
- a request, audit report or tax notice-decision (податкове повідомлення-рішення) from the tax authority.
What the service covers
- tax consequences of a contract before it is signed: VAT, corporate income tax, personal income tax (ПДФО) and military levy;
- VAT registration, tax invoices and VAT refunds from the budget;
- payroll taxes and the unified social contribution (ЄСВ) for employers;
- lawful tax optimisation and a change of tax regime;
- objections to audit reports and administrative appeals.
We consult at our Kyiv office, by phone or online: orally, with a written opinion, or as ongoing support under a contract.
How we work
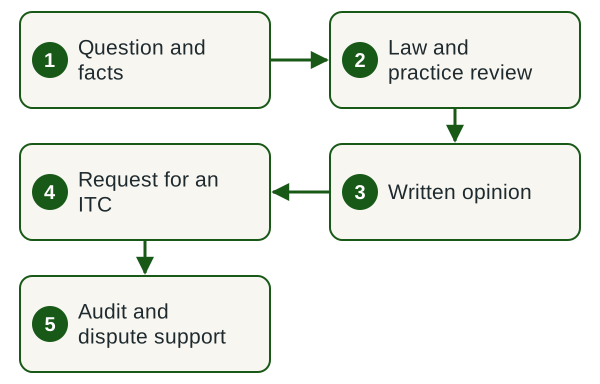
- Question and facts We record the facts and the question you need answered.
- Law and practice review We check the Tax Code, secondary legislation, court practice and the register of tax consultations.
- Written opinion We set out the options and the risk of each.
- Request for an ITC When needed, we prepare a request for an individual tax consultation.
- Audit and dispute support We prepare objections to an audit report and an administrative appeal.
Timing
We set the deadline for a written opinion after reviewing the documents and fix it in the contract. Tax authority deadlines come on top: an individual tax consultation (індивідуальна податкова консультація, ITC), Ukraine's form of a private tax ruling, is issued within 25 calendar days, extendable by up to 15 days (para 52.1 of the Tax Code).
What affects the cost
- the number and complexity of the questions;
- oral advice or a written opinion;
- the volume of contracts, primary documents and returns to review;
- tax authority deadlines that are already running.
We quote after a short description of the situation and fix the fee before work starts.
What we need from you
- A short description of the situation and the question.
- Contracts, primary documents and returns for the period in question.
- Any tax authority letter, with the date you received it: deadlines run from that date.
- Your tax regime and VAT registration status.
Result
- An answer with references to specific articles of the Tax Code and other laws.
- A written opinion with options and the risk of each, if you choose this format.
- A draft ITC request when you need the official position of the tax authority.
- A list of actions and deadlines.
Payments to non-residents and double tax treaties
A Ukrainian payer withholds 15% tax from Ukrainian-source income paid to a non-resident unless a double tax treaty in force provides otherwise (sub-para 141.4.2 of the Tax Code). Treaty relief applies if the recipient is the beneficial owner of the income and provides a legalised and translated certificate of tax residence (paras 103.2, 103.4 and 103.5). Without the certificate, the income is taxed under Ukrainian law (para 103.10). More on this: working with non-residents and transfer pricing in Ukraine.
Legal framework
Rules the work relies on
- Arts. 52 and 53 of the Tax Code — individual tax consultations and their legal effect.
- Sub-para 112.8.2 of the Tax Code — release from penalties when acting under a registered ITC.
- Art. 56 of the Tax Code — administrative and court appeals.
- Art. 103 and sub-para 141.4.2 of the Tax Code — withholding tax on non-residents and treaty relief.
Risks, and why to hand this to a team under contract
A tax error has a price set by law: 10% of the liability assessed by the tax authority, 25% if intentional and 50% if repeated within 1,095 days (Art. 123 of the Tax Code), plus late-payment interest. We work under a contract and give written opinions with references to the law; the group's lawyers at legal.ua take disputes to court. To check the books before an inspection, see audit before a tax inspection.
Why Key Solutions
- Company
- ТОВ «АУДИТОРСЬКА ФІРМА «КЕЙ СОЛЮШНЗ», a Ukrainian limited liability company, EDRPOU code 39610085. The company's details are public in the Unified State Register (ЄДР).
- Contract
- We work under a contract: scope, timing and liability are agreed before work starts. Client information is protected by professional secrecy (Art. 11 of Law No. 2258-VIII).
- Group
- Key Solutions is part of Innova Consulting Group: legal matters are handled by legal.ua, crypto-asset taxation by crystal.tax.
- Office
- Our office is at 77 Velyka Vasylkivska St., Kyiv. We serve clients across Ukraine remotely. The specialists who run engagements are listed on the Our employees page.
Frequently asked questions
How does a tax consultant differ from an accountant?
An accountant records transactions after they happen. A tax consultant works out the tax consequences before a transaction and defends the taxpayer's position in a dispute with the tax authority.
Does an individual tax consultation protect against penalties?
Yes, if it was issued to you in paper or electronic form and entered in the unified register. Acting in line with it releases you from penalties (sub-para 112.8.2 of the Tax Code) and late-payment interest (sub-para 129.9.2); the tax itself is still payable (para 53.1).
Can a tax notice-decision be appealed without going to court?
Yes. An administrative appeal to the higher-level tax authority is filed within 10 working days of receiving the decision and suspends payment of the disputed amount (paras 56.3 and 56.15 of the Tax Code). The decision on the appeal is due within 20 calendar days (para 56.8).
How far back can the tax authority assess additional tax?
As a general rule, 1,095 days after the filing deadline for the return; for transfer pricing and para 141.4 cases, 2,555 days (para 102.1 of the Tax Code). Transitional provisions suspended these periods, so we calculate the date for each period separately.
How much does a tax consultation cost?
It depends on the number and complexity of the questions, the form of the answer and the volume of documents. We quote after a short description and fix the fee in the contract or invoice before work starts.
Do you advise sole proprietors (FOP)?
Yes. We advise sole proprietors (ФОП) on the single-tax group and its income limit, the unified social contribution, VAT registration and payments to non-residents, at our Kyiv office, by phone or online.
Related services
Let's discuss your tax question
Briefly describe the situation and tell us whether you have received a letter or decision from the tax authority, and on what date. We will reply with the format, timing and a fee estimate.
Book a consultation Order the service +38 (068) 777-14-74 Telegram WhatsApp